Strip out IDEX's acquisitions and its owners' equity turns negative
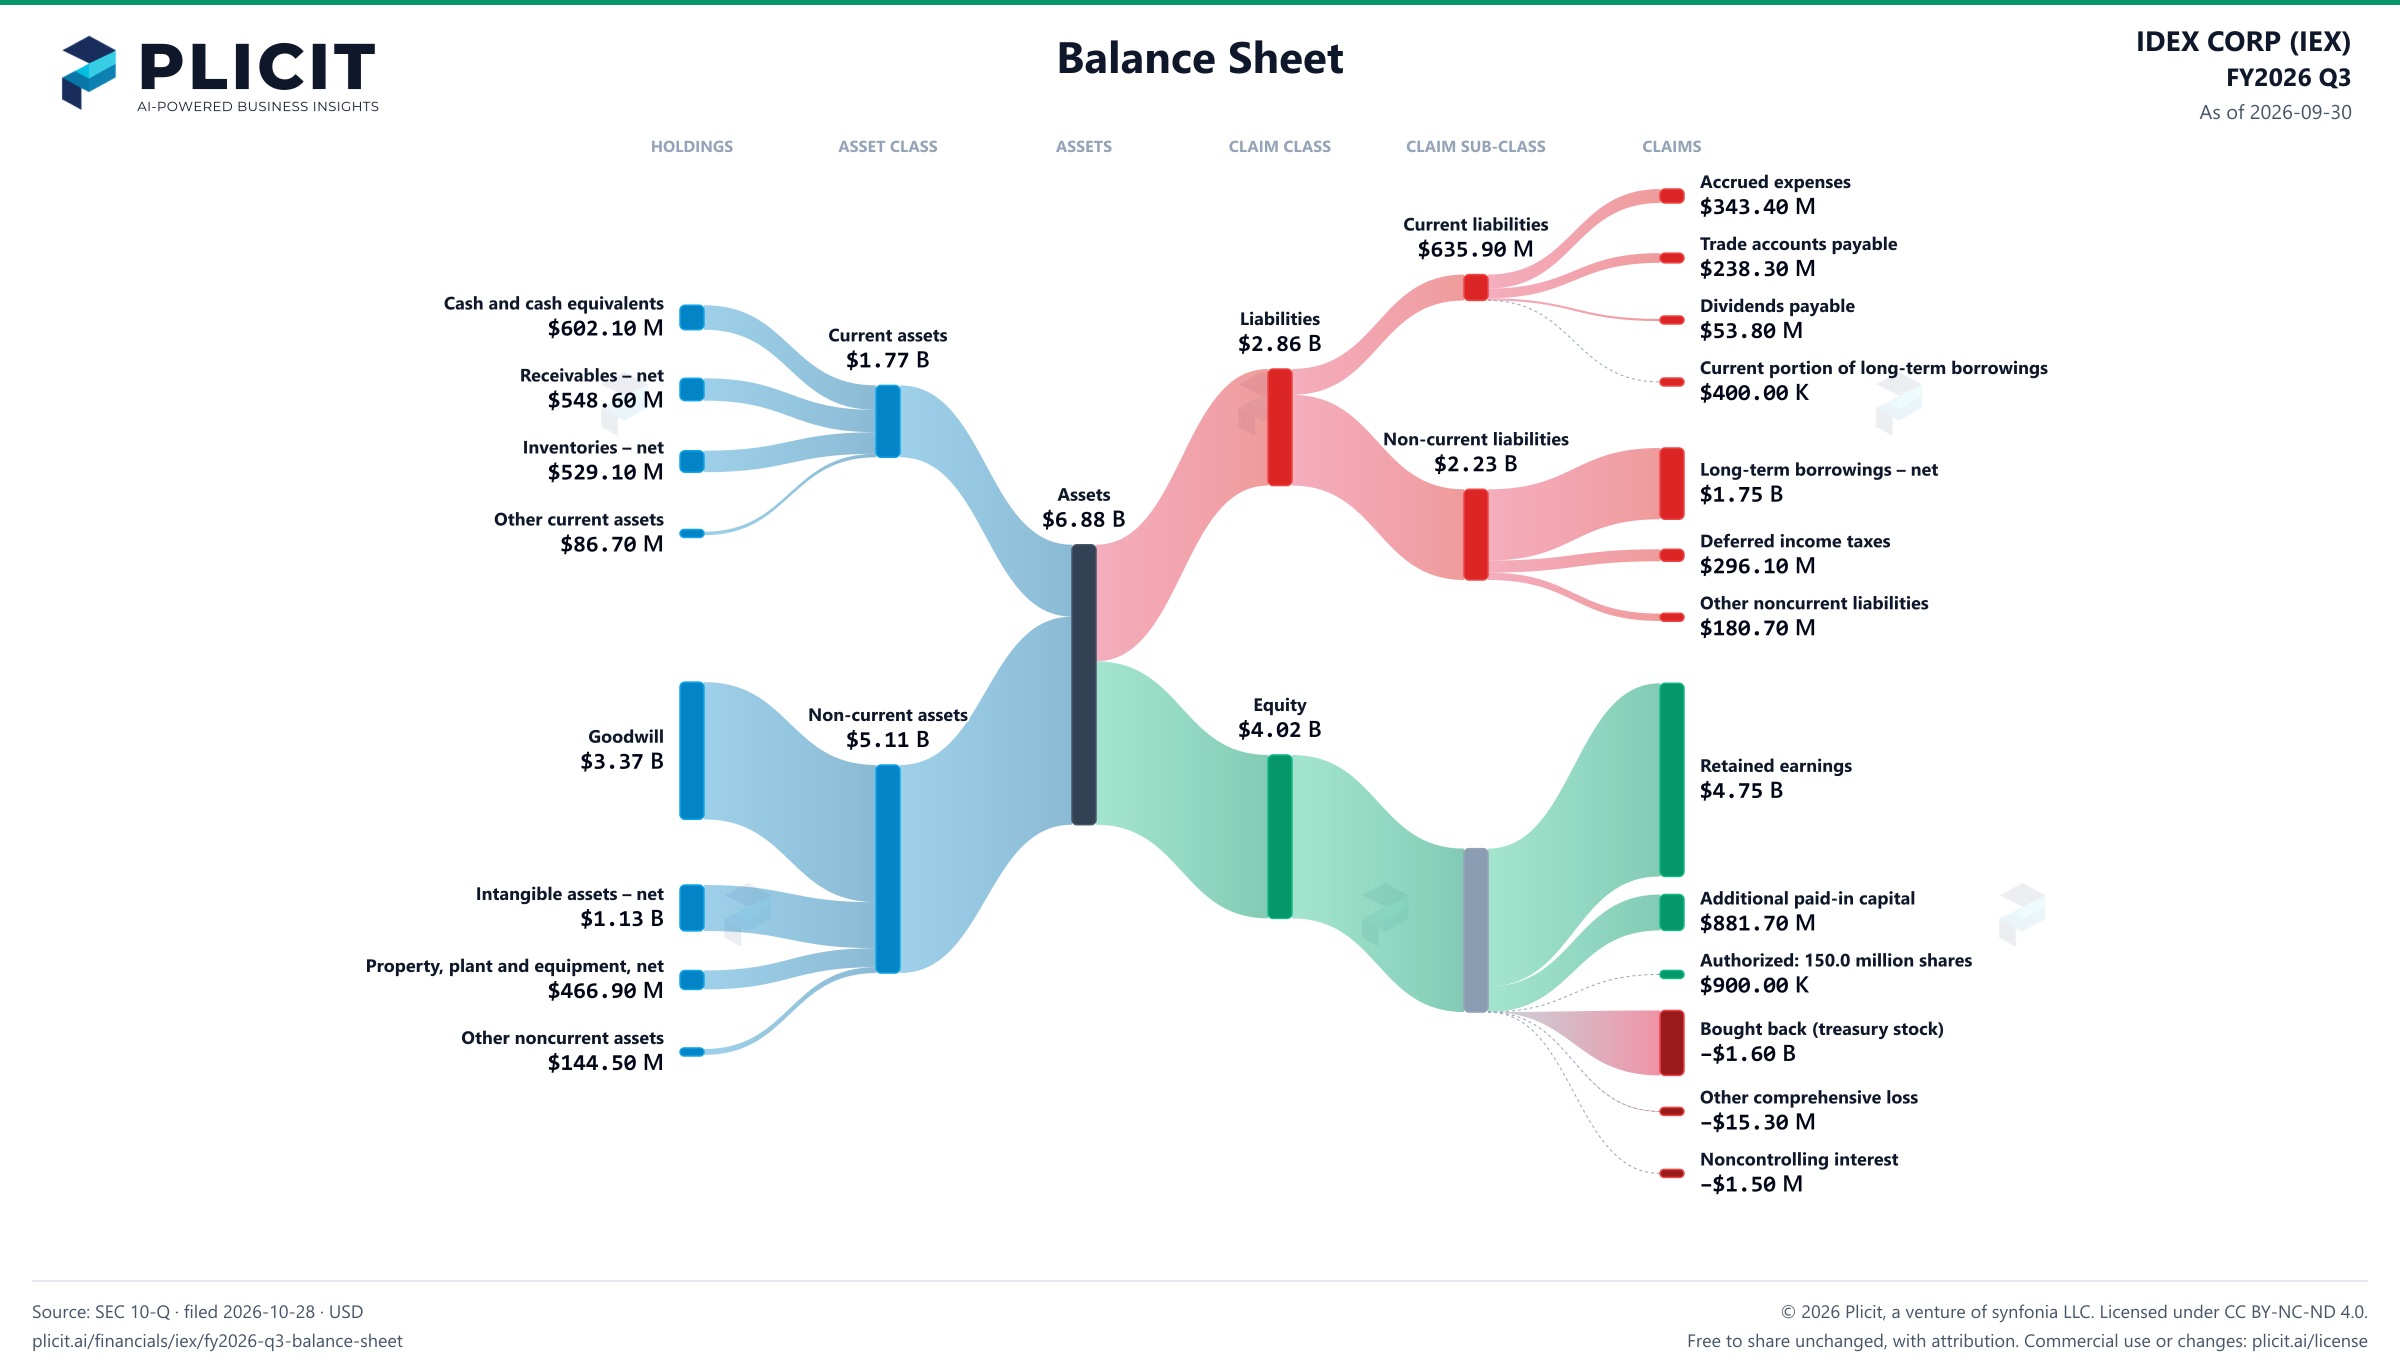
IDEX looks sturdy on the surface, yet its equity depends on the prices it paid for other companies. Goodwill and intangible assets total $4.50 B, 65% of everything the company owns, and that is more than all of its $4.02 B of shareholder equity. Strip the acquisitions out and equity sits below zero at -$484.40 M. Why would a company with $6.88 B of assets be so thin on its own tangible value? The answer starts with what it paid for.
Goodwill is where the money went. Health & Science Technologies holds 66% of that goodwill, according to the filing's goodwill table. Debt is the other side of the story: IDEX drew $260.0 M on its revolving credit line in the first nine months, and the filing says the money was used for general corporate purposes, including to finance share repurchases. Of its $602.10 M of cash, $541.90 M is held outside the United States. The filing does not say why a company holding most of its cash abroad still drew on its revolver.
For a reader, IDEX is a company built by buying other businesses and paying for them with debt. Lenders appear to have room: the covenant ratios sit far from their limits, and only $0.40 M of the debt is due within a year. Equity barely moved over the first nine months, because buybacks and dividends took the earnings that came in. What settles the question is whether the $4.50 B of acquired value still matches the prices IDEX paid. If those businesses were valued again tomorrow, would the price still hold up?