ICS sales jumped 57%, but it kept only 2.2 cents a dollar
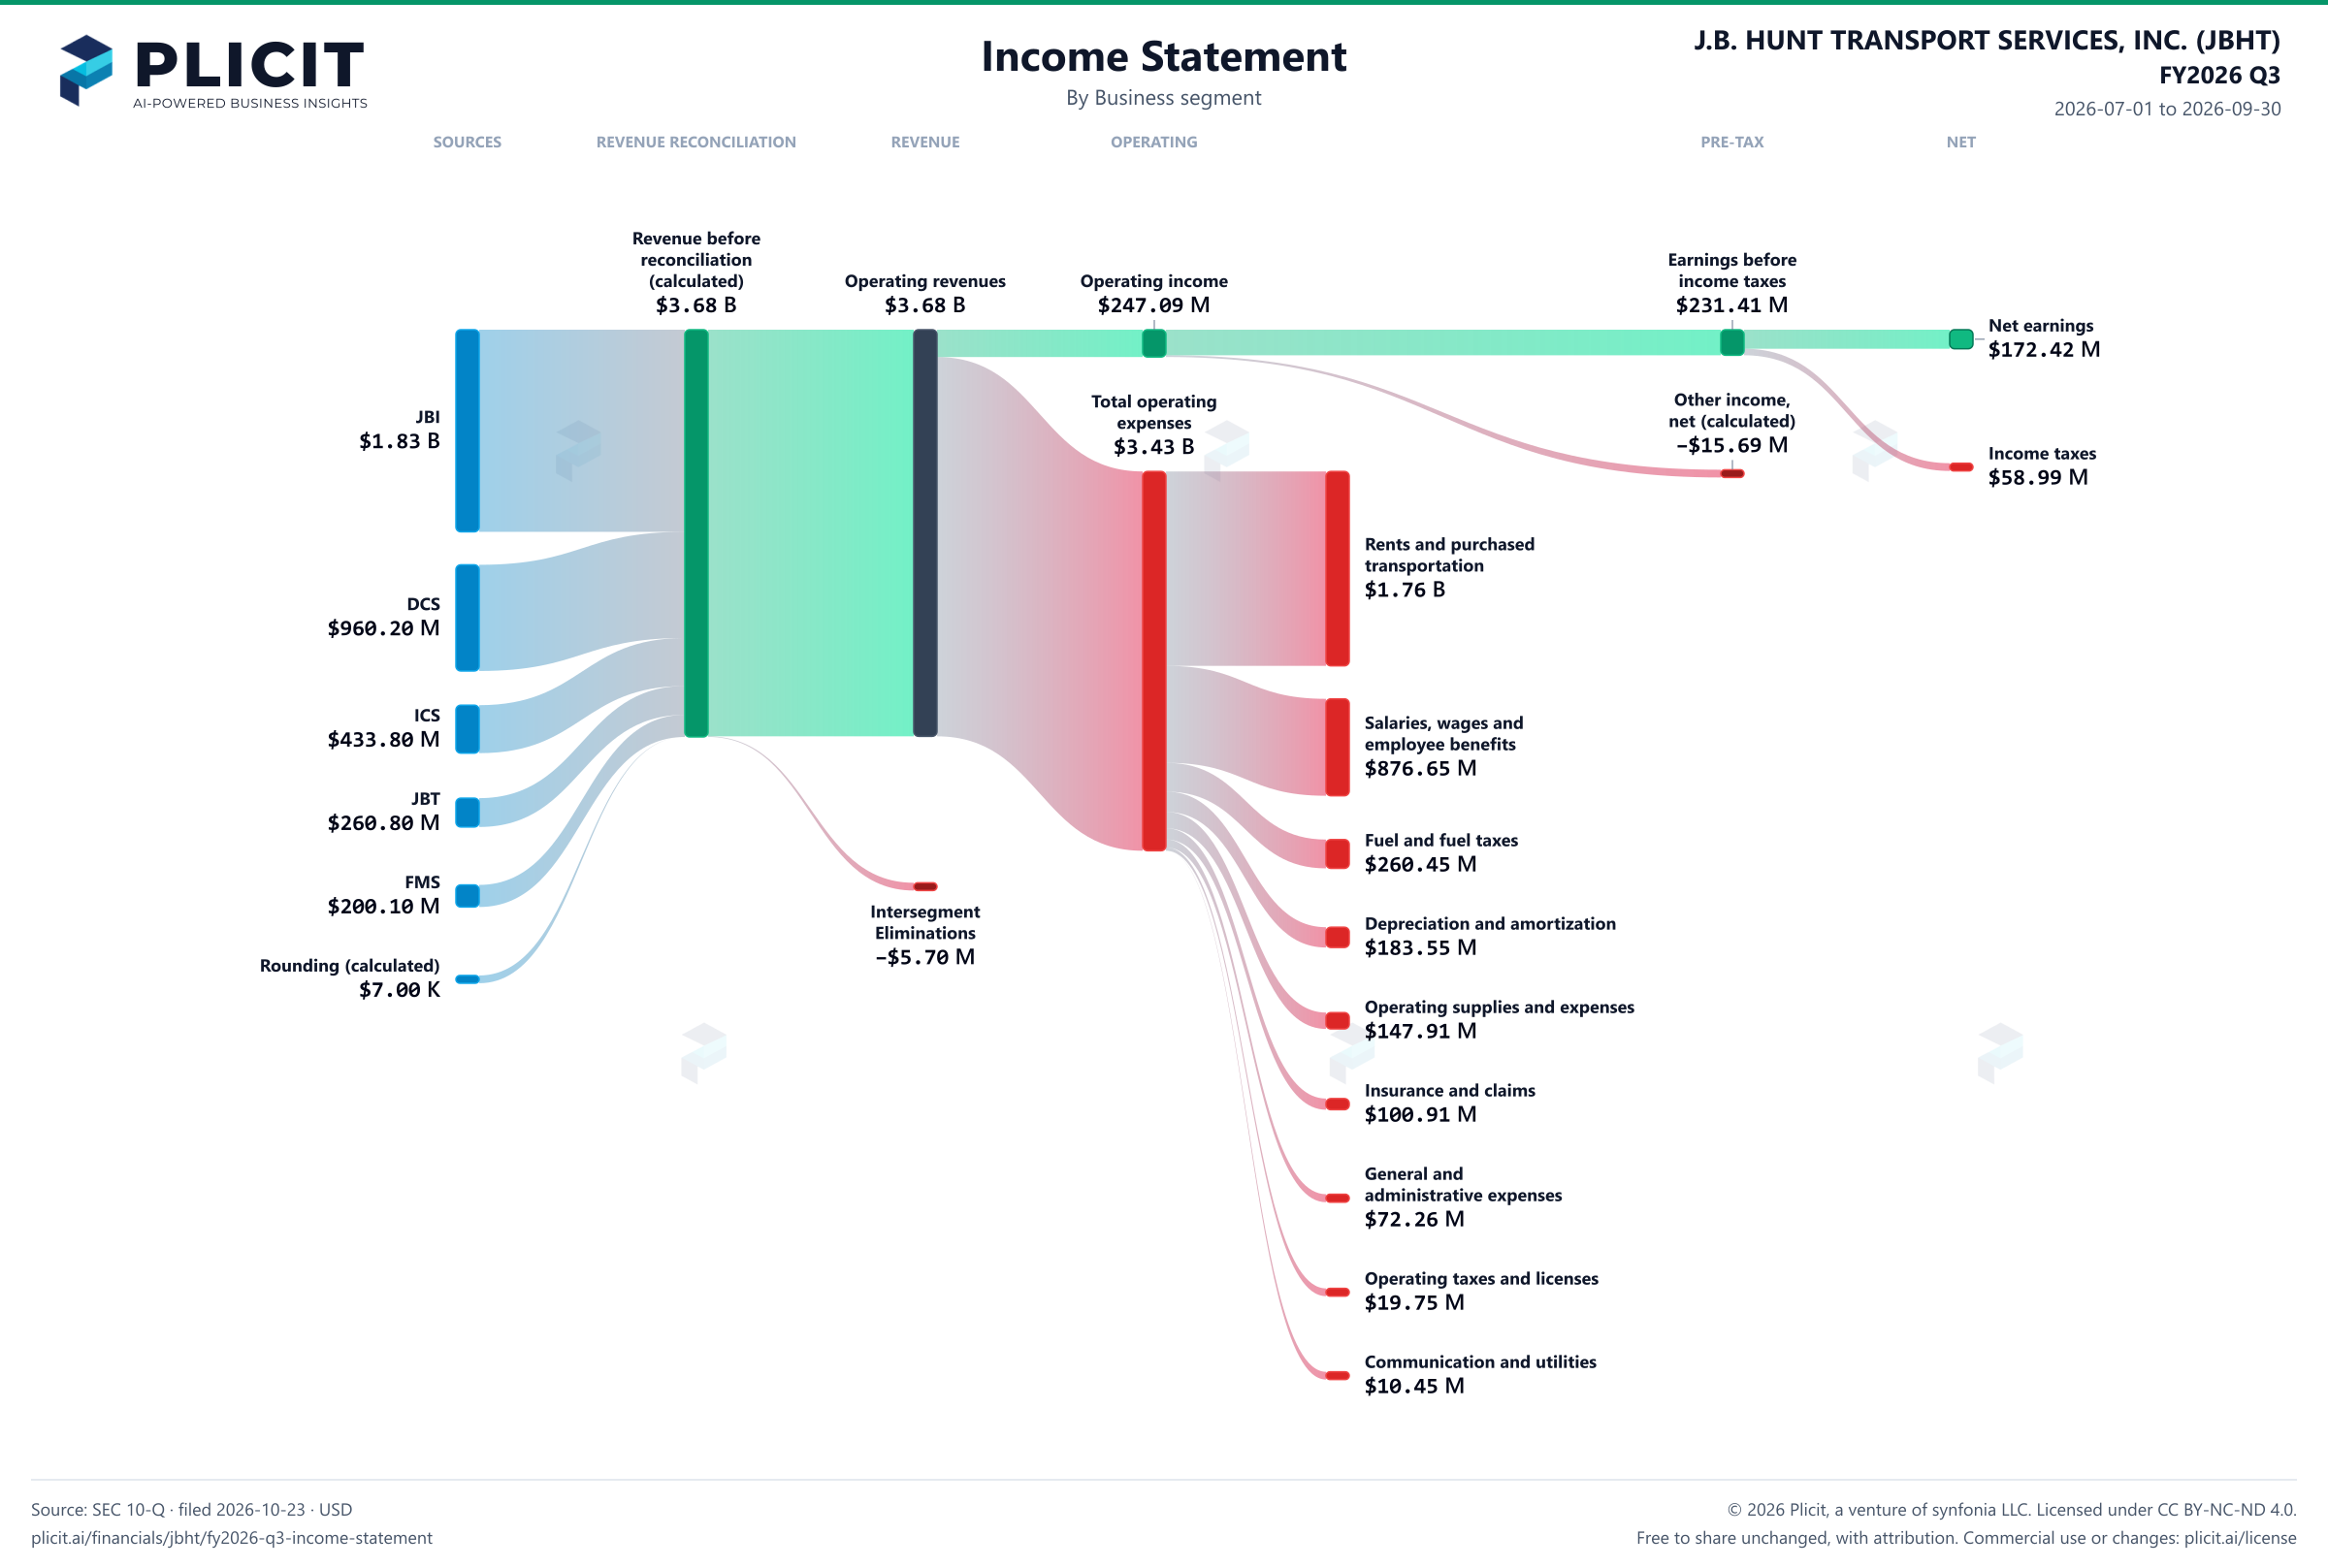
The fastest-growing unit keeps only a sliver of its sales. ICS revenue rose 57% this quarter, to $433.8 M, yet its operating income was $9.6 M, about 2.2 cents on each dollar. The company's own explanation is purchased transportation: gross profit margin fell to 14.3% from 15.0%. Buying capacity from outside carriers is the cost that grows with volume, so the growth number says less about profit than it looks. Sales growth is easy to show. The cents that reach the bottom line are the number to watch.
Meanwhile DCS, the second-largest profit source, saw operating income decrease 22% to $81.7 M from $104.3 M. The filing blames professional driver personnel expense, group medical claims and insurance premiums. Its revenue still rose 11% to $960 million, and customer retention is about 96%, so the squeeze is in costs, not in lost customers. JBI, the biggest unit, kept rising: its operating income went to $147.5 M from $125.0 M. Those two segments explain most of the profit story, and the smaller units barely register beside them.
What does it mean for a reader? The biggest unit also holds the most assets, $3.43 B, so the company's capital follows its strongest earner. ICS's own numbers show the trade: volumes rose 22% and revenue per load 29%, on higher contract and spot rates. The question that settles the margin story is whether ICS keeps its volume growth while its gross profit margin, already down to 14.3%, keeps falling. Will ICS margins recover, or does growth come at a price the next quarter will reveal?