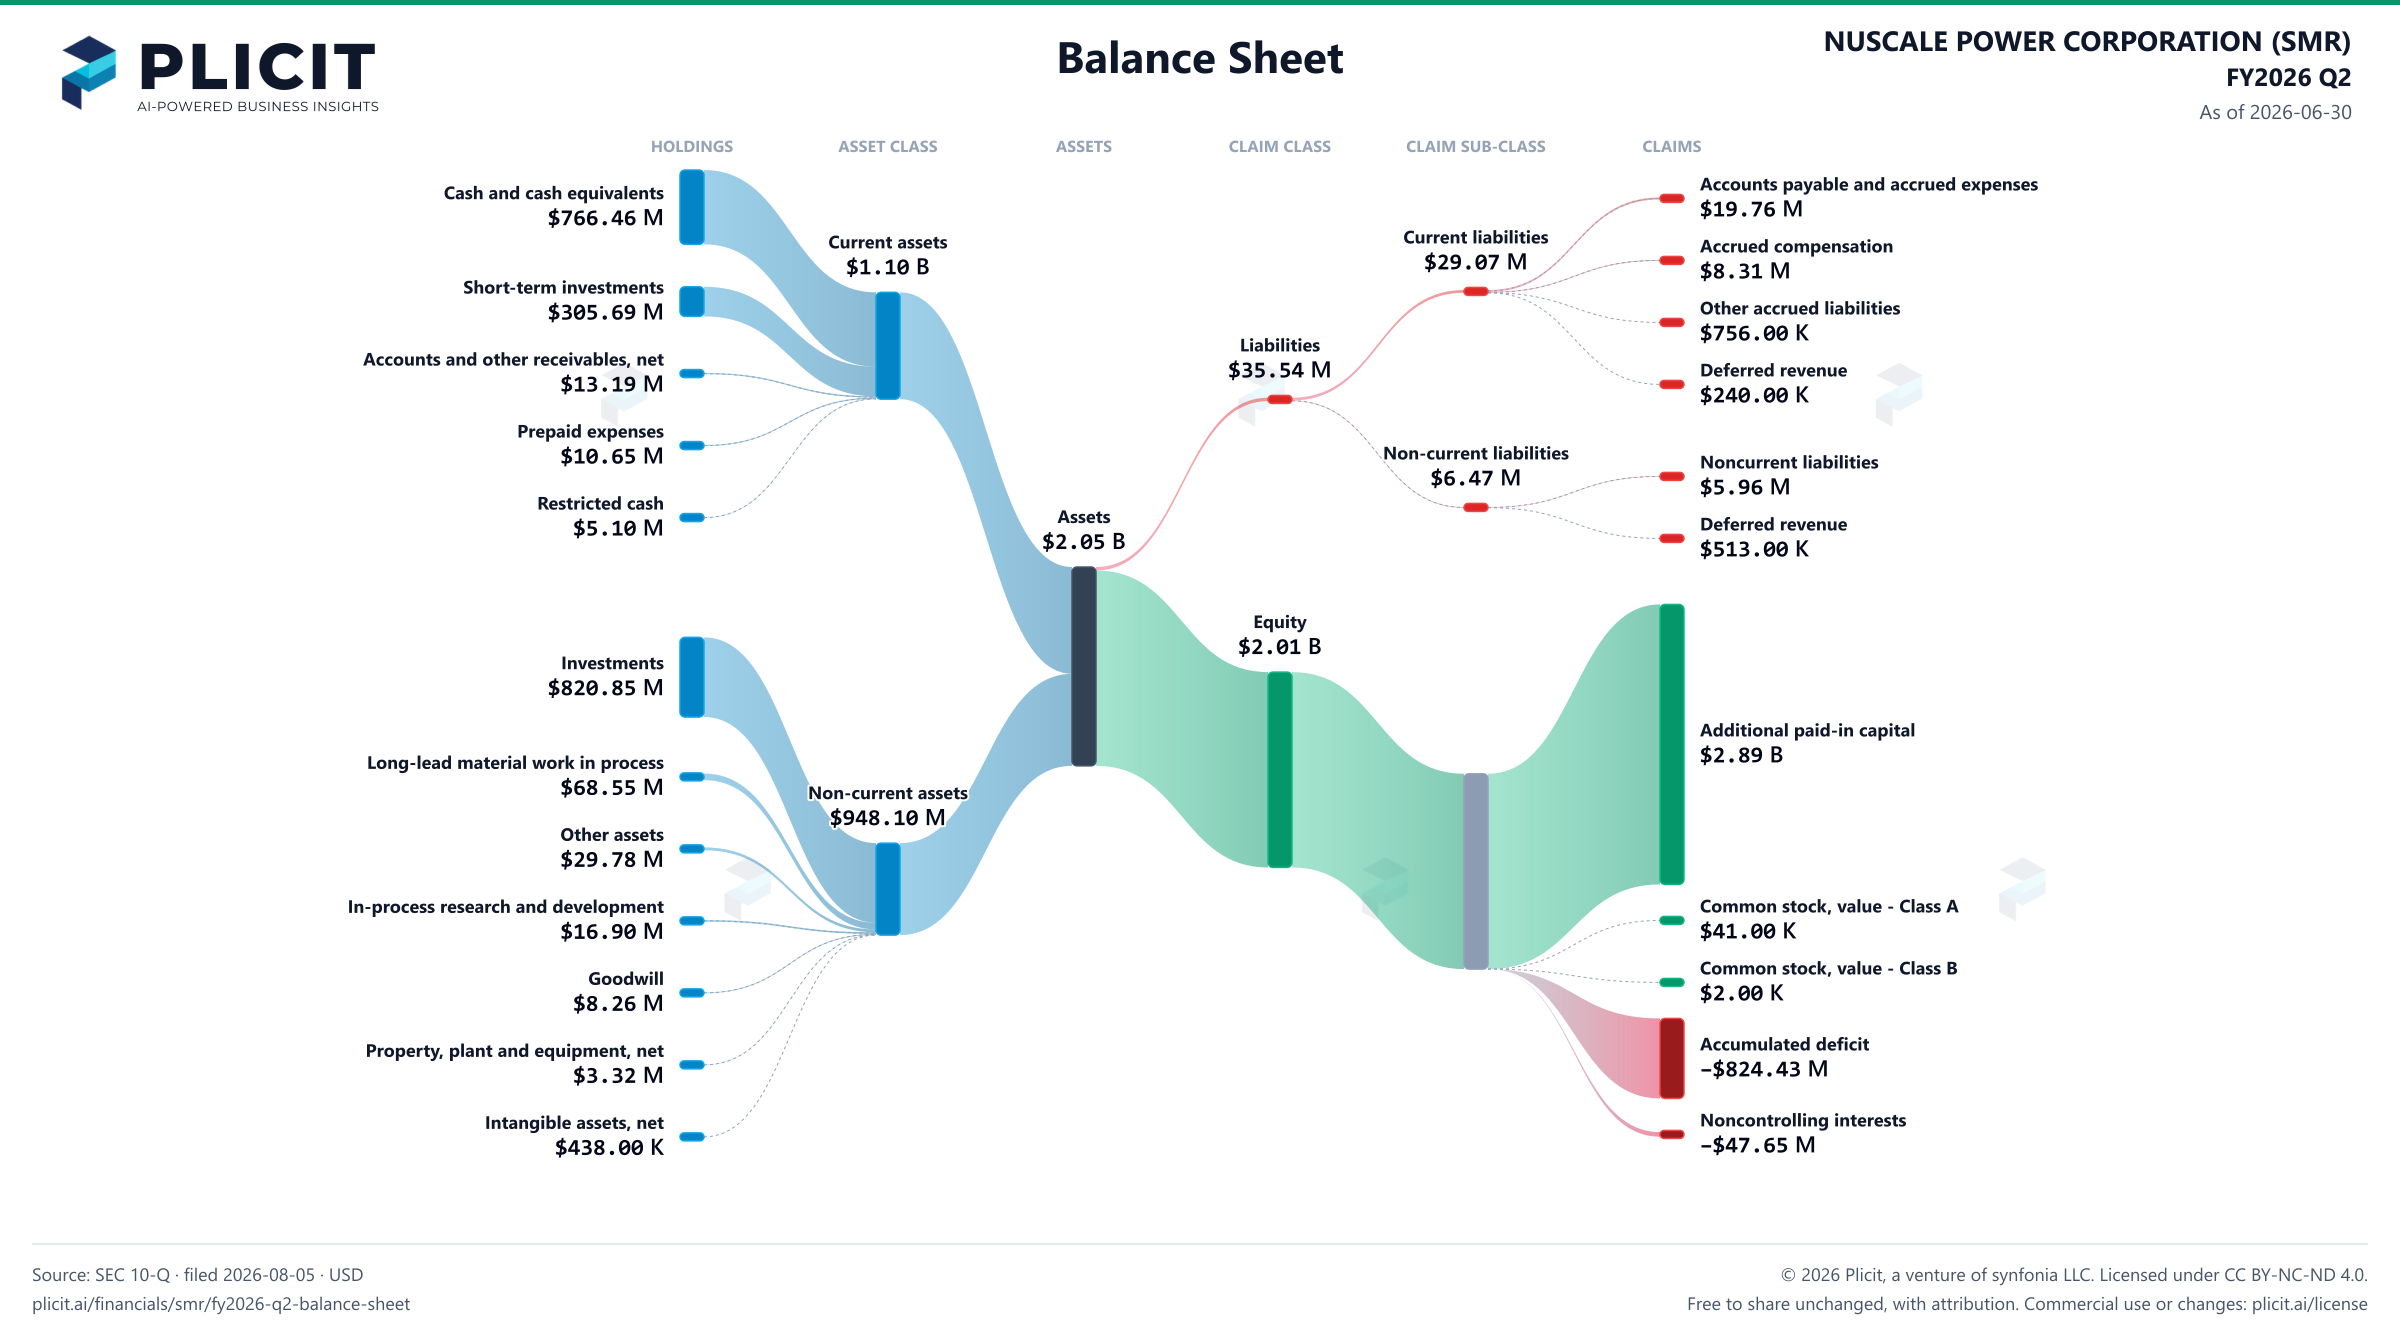
NuScale's $2.05 B fortress was built by shareholders, not customers
NuScale sits on $766.46 M of cash, $305.7 million of short-term investments and $820.8 million of longer investments, with no debt. That pile did not come from selling reactors. Sales this quarter were $75.00 K, down from $8.05 M a year earlier. The money came from shareholders: in the six months to June 30, 2026, the company sold 89,727,165 new shares for net proceeds of $984.5 million before completing its stock sale program in June 2026. Liabilities were only $35.54 M. This is a balance sheet funded by hope, and the hope is on loan from investors.
Why does a company with $75.00 K of quarterly sales hold $1.89 B of cash and investments? Part of the answer is ENTRA1, its exclusive commercialization partner. When ENTRA1 signed a non-binding agreement relating to 72 NPMs in 2025, NuScale owed it the first Milestone Contribution, and it paid $259.9 million of that in 2026. That was only the first tranche, 15% of the total. The second, 35%, comes due when ENTRA1 signs a binding power purchase agreement; the third, 50%, with an equipment order. None of it is accrued at June 30, 2026.
For shareholders, the cash buys time, not proof. Management says it has enough cash, investments and market access "to satisfy our cash requirements for the next 12 months and beyond." But the partner holding the customer relationship has "sole and full discretion to select, contract with, or purchase from NuScale." Watch the talks between ENTRA1 and TVA, because a binding power purchase agreement there would trigger the 35% tranche and could open the door to real orders. When that bill arrives, will a reactor sale come attached?