Credit cards, not seats, are Alaska Air's fastest-growing sales line
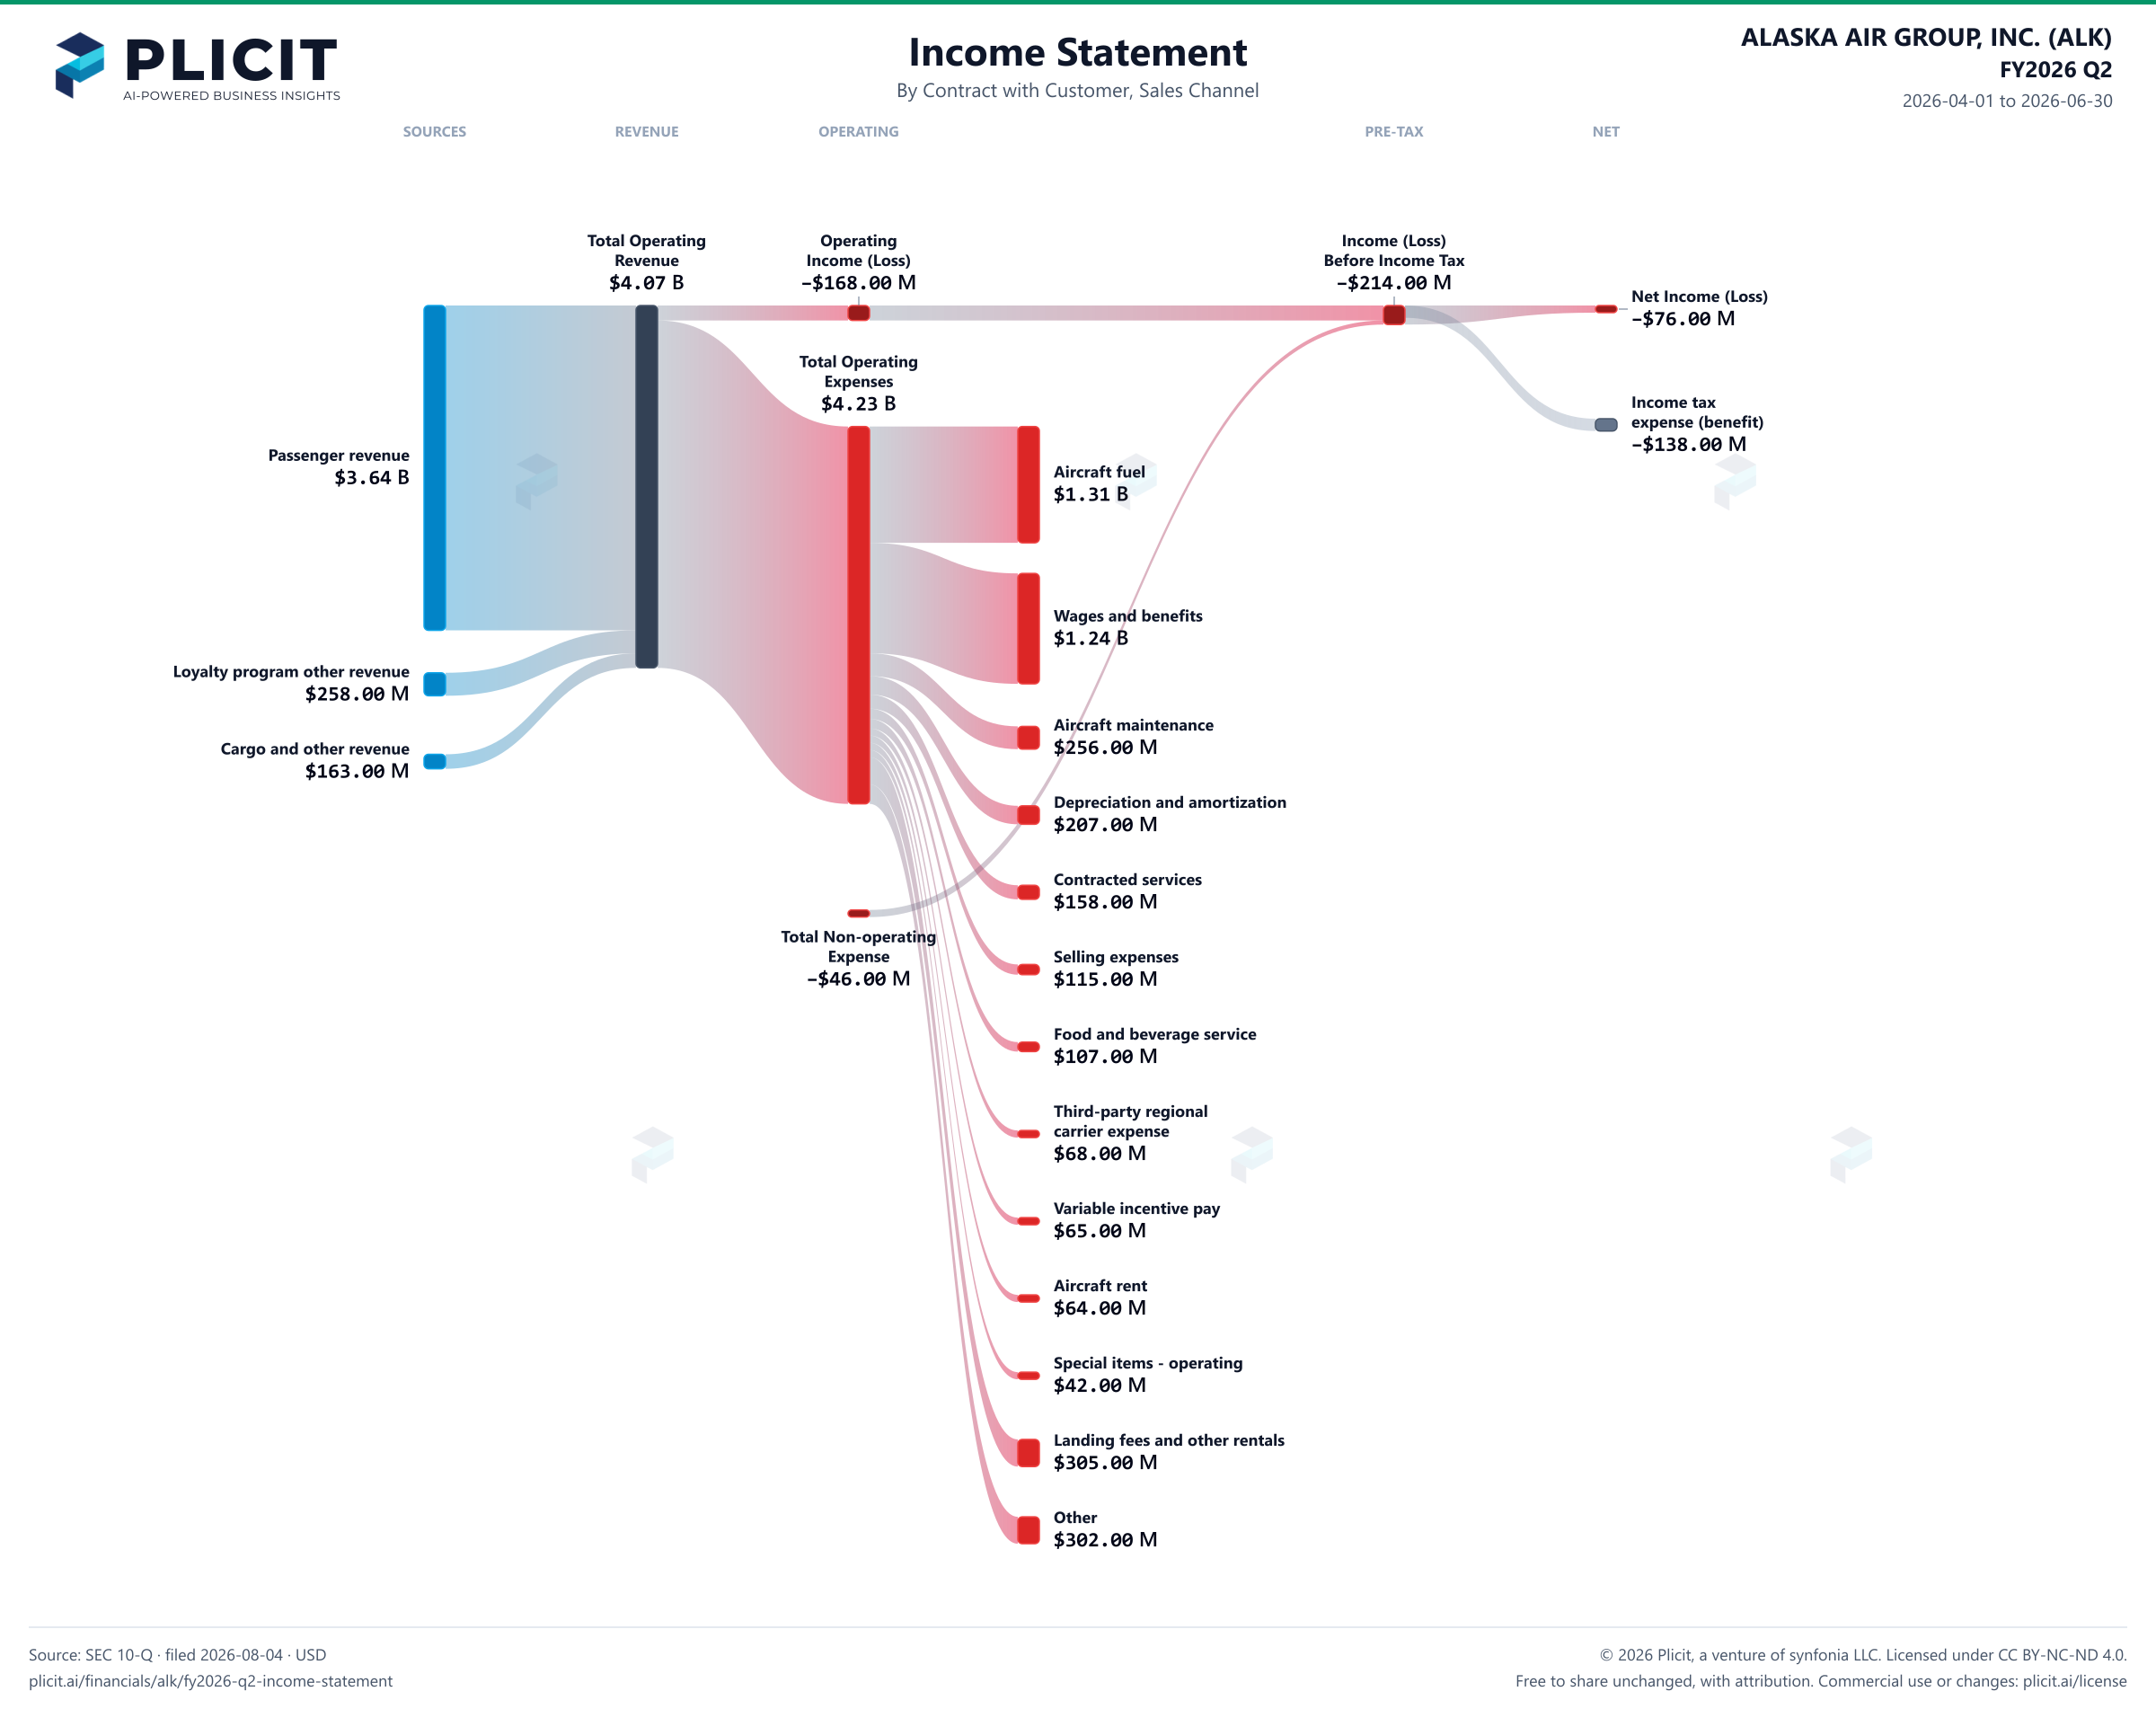
Alaska Air's sales grew 9.7% this quarter, and still the airline lost money. The growth was real but unevenly spread. Passenger revenue, $3.64 B and 90% of sales, grew 8.6%. The fastest line was Loyalty program other revenue, up 23% to $258.00 M. Management ties it to "the launch of the Summit Visa Infinite premium credit card and the Atmos Rewards program in August 2025", which drove commissions from bank card partners. Cargo and other revenue added $24 million, or 17%. Together the lines added $361 million. Fuel alone took $605 million more.
Why does the loyalty line matter more than its size suggests? Its share of revenue rose to 6.3% from 5.7% a year earlier, and it earns commissions without burning jet fuel. Management also cites "the extension and expansion of Alaska's co-branded credit card agreement with Bank of America". Passenger revenue tells a softer story. Management credits higher yields, but concedes "softer demand in certain leisure markets, including Hawai'i". Passenger growth did speed up, to 8.6% this quarter from 4.0% the quarter before. The gain came from price, not volume.
For investors, the mix is a partial hedge. Every point of share the loyalty card wins is revenue that fuel prices do not touch directly, while fares must keep rising just to stand still against fuel. The filing does not say what the $258.00 M of loyalty revenue costs to earn, so its margin is unknown. Watch whether loyalty keeps growing near 23% and whether passenger growth holds near 8.6% if leisure demand stays soft. Can a credit card program that brings in 6.3% of revenue grow fast enough to carry an airline through a fuel shock?