Acuity's profit jumped 34%, but tariff refunds and QSC did the lifting
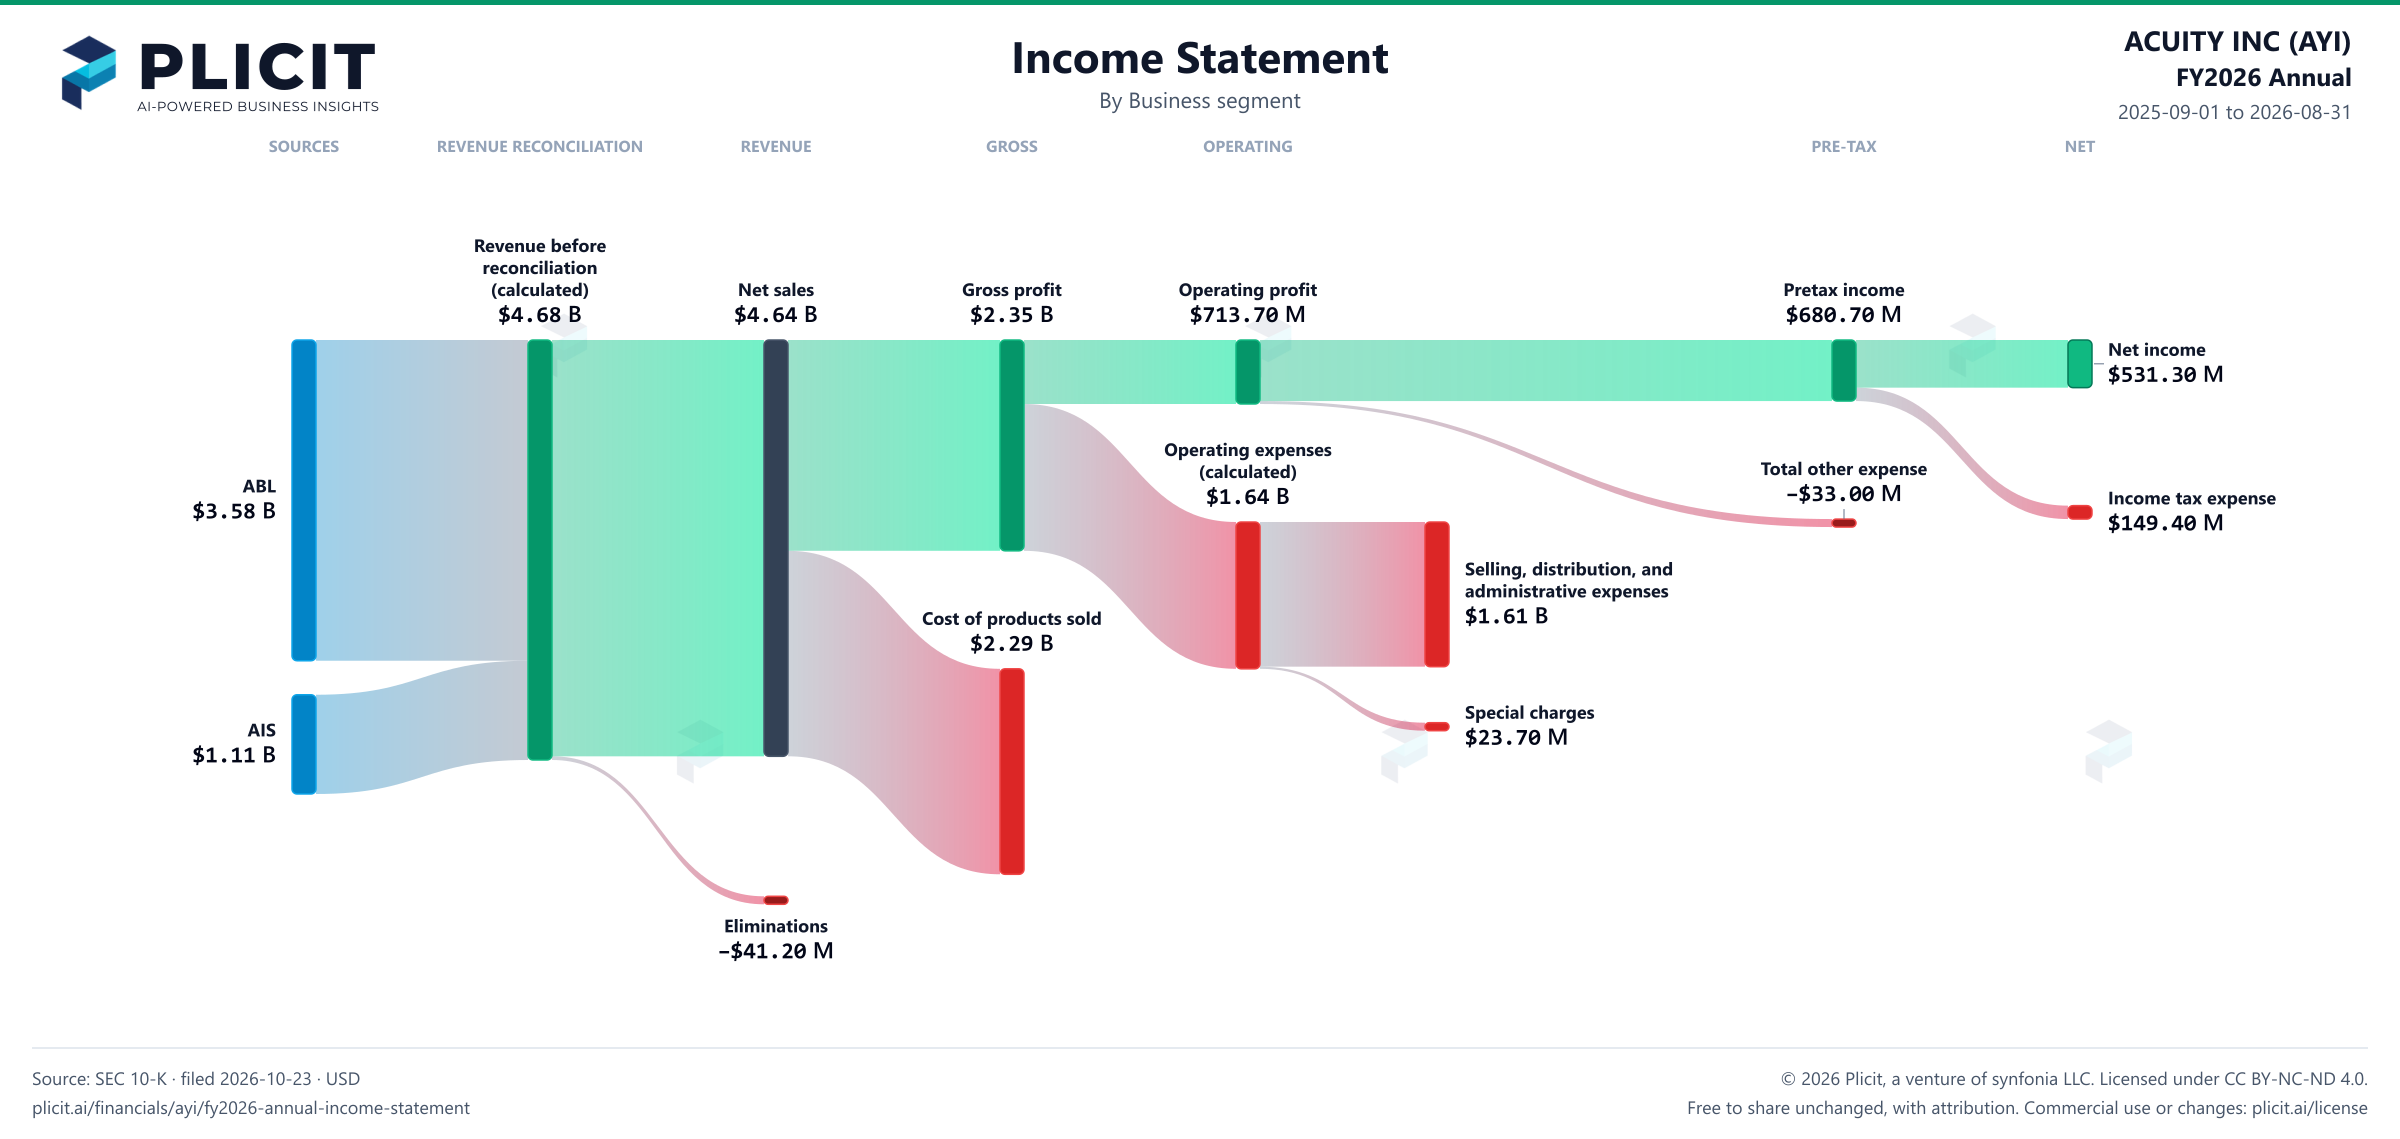
Acuity's net income jumped 34% to $531.30 M in the year to August 31, 2026, while sales rose just 7%. Operating profit climbed $149.80 M, and management credits "higher gross profit". But $51.30 M of that gross profit was refunds from U.S. Customs for tariffs Acuity had already paid. That is about a third of the operating profit gain, and it is not money a lighting maker earns from customers. Gross margin rose to 50.6% from 47.8%, a jump the refunds helped buy. How much of this year is repeatable?
Why did profit outrun sales so far? AIS, the building-technology unit that bought QSC for $1.2 billion on January 1, 2025, grew sales 45%. It supplied $110.40 M of the $143.30 M rise in operating profit across both businesses. ABL, the lighting arm that still makes 77% of sales, shrank 1.0%, which management puts down to lower sales in its direct sales network and OEM channel. Even ABL's margin of 17.4% leaned on $38.2 million of the same tariff refunds. Below the operating line, a $30.9 million pension settlement charge that hit 2025 did not recur.
For investors, the open question is what Acuity earns once the refunds stop and QSC no longer flatters the comparison. Diluted earnings per share rose 36.1% to $17.05, helped by fewer shares as well as higher profit. Special charges of $23.70 M, aimed at productivity and labor cost reductions, show management trimming a lighting business that is not growing. Watch ABL's sales and how much of the 50.6% gross margin survives without customs refunds. If the refunds and the QSC lift fade, can AIS grow fast enough to carry a lighting arm that is shrinking?