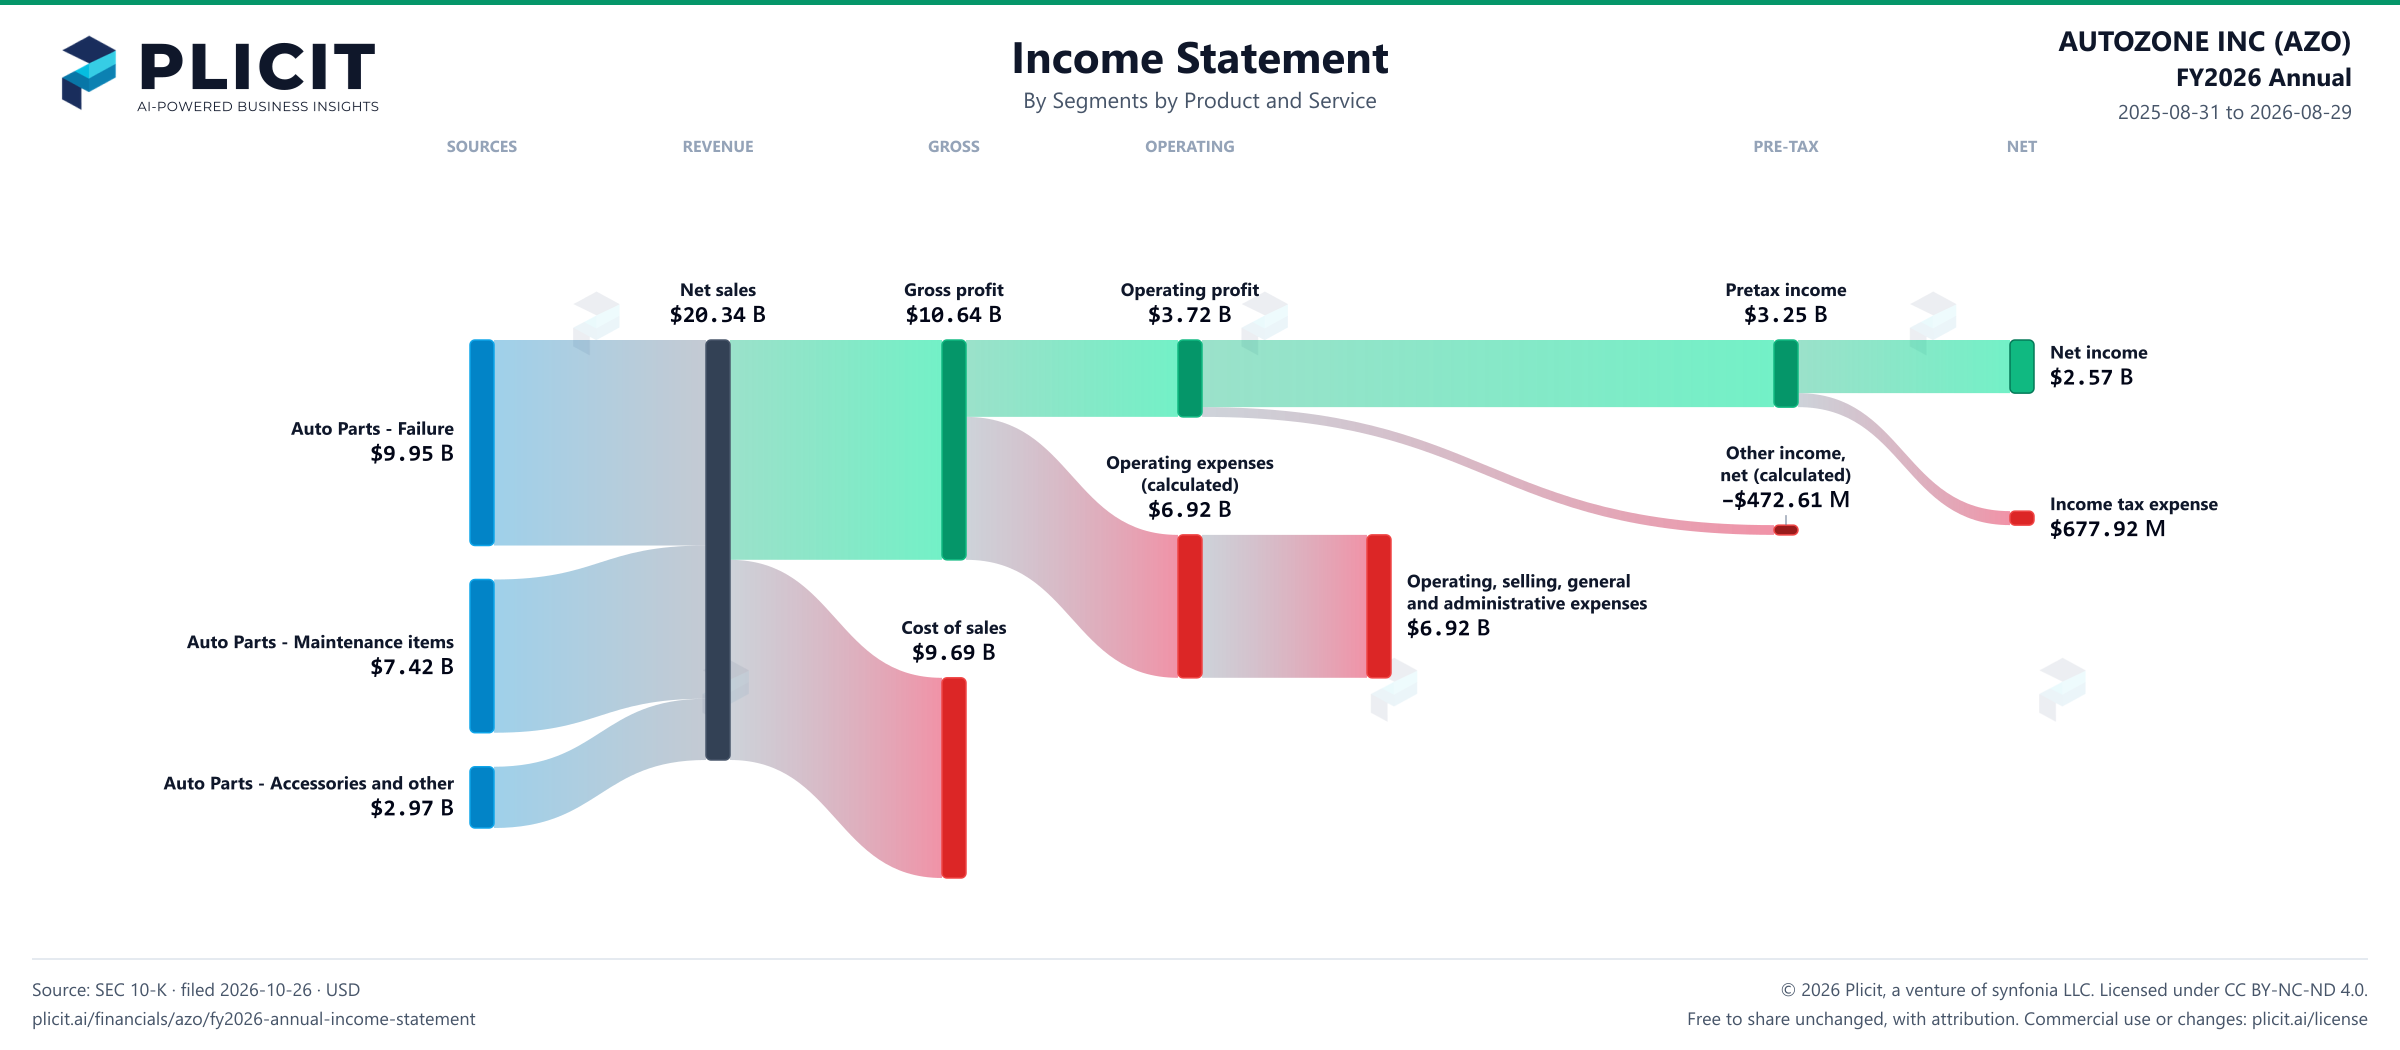
AutoZone's sales rose 7%, but its operating profit grew only 3%
Sales rose 7%, but operating profit rose only 3%. Revenue reached $20.34 B this year, and operating profit reached $3.72 B, against $3.61 B a year earlier. Every extra dollar of sales kept less of the gain, because cost of sales and overhead grew faster than the top line. Cost of sales took 47.66% of sales, and selling and overhead costs took 34.03%. Its tax rate went up too, which kept net income growth to 3%. Did costs grow faster than sales, and what is the cost of growing?
Growth came from the top-selling line: Auto Parts - Failure grew 7.1% and supplied 47% of the $1.40 B rise in revenue. Interest and other items below operating profit took $472.61 M, and the tax rate rose to 20.85%, which trimmed the profit that the growth earned. Failure is the line to test first, because it carries the growth and the cost of selling it. If Auto Parts - Failure carries the growth, what is it costing in inventory and cash?
Read this as a test of management's cost story, not as a verdict on the company. For investors the signal is the gap between sales growth and profit growth, not the profit figure by itself, because a rising profit figure can hide thinner margins and a heavier cost base. That gap is 4 points wide this year, with sales up 7% and operating profit up only 3%. Will AutoZone's gross margin keep sliding while Auto Parts - Failure carries the growth?