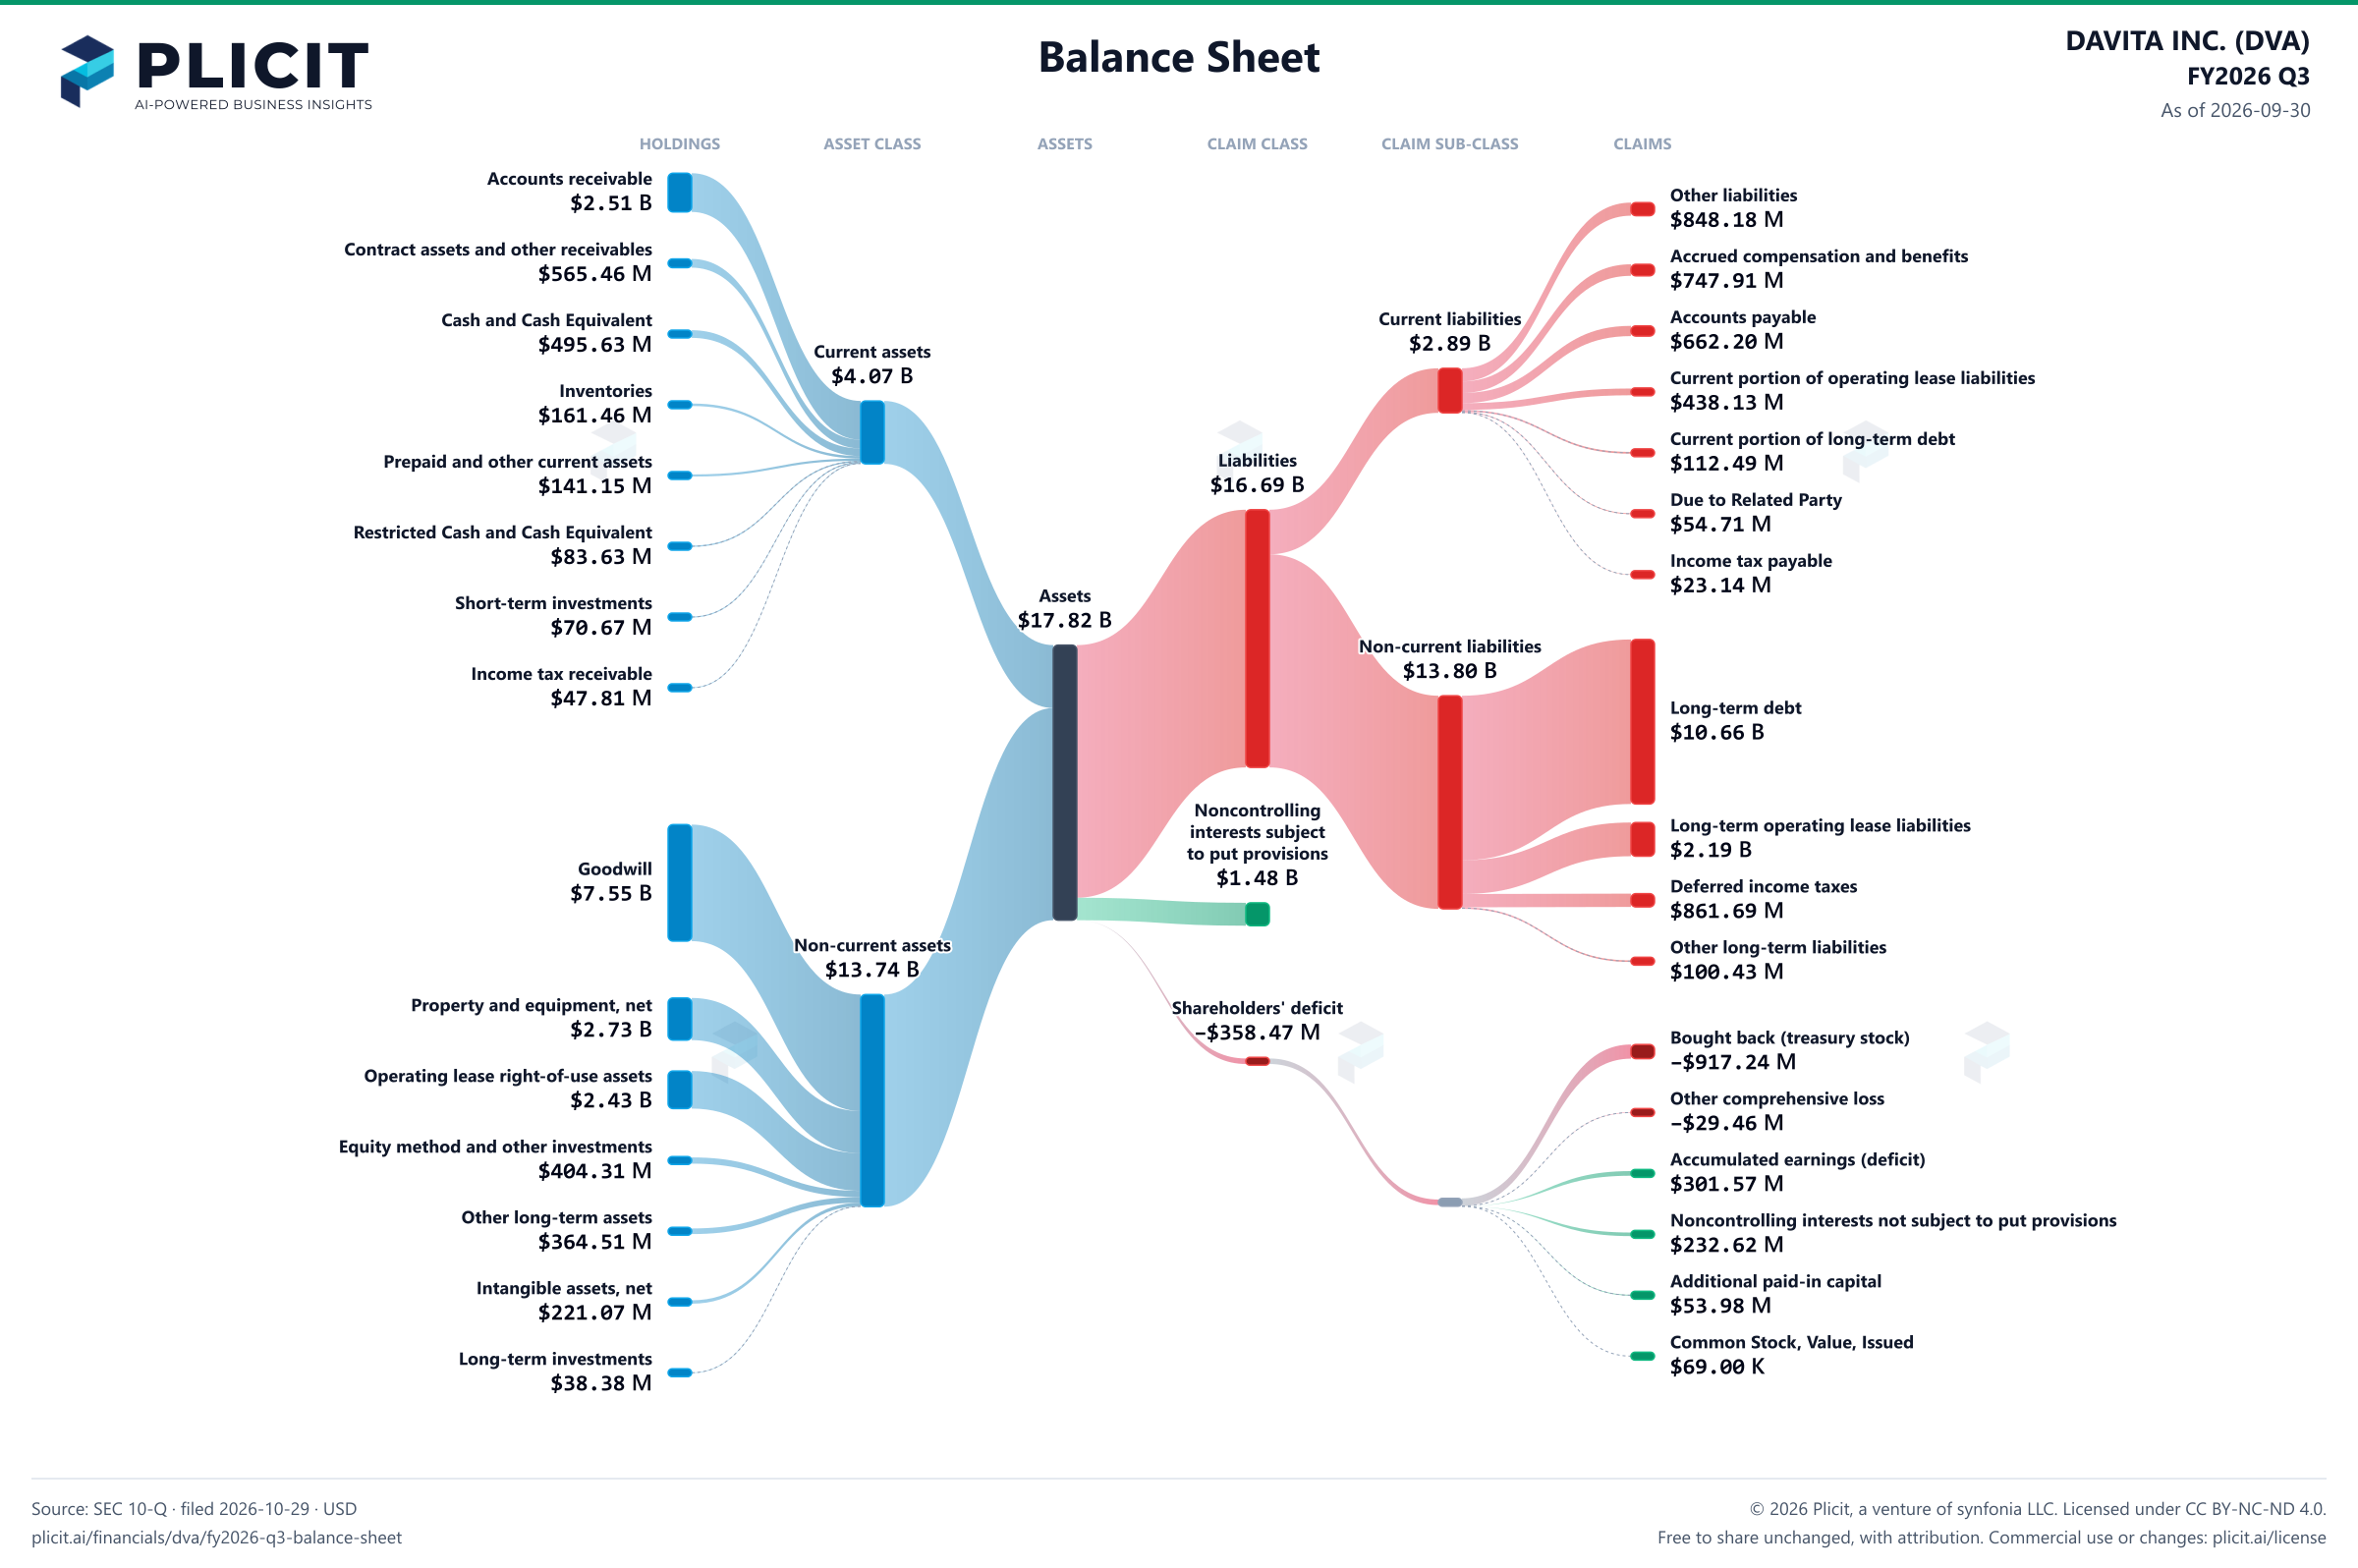
DaVita owes $10.77 B and its shareholders' equity is below zero
DaVita carries $10.77 B of debt against just $495.63 M of cash, and its total equity sits at -$358.47 M. That deficit is not because debts exceed assets: assets of $17.82 B still top liabilities of $16.69 B. What sinks equity is $1.48 B of stakes in its subsidiaries that partners can, in some circumstances, require DaVita to buy back, booked outside equity. Meanwhile, $7.55 B of goodwill, 42% of everything it owns, props up the asset side. Strip out goodwill and other intangibles and DaVita's own shareholders' deficit deepens to -$8.36 B.
Why should a goodwill line matter? Because it is where write-downs land. This quarter DaVita booked $62.18 M of goodwill and other asset impairments in China, $57.10 M of it goodwill. Management blames adverse reimbursement rate changes in non-renal hospital services. Partners in the China unit absorbed $31.60 M of the goodwill charge. The note says China remains at risk of further impairment. The real weight sits in U.S. dialysis, which carries 87% of all goodwill. Any lasting hit to that business would land on a balance sheet with no equity cushion.
For lenders, the calendar matters more than the deficit. Of $10.83 B of scheduled repayments, only $144.41 M comes due in the near term, while $4.57 B lands in 2030 alone. Current assets cover bills due within a year 1.41 times, so near-term liquidity is not the pinch. The pinch is refinancing: that 2030 wall is about 9 times today's cash, and every dollar spent on buybacks is a dollar not set aside for it. Can DaVita roll over that wall on good terms while it keeps shrinking its share count?