DaVita's per-share earnings leapt 67% while its operating profit slipped
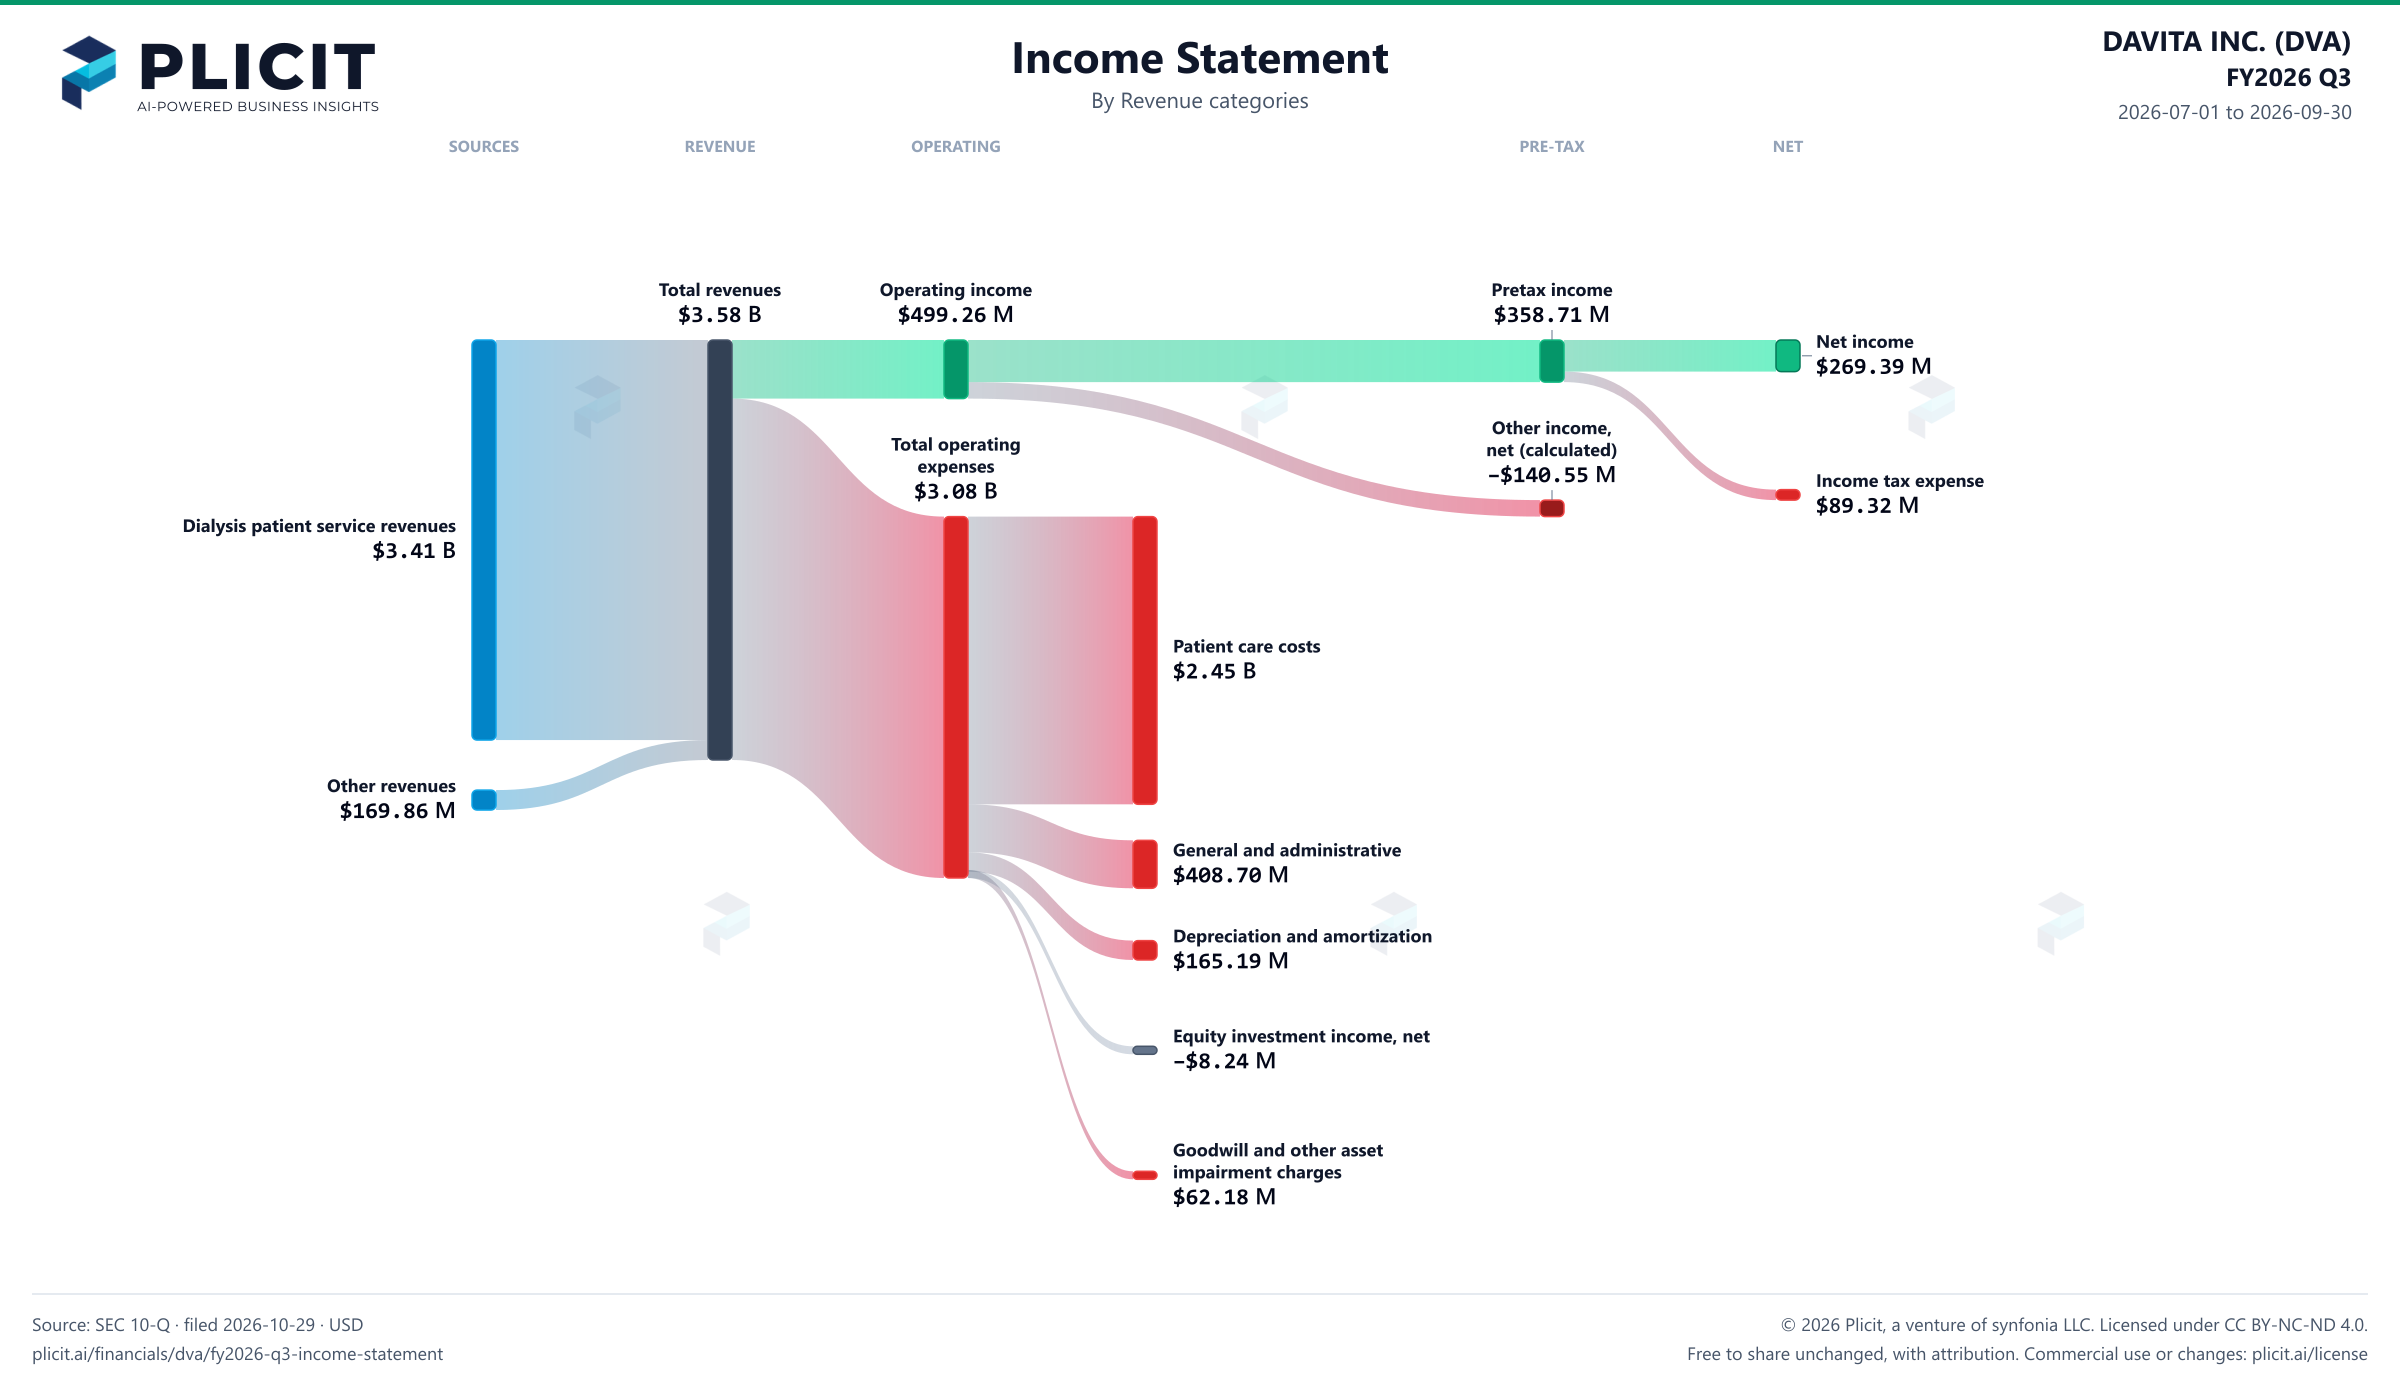
DaVita wrote $62.18 M off its business in China this quarter, and that charge decides the headline. Operating income slipped 1.3% to $499.26 M even as sales grew 4.6% to $3.58 B. Add the charge back and operating income would have been $561.43 M, 11% above a year earlier. Yet diluted earnings per share leapt 67%, to $3.40, from $2.04. How does a company post a lower operating profit and a far richer profit per share in the same quarter? The answer runs through its partners and its share count.
Start with partners. Outside owners of DaVita's subsidiaries took $46.46 M of profit, down from $89.92 M a year earlier. Management says $34 million of the China impairments fell on those minority holders. Net income attributable to DaVita rose 48% to $222.93 M. Then shares. The diluted share count averaged 11% fewer than a year before, after heavy buybacks, so each remaining share claimed more. Below the operating line, other income was $9.47 M against a $41.26 M loss a year earlier.
For shareholders the quarter's gain is real but narrow: it comes from fewer shares, a smaller partner cut and a turn in other income, not from a stronger core. Operating profit covered interest 3.3 times, against 3.4 times a year earlier. The share of pre-tax profit paid in tax rose to 24.9% from 22.2%. Management ties the rise from the second quarter mainly to a goodwill charge that is not tax-deductible. The filing says China remains at risk of further goodwill impairment. Watch the operating line, not the per-share line. If the China write-down is set aside, is DaVita's dialysis engine still growing, or are buybacks doing the heavy lifting?