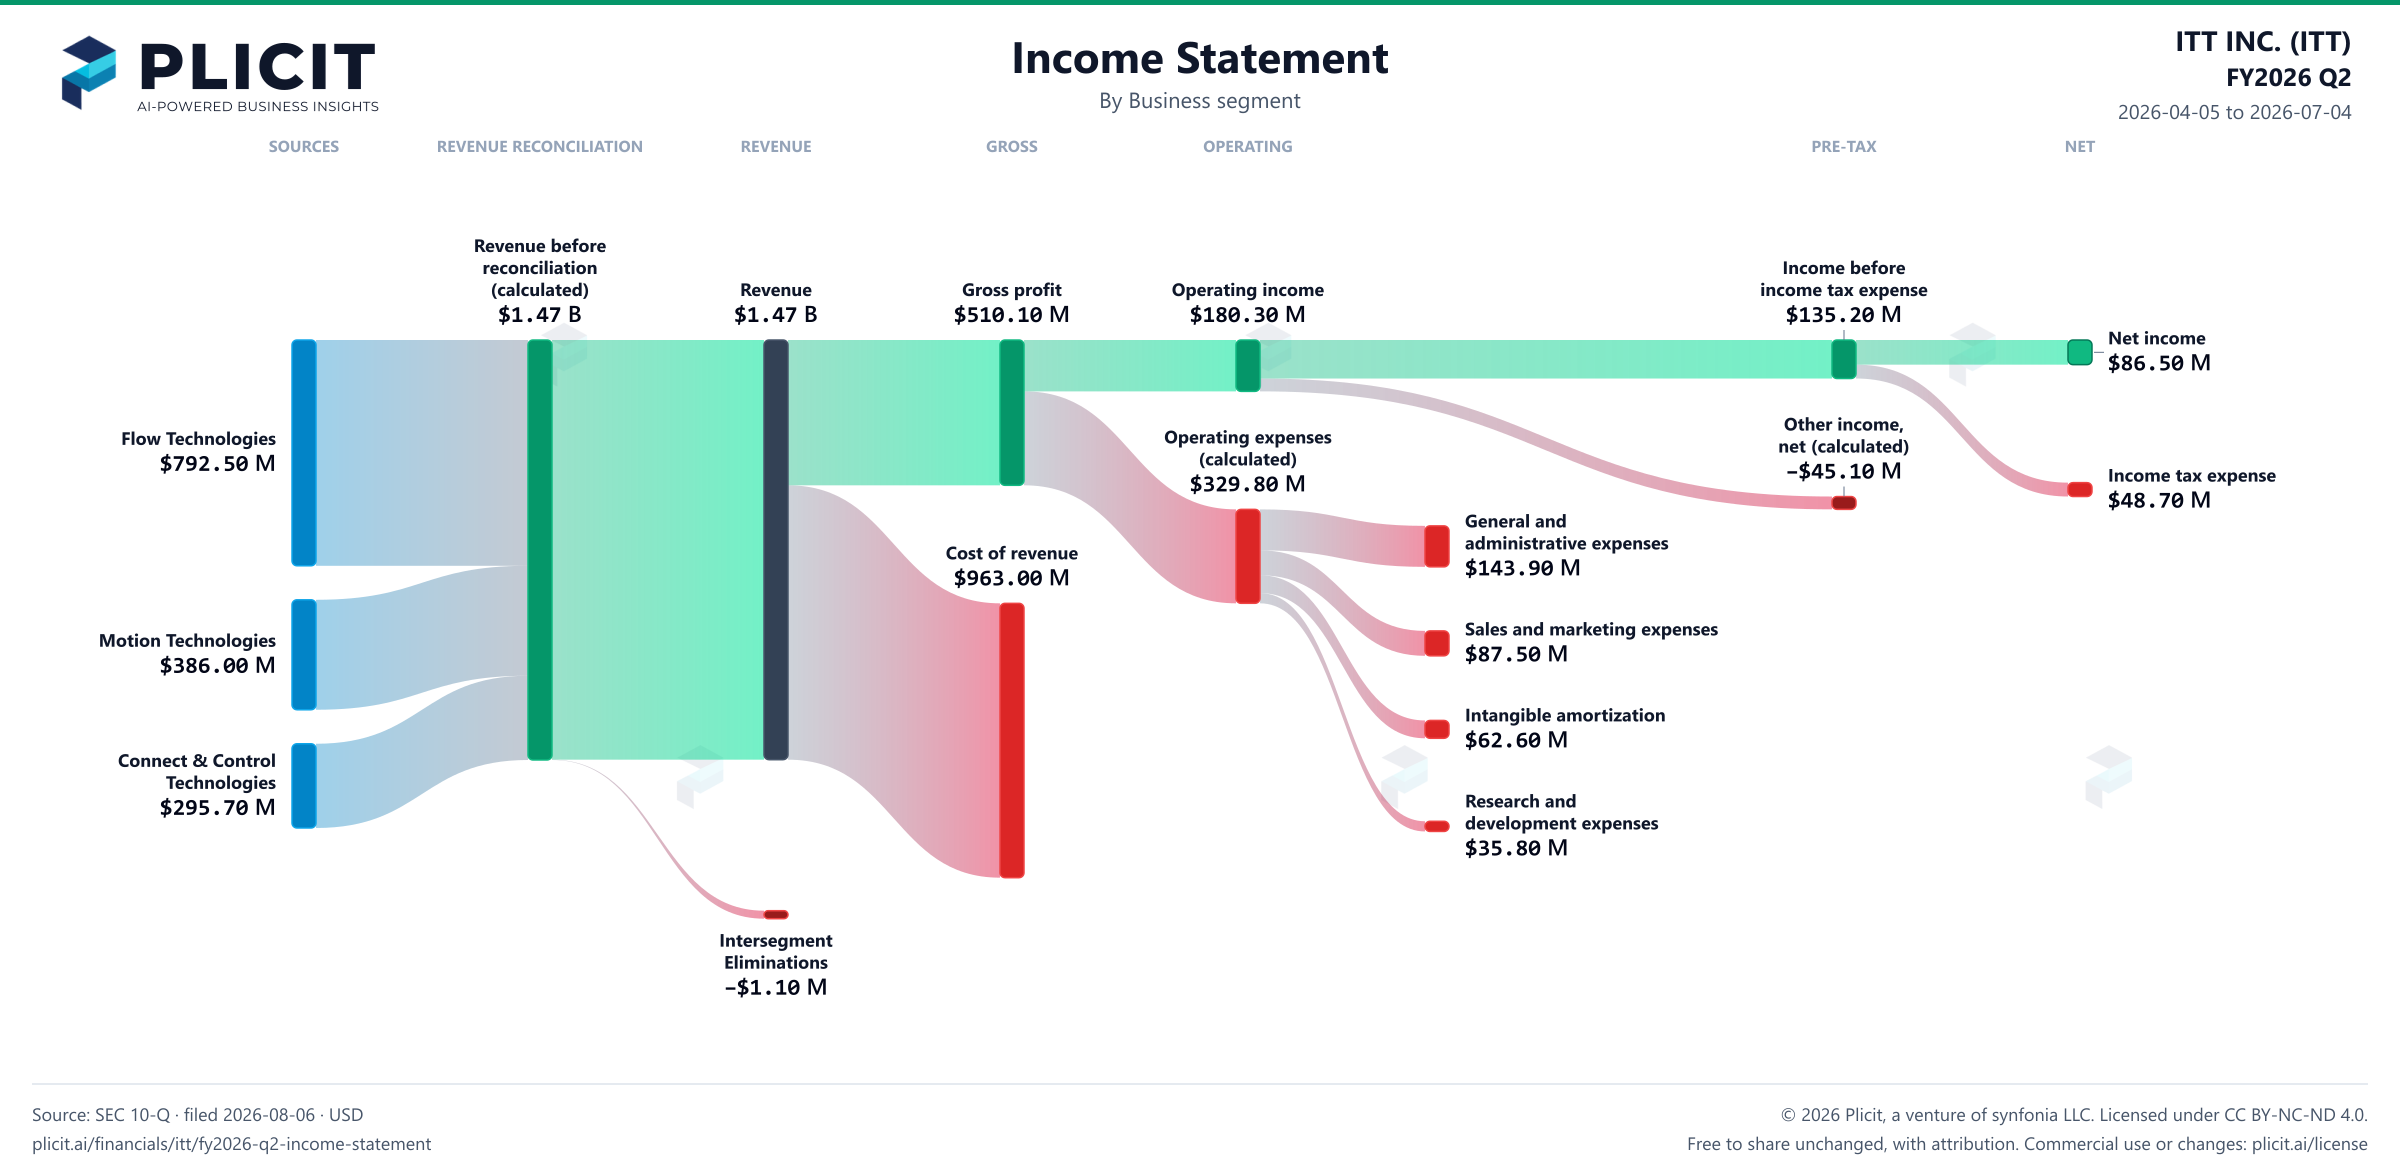
Flow Technologies' sales rose 123%, but its operating margin fell to 7.9%
Flow Technologies' sales rose 123% this quarter, to $792.50 M from $355.90 M. Management says the acquisition supplied most of that jump: $359.60 M of the $436.60 M increase came from acquisition contributions. Organic growth, the part without the acquisition, was 20.7%, yet the segment's operating margin fell to 7.9% from 21.5%. That is the trade the acquisition made: more sales, thinner margins. Read the segment table as a record of what was bought, not what was built.
Motion Technologies earns the most profit, $82.10 M of operating income, or 40% of the segments' total, on 26% of sales. Flow Technologies holds $8,013.80 M of assets, against $1,263.50 M at Motion Technologies. Its operating income of $62.90 M came to 0.8% of those assets, while Motion Technologies earned 6.5% of its $1,263.50 M. Most of those assets came with the acquisition, which is why the segment carries 78% of the goodwill.
The lesson for a reader is that size and profit point in different directions here. A segment can look bigger and still earn less, and this one does. Corporate costs grew too: Corporate and Other took $25.50 M out of operating income this quarter, up 44.9% from $17.60 M a year earlier. Will Flow Technologies' margin climb back toward its old 21.5% once SPX FLOW is integrated, or was the bought growth never going to earn it?