Jabil's restructuring charges have run three years straight
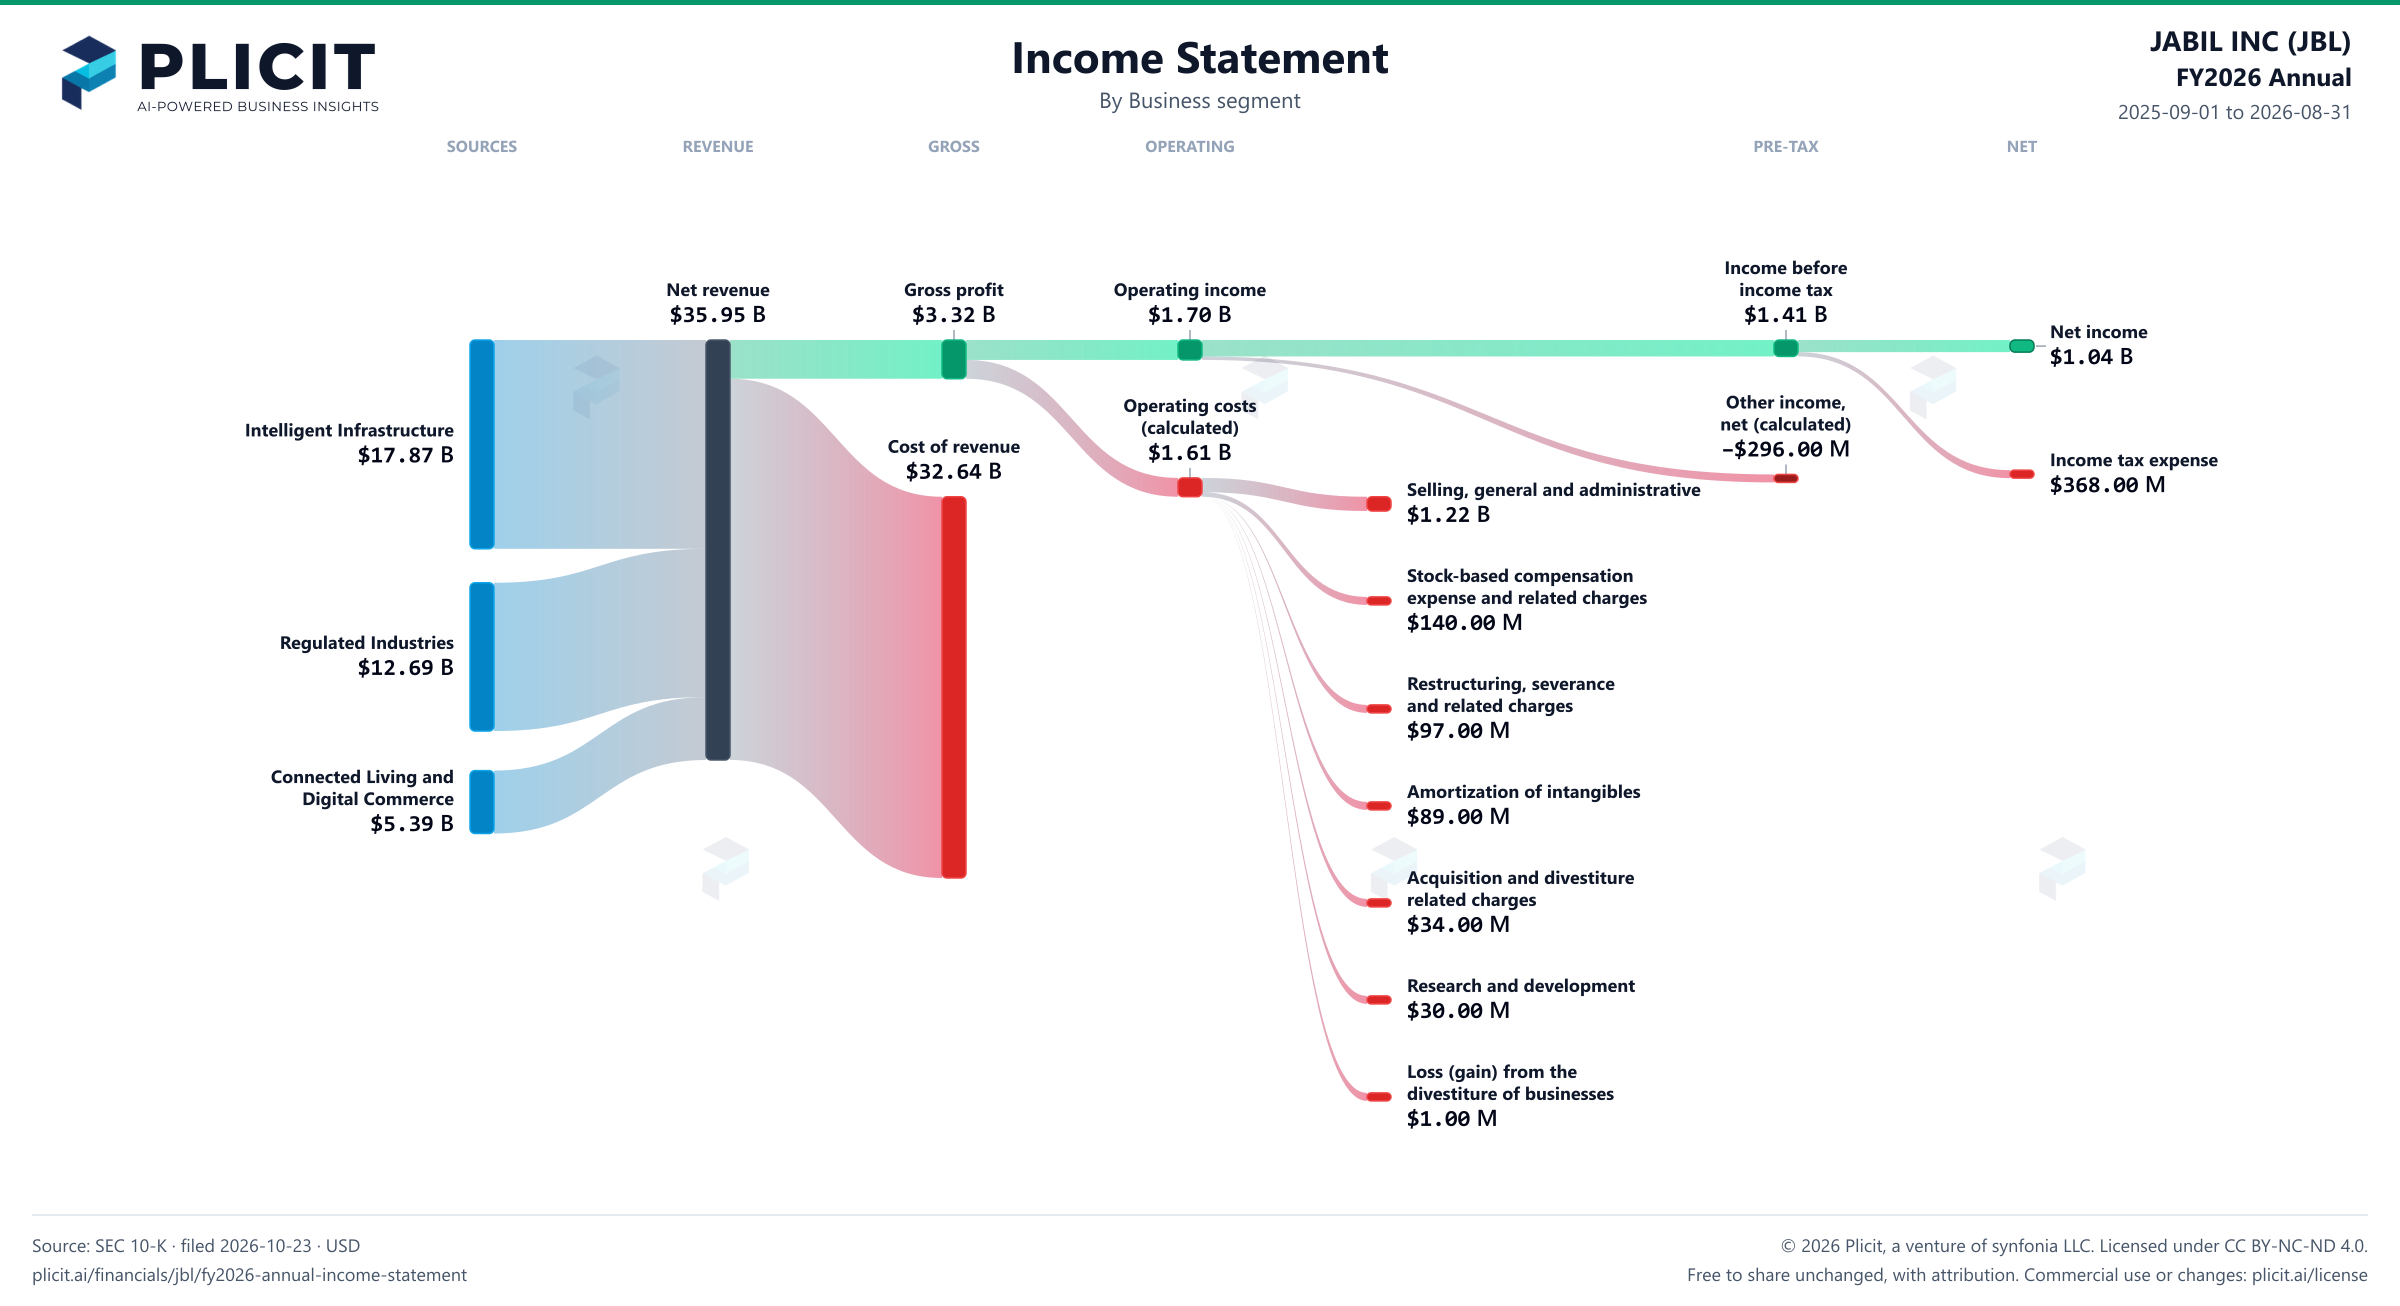
Jabil has booked restructuring charges three years straight. They were $296.00 M two years ago, $181.00 M last year and $97.00 M this year. Each one is smaller than the last. The 2025 plan totaled about $200.00 M and is now substantially complete. Regulated Industries took $57.00 M of this year's charges, more than any other business. The note says all of it except asset write-offs is cash. Even so, profit rose 58%. A cost that keeps coming back is not a one-time item.
Why does profit grow faster than sales? Operating profit rose to $1.70 B from $1.18 B, a gain of 44%. Items below it, led by net interest of $181.00 M, took $296.00 M before tax, against $290.00 M a year earlier. Net income rose faster still, to $1.04 B from $657.00 M. Gross margin rose to 9.2% from 8.9%, and management credits product mix in Intelligent Infrastructure. That segment is now half the business, and its operating margin of 6.0% is still thin.
Put it together. Revenue is concentrated in a business that grows fast and earns little, while the costs of reshaping the company keep arriving. Cost of revenue took $32.64 B, or 90.77% of sales, which leaves little room for a surprise. Connected Living and Digital Commerce, the third business, shrank 3.9% and lost $218.00 M of revenue, even as revenue climbed 21%. Will the charges stop once the fastest-growing business matures, or will they keep returning every year?