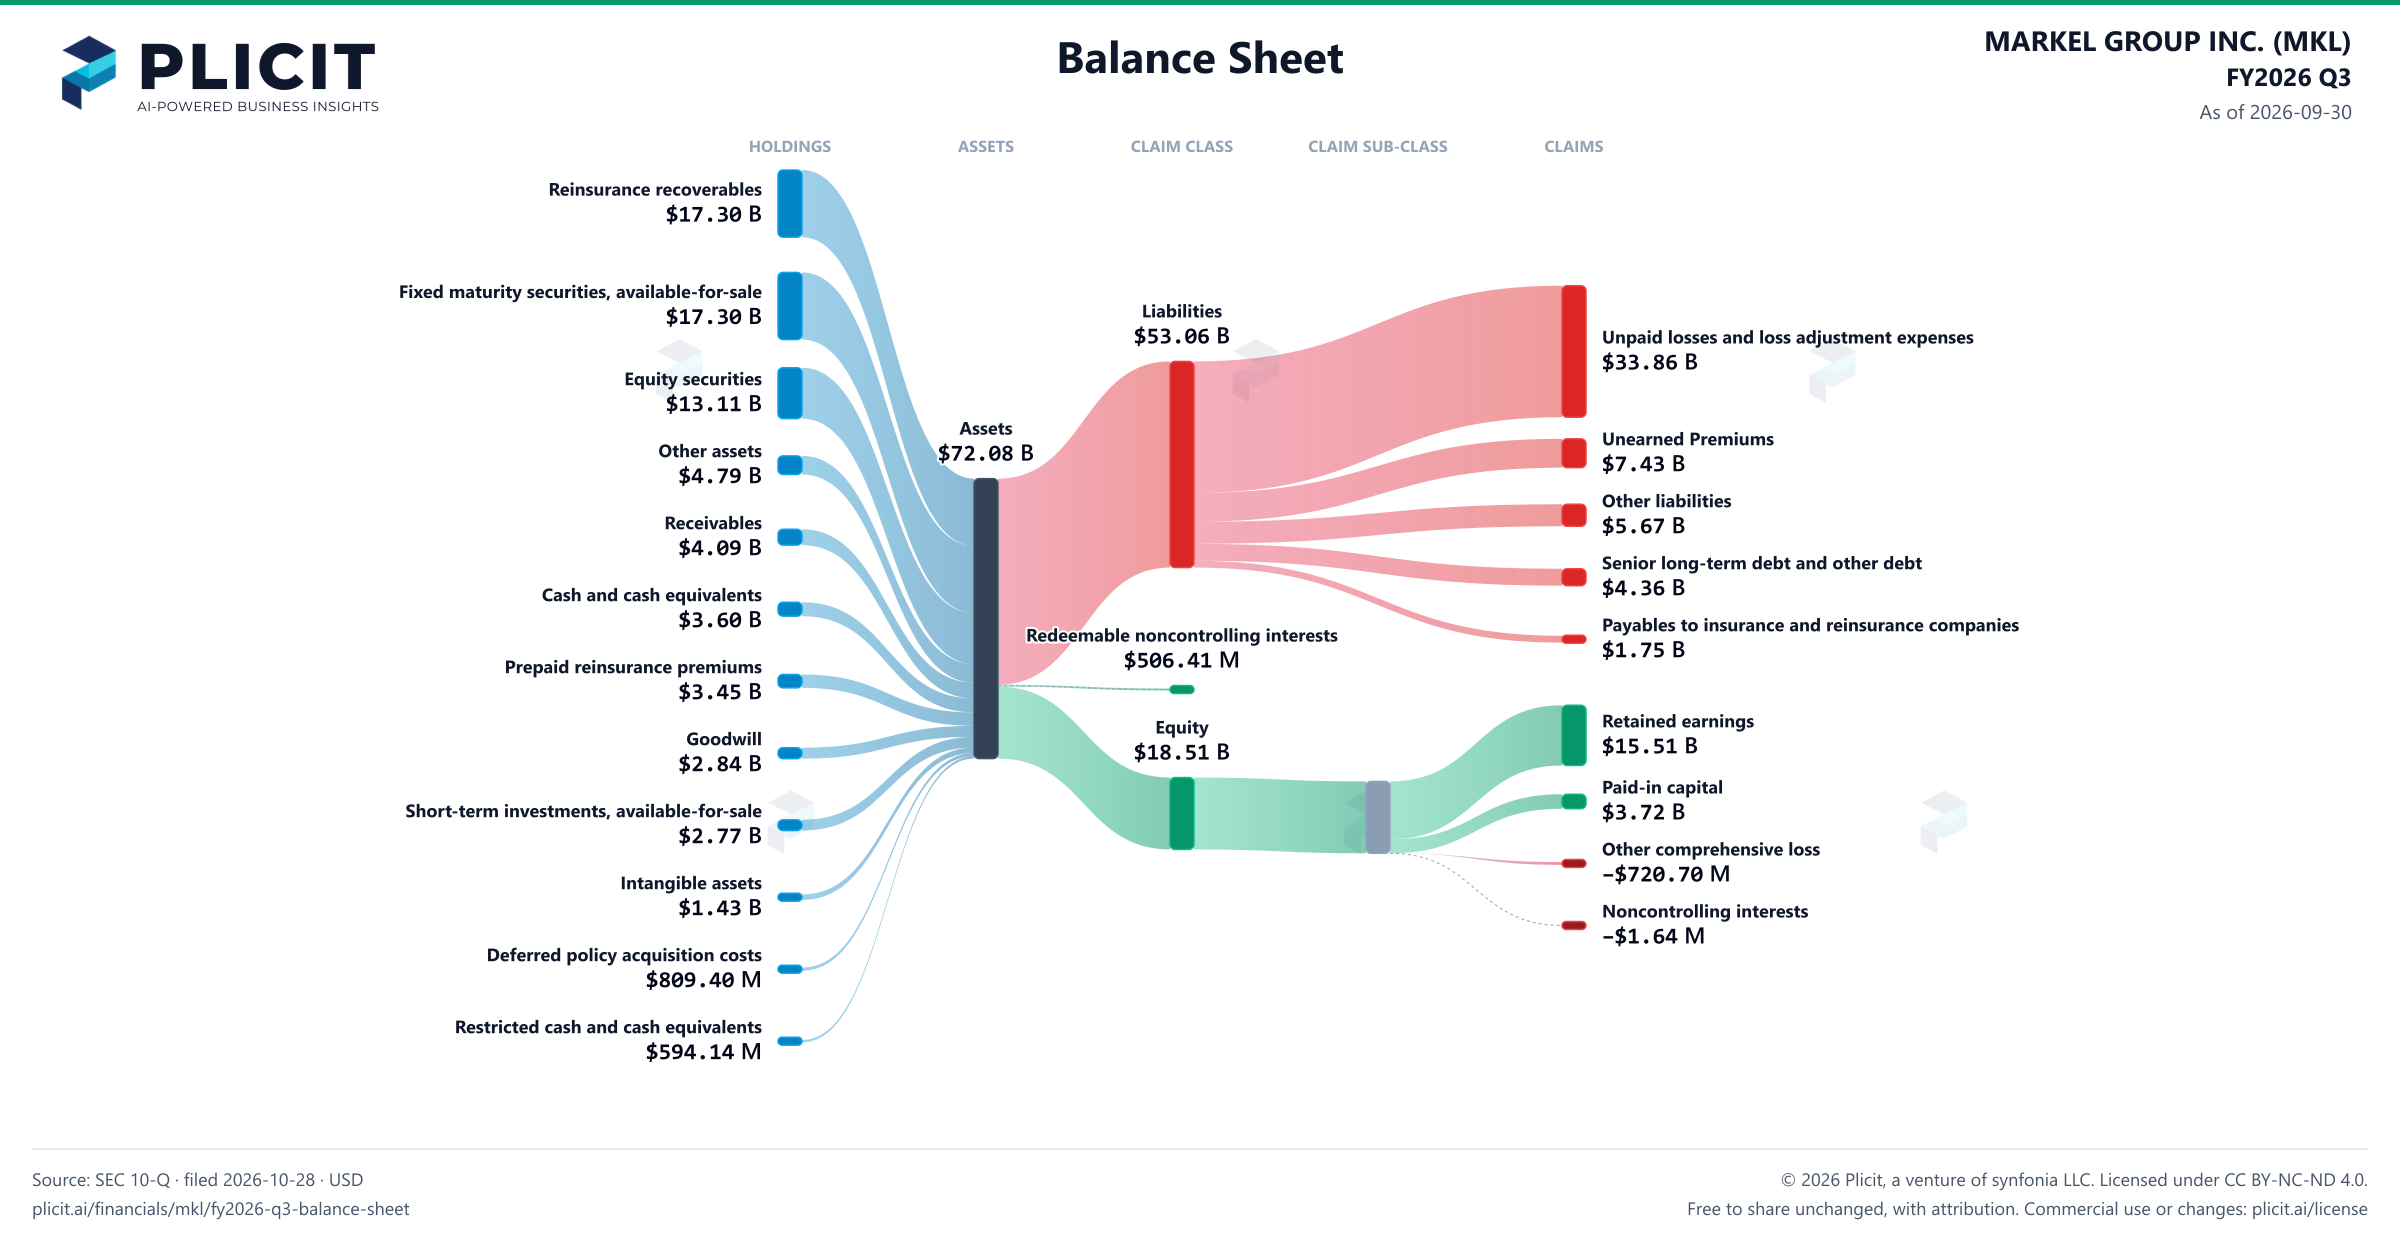
Markel's biggest asset is money its reinsurers owe it
Markel's biggest asset is money its reinsurers owe it. Reinsurance recoverables, the amounts reinsurers owe for claims they agreed to share, reached $17.30 B on September 30, 2026, which is 93% of total equity. Then one capacity provider went into bankruptcy. Markel booked a $205.3 M provision for expected credit losses because it does not expect to collect more collateral from that provider. The asset the balance sheet leans on hardest has already taken that hit. How much of the rest of the $17.30 B could go the same way?
Why does that matter so much? Equity is the cushion that absorbs a bad bet, and against $17.30 B of recoverables, it is thin. Long-term debt of $4.36 B sits beside cash of $3.60 B, so cash would cover 83% of the debt. Unpaid claims rose to $33.86 B from $30.86 B at the last year-end. Those claims are an estimate of what Markel owes, not cash it has set aside. Put the debt, the claims and the reinsurance together, and the balance sheet depends on other companies paying on time.
For a reader, the watch list is short. Markel holds $594.14 M of restricted cash, money set aside for a purpose and not free to spend, next to $3.60 B of cash it can use. Only 15% of its debt securities mature within a year, so they are not a quick source of cash. Management says its reserving philosophy is more likely redundant than deficient. Does the $17.30 B of recoverables collect in full, or is the $205.3 M only the beginning?