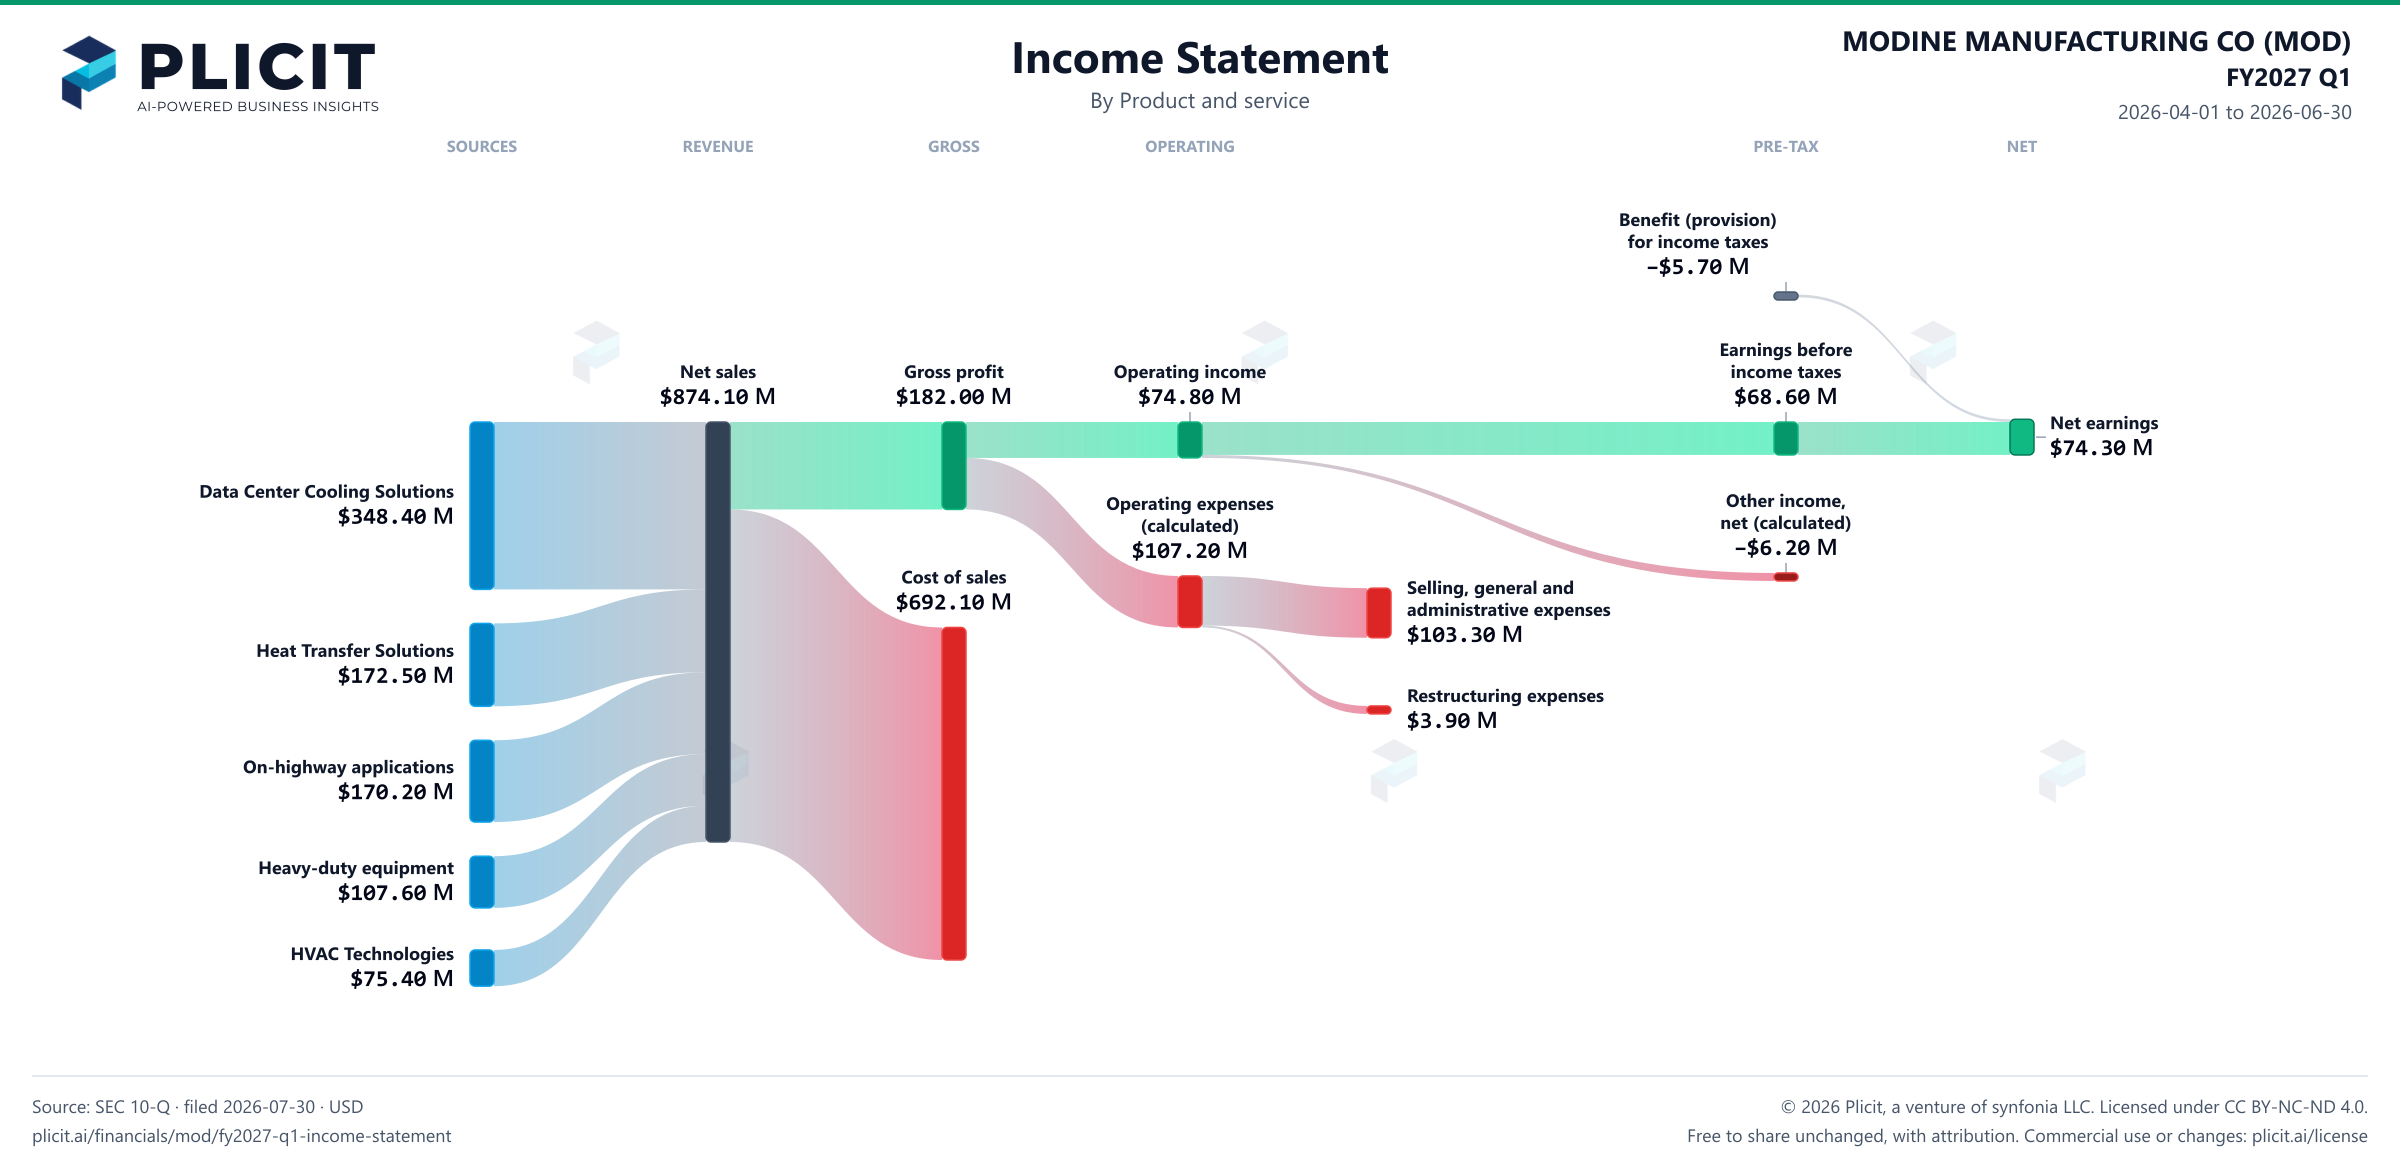
Gross margin fell to 20.8%, and restructuring cost $3.90 M
Restructuring cost $3.90 M this quarter, against $4.80 M a year earlier. The bigger drag is cost of sales, which rose to $692.10 M and ate 79.2% of sales. Management blames higher material costs and operating inefficiencies. Gross profit still rose $16.60 M, to $182.00 M. Operating income slipped $0.90 M to $74.80 M, and net earnings rose $22.60 M. A $19.70 M swing in taxes explains most of that rise. Diluted earnings per share were $1.37, against $0.95 a year earlier.
Follow the sales mix into the margin. Data Center sales carry the sharpest margin drop: gross margin in that segment fell from 29.8% to 20.2%. Data Center Cooling Solutions is the largest line in the business, at 40% of sales. SG&A rose to $103.30 M, from $84.90 M, yet as a share of sales it fell to 11.8%. Interest expense rose to $6.40 M, and the company still covered it 11.7 times. Operating income for the company was $74.80 M, down $0.90 M.
Two things decide the next quarter. Management says supply actions began yielding positive results in the quarter, and that it will keep securing supply. Restructuring cost $3.90 M this quarter, and the restructuring note cites transfers of product lines among facilities. The Performance Technologies spin-off will change the mix as well. Tests of both claims come in the next filing. Will the Data Center margin recover as supply constraints ease, or will restructuring and SG&A keep eating the gain from higher sales?