Data Centers now brings 40% of sales on a thinner margin
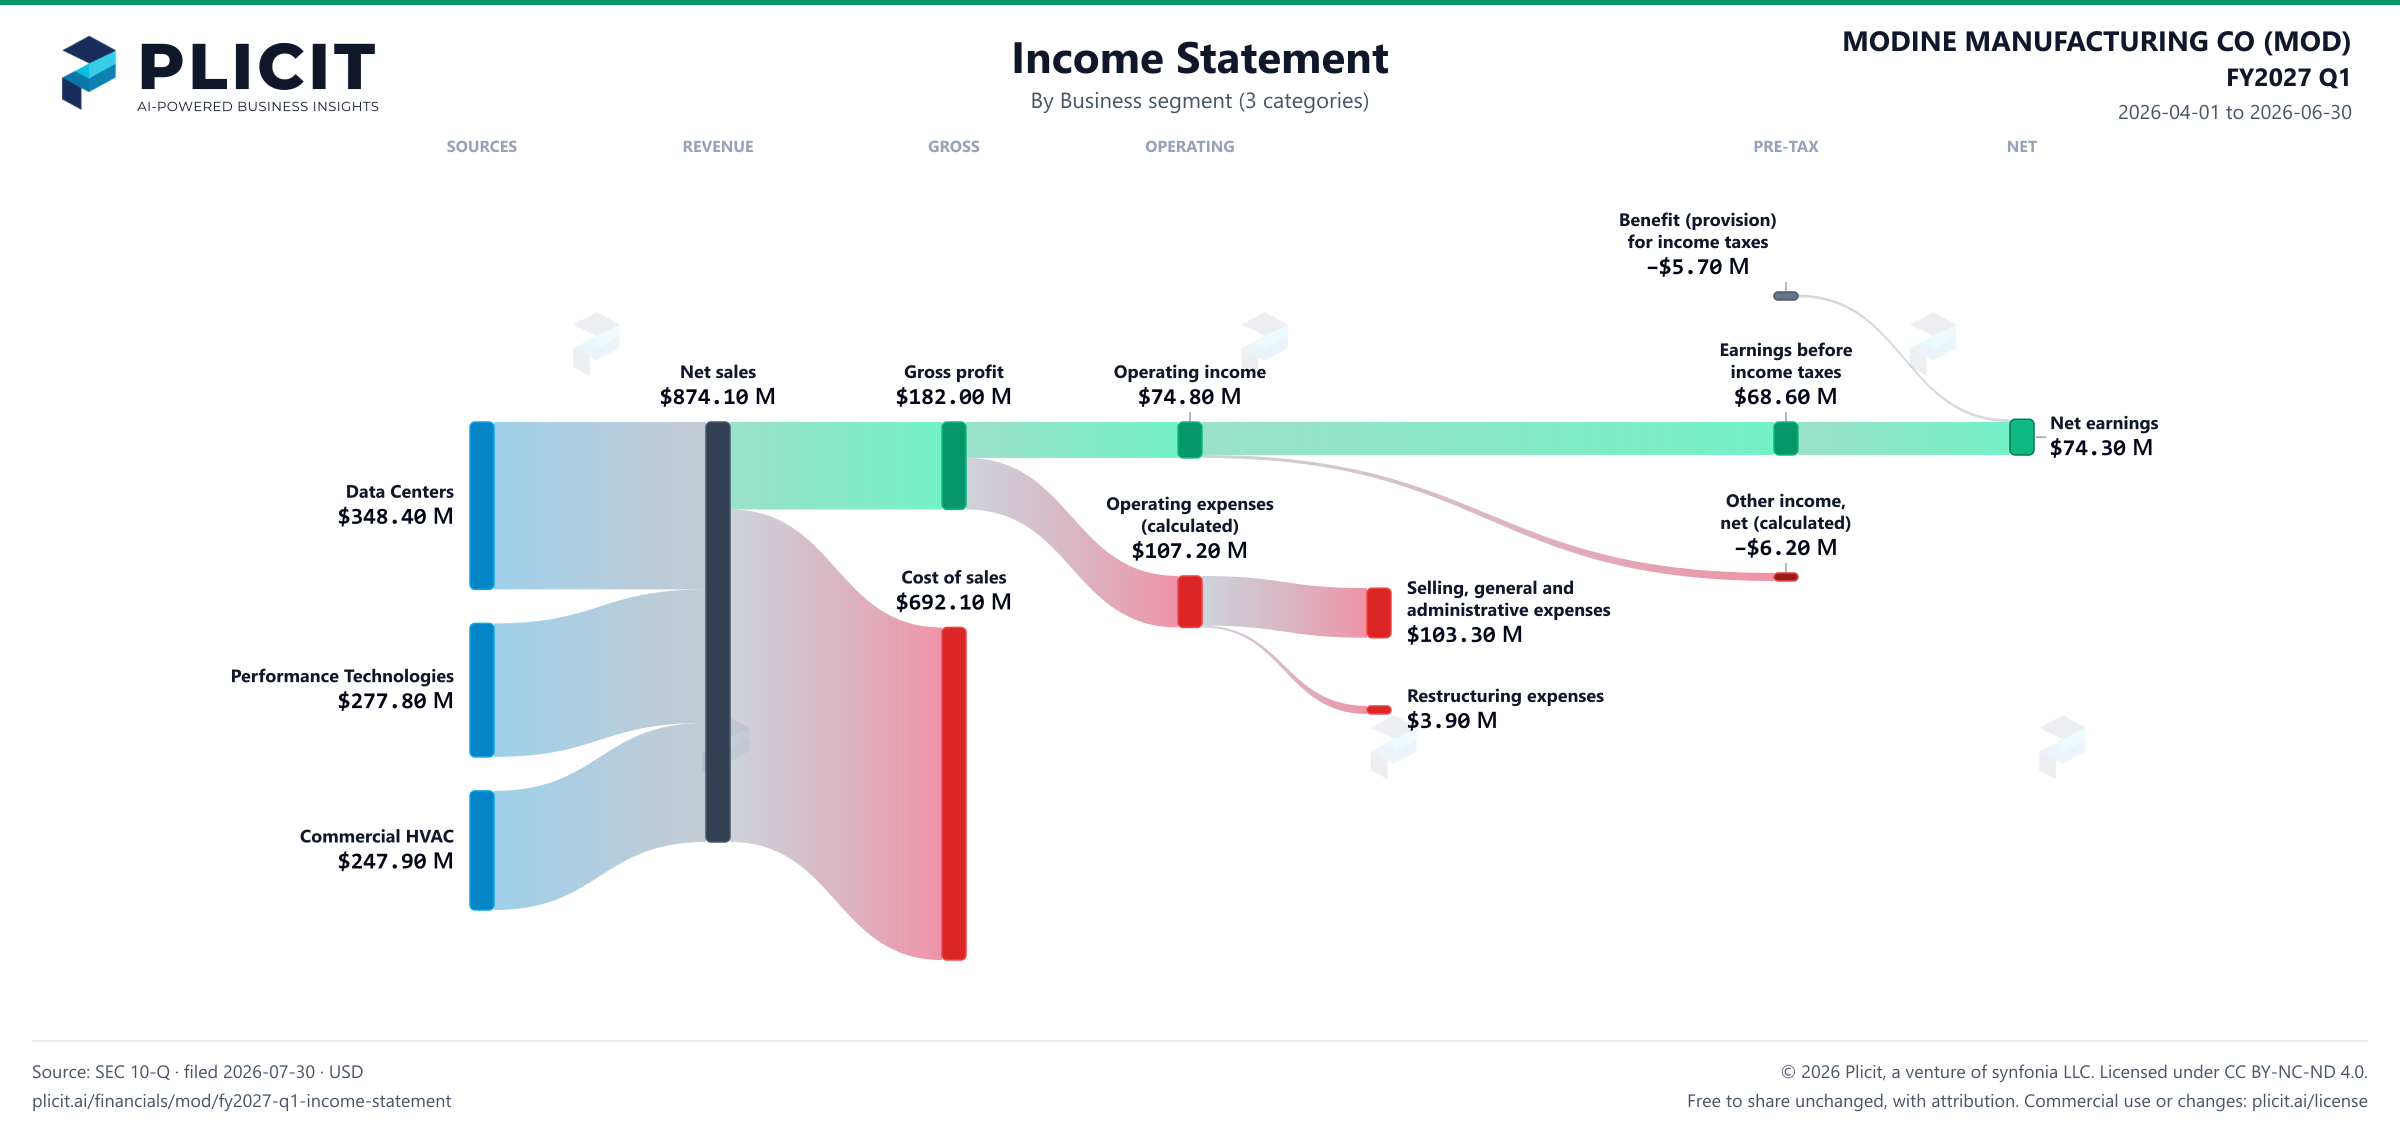
Modine's largest business is also its fastest grower, and that growth is coming at a price. Data Centers sales reached $348.40 M, up from $183.60 M, a jump of 90% in a year. Its gross margin fell to 20.2% from 29.8%, because of higher material costs and supplier capacity constraints while the business expanded. Its operating income still rose $11.60 M, to $46.30 M, primarily due to higher gross profit. Performance Technologies fell 2.7% over the same year, while revenue as a whole rose 28%.
Follow the profit mix, which tells a different story from sales. Data Centers earned $46.30 M of operating income, 44% of what its businesses reported together, against 40% of sales. It added $11.60 M of the $11.90 M rise in combined operating profit. Commercial HVAC fell $0.80 M to $31.40 M, and Performance Technologies rose $1.10 M to $27.60 M. Corporate costs and eliminations took $30.50 M, up from $17.70 M. Those figures cover the first quarter of fiscal 2027 alone.
The open question is whether the margin recovers when supply catches up. Management says the supply actions began yielding positive results in the quarter, and that it will keep securing supply. Performance Technologies, the segment slated for the Gentherm spin-off, earns the least per dollar of sales. Management expects the Gentherm deal to close by the end of calendar 2026. Once it leaves, will Data Centers' gross margin climb back toward the 29.8% it earned a year ago, or will the margin stay thin as the segment grows?