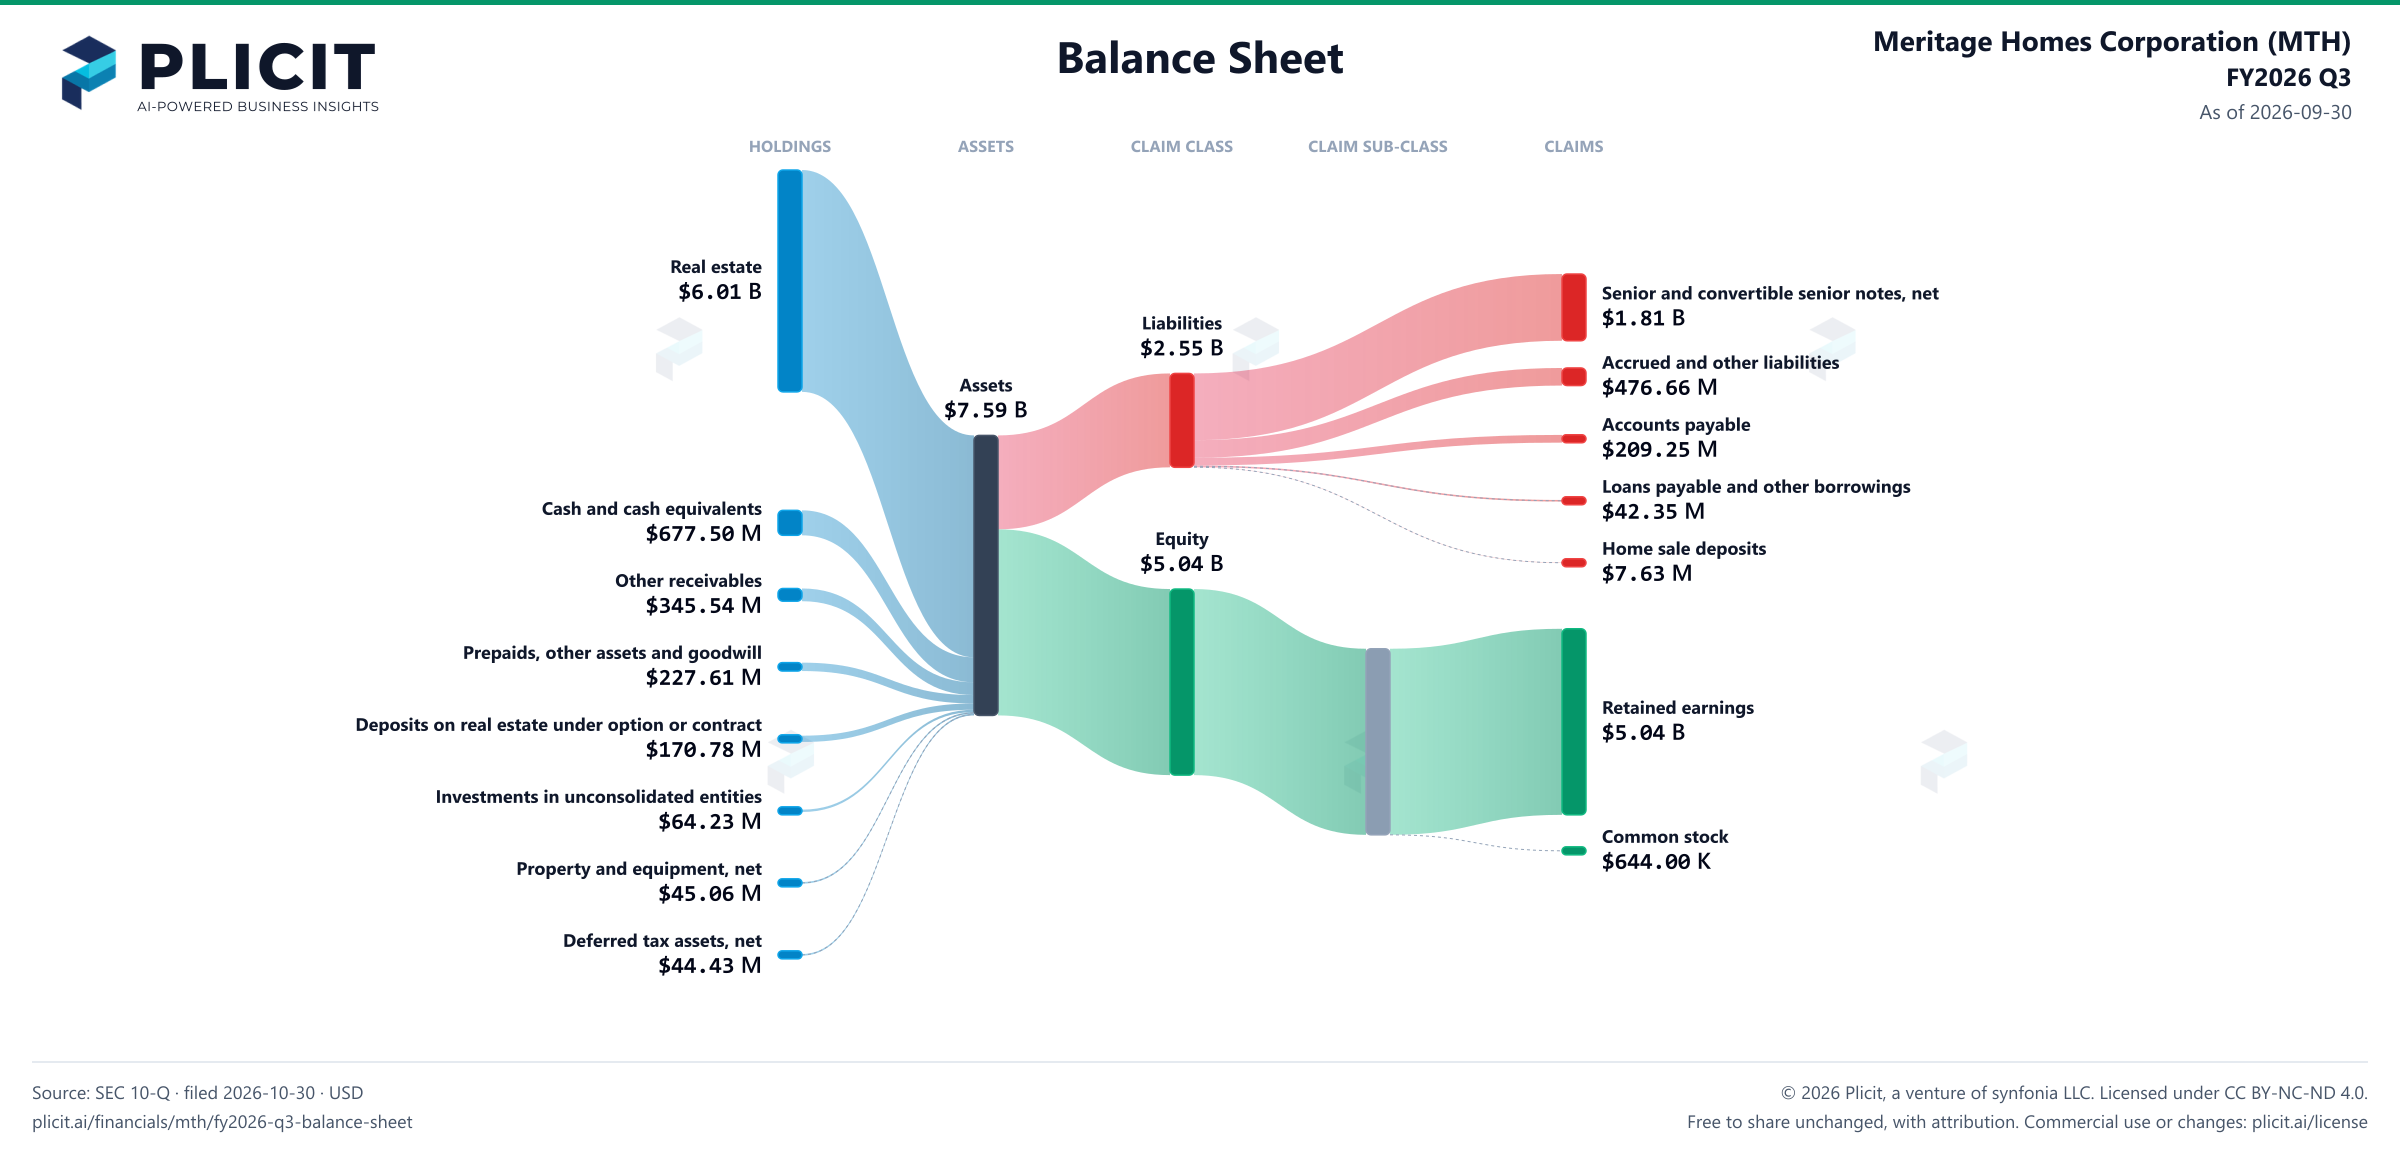
Meritage's $6.01 B pile of land and homes dwarfs its cash
Meritage is a land company with a homebuilder on top. Real estate, from raw lots to finished homes, came to $6.01 B on September 30, 2026, 79% of its $7.59 B of assets. Cash, the only other large asset, fell to $677.50 M from $775.16 M at the last year-end. With sales down 17% this quarter, that inventory now has to be sold into a market where management reports a 13% cancellation rate and more spending on financing incentives to get buyers to close.
Why does the cash keep shrinking? Not because of debt: senior notes held at $1.81 B, about unchanged since year-end. Retained earnings, the profit kept over the company's life, fell 3% to $5.04 B, because this year's buybacks and dividends ran ahead of nine months of profit. The lenders' terms leave room for now. The credit facility requires tangible net worth of at least $3.5 billion and caps leverage at 60%, and management says Meritage was in compliance with all of its covenants at the quarter's end.
For shareholders, book value looks solid: owners' equity of $5.04 B is about twice the $2.55 B Meritage owes. For lenders, the nearer test is the cash line, not the covenants. The real question is the land: real estate barely moved from year-end while sales fell. Management reports fewer impairment and deal termination charges this quarter than a year earlier, so the books have not yet marked that land down in any serious way. If buyers keep needing bigger incentives, will that $6.01 B of land and homes still be worth what Meritage paid for it?