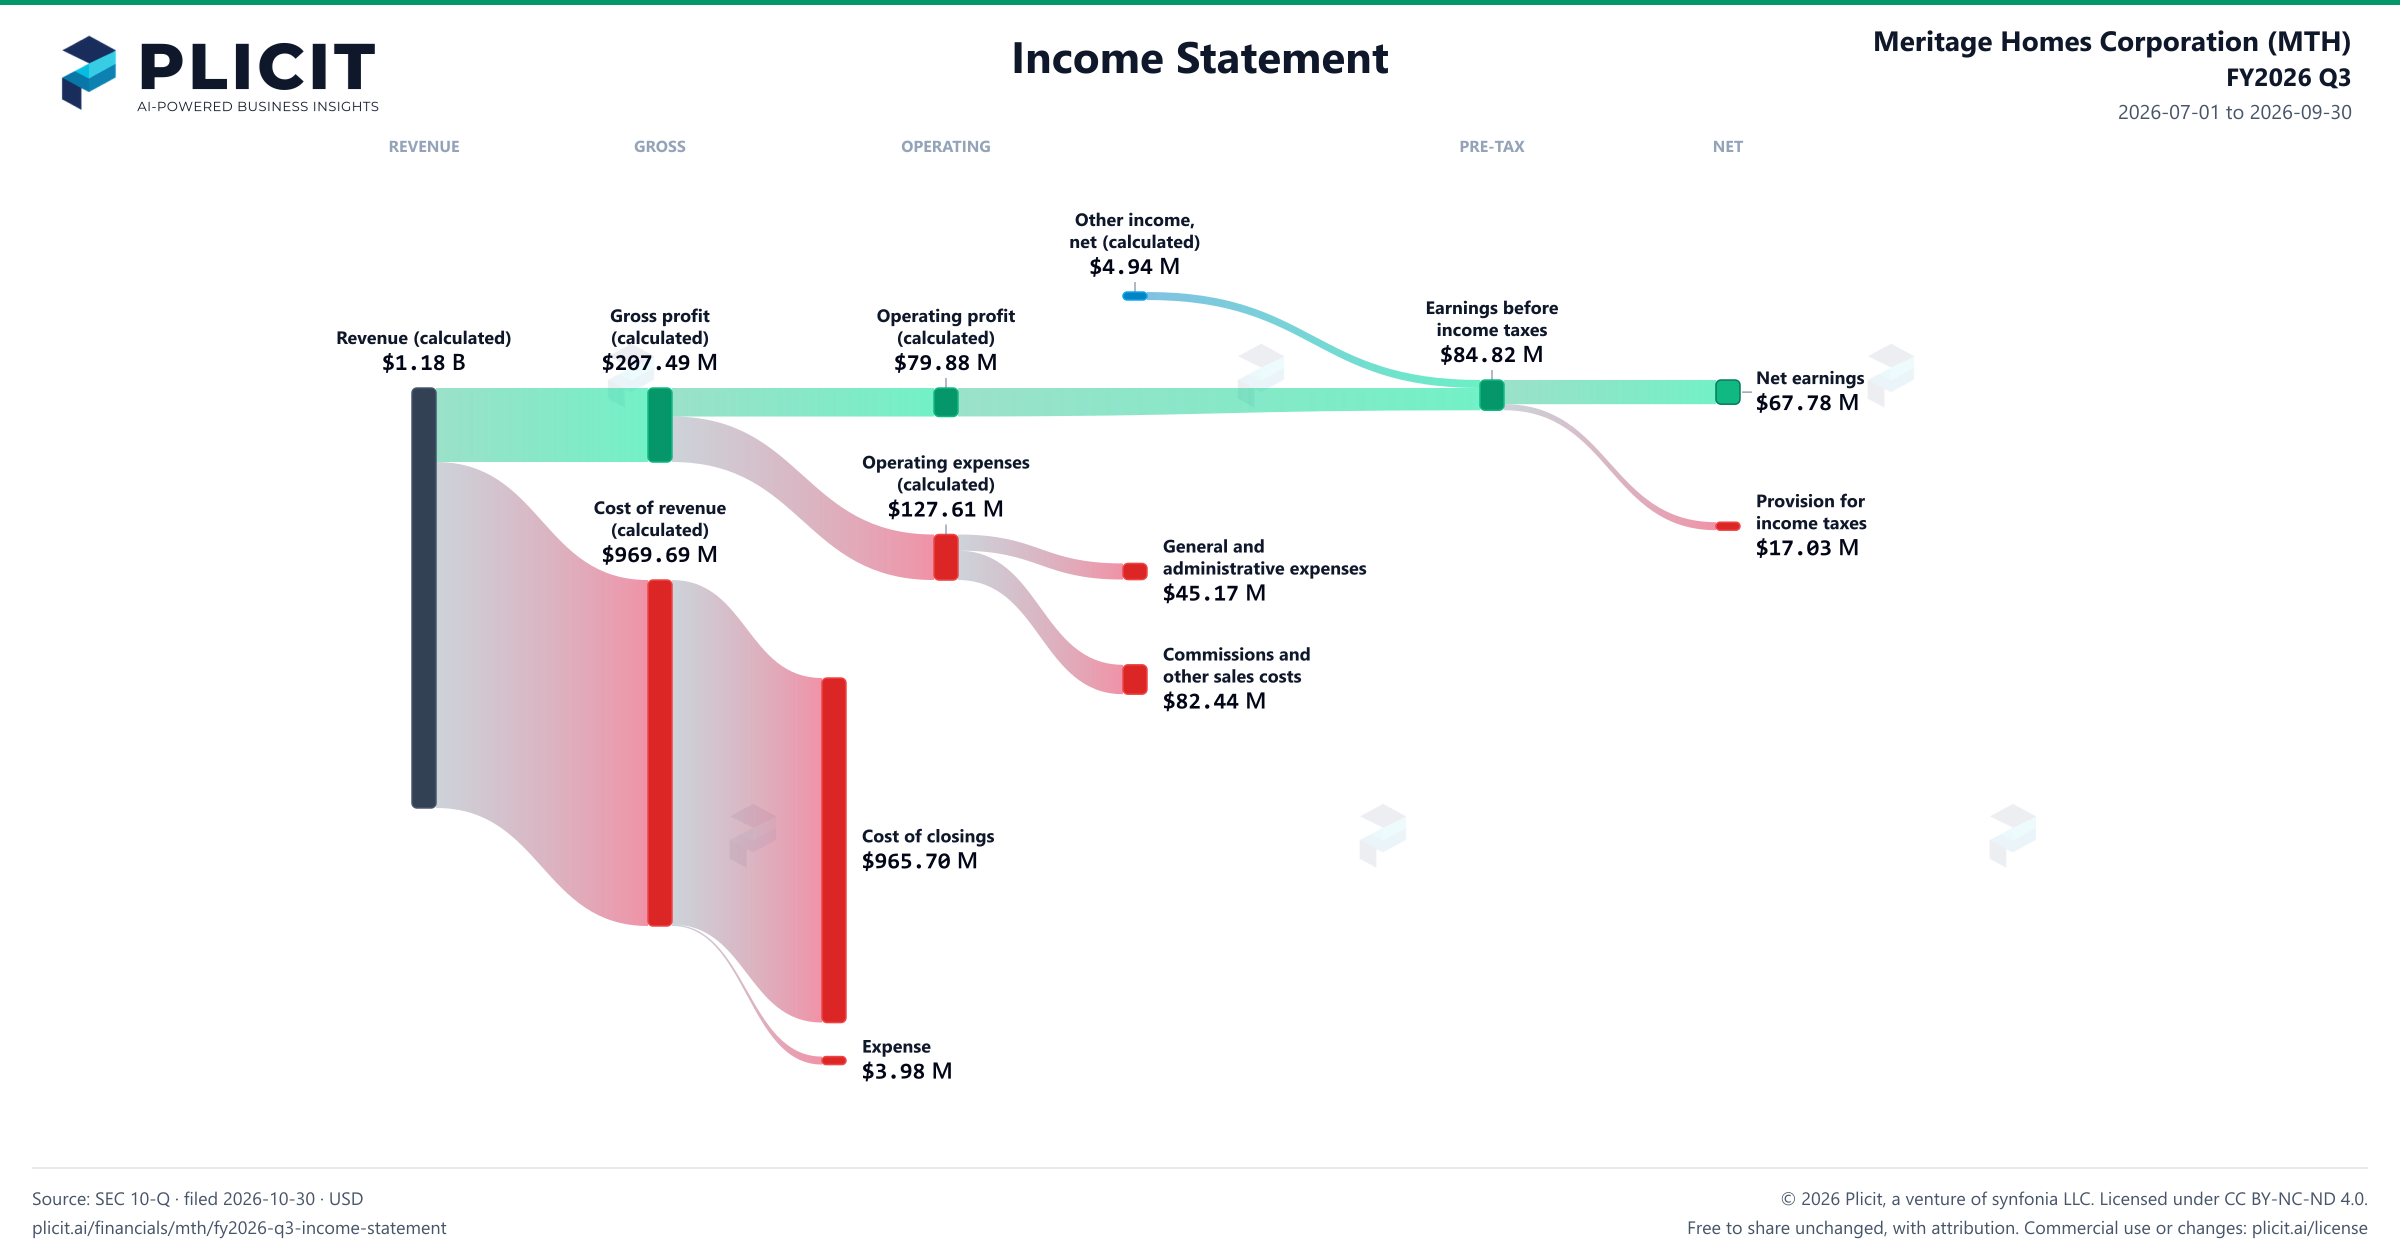
Meritage's sales fell 17% as buyer incentives ate into prices
Meritage Homes closed 3,187 homes this quarter, down 13.5% from 3,685 a year earlier, and sales fell 17% to $1.18 B. Worse, it got less for each house. Management says the average sales price fell 4.0%, and that the lower price is "primarily due to increased use and cost of financing incentives", the money a builder spends to bring down a buyer's mortgage rate. Orders point the same way. Management reports the cancellation rate rose to 13% from 11%, "reflecting the tougher selling environment."
Why did profit fall faster than sales? Gross margin, the share of sales left after building the homes, slid to 17.6% from 19.1%. Management attributes the squeeze to "higher incentives and lot costs and lost leverage on lower home closing revenue". Overhead did not shrink as fast as sales: selling and administrative costs took 10.8% of sales, up from 10.6%. Pretax earnings fell 34%, while profit fell 32% to $67.78 M. A lower tax rate, 20.1% against 22.6%, made the difference, and management credits tax credits it bought below market for it.
For shareholders, the cushion is buybacks: diluted shares fell 9%, so earnings per share fell 25%, less than profit did. But the engine is slowing. Orders fell 15.2% to 3,083 homes, and backlog ended at 1,611 homes, down 5.2%, so Meritage starts the next quarter with fewer homes already sold. Watch the average price and the incentive bill together. If incentives have to keep climbing just to hold volume, does Meritage still have a margin floor, or is it buying sales it cannot profit from?