Most of Rocket's equity jump came from a stock deal, not profit
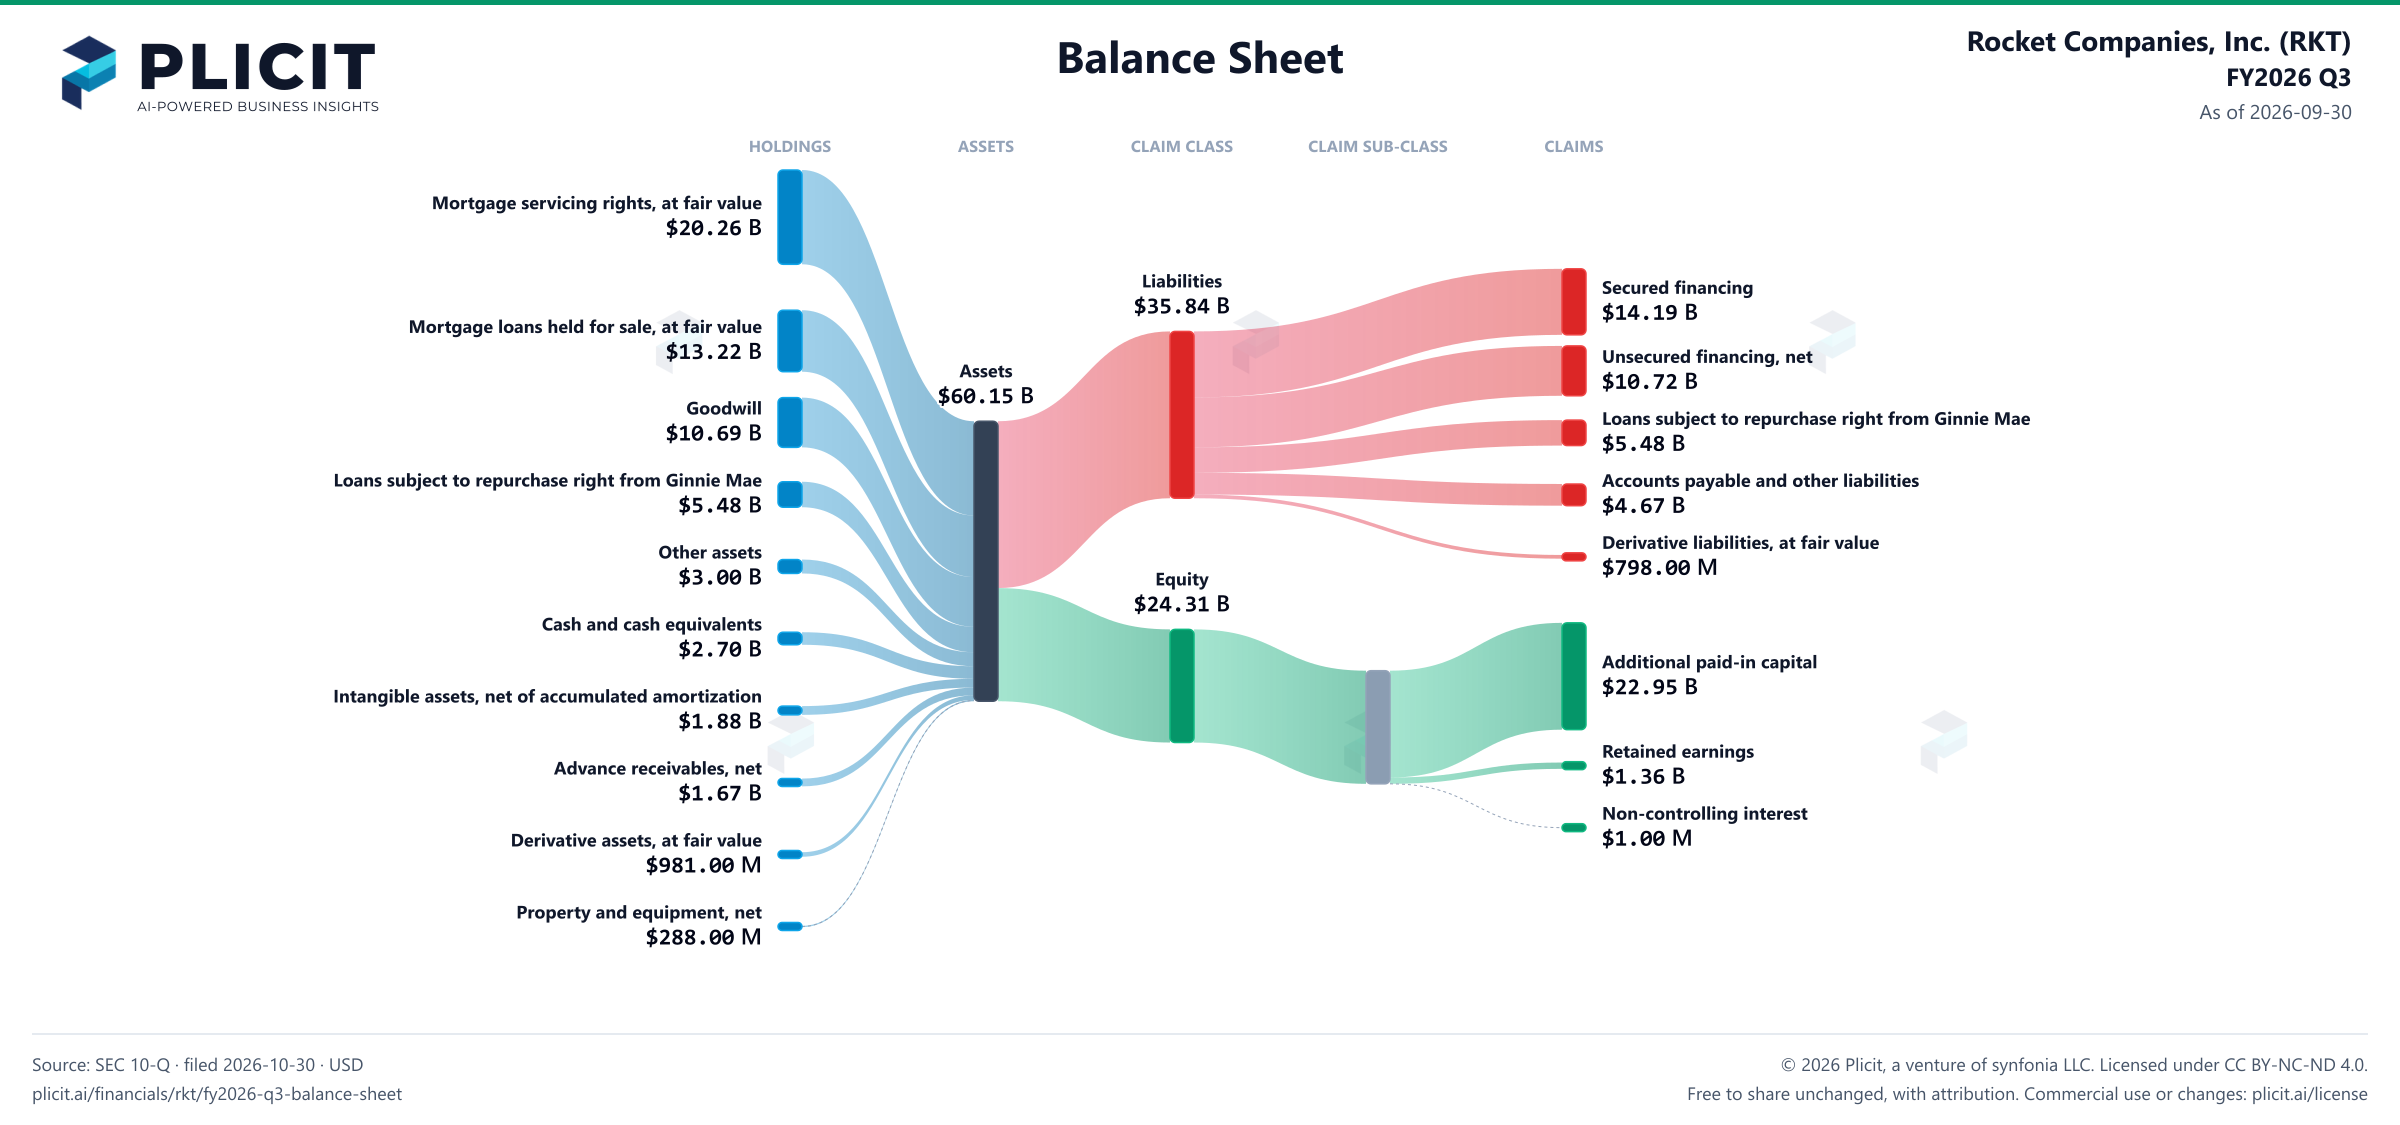
Rocket Companies owed $24.90 B on September 30, 2026, and its cash covered only 11% of that. The debt was $28.36 B at the last year-end, and secured financing, the short-term loans that fund mortgages until they are sold, fell by $3.75 B. Cash was $2.70 B on both dates, so the paydown did not come from a bigger cash pile. The bigger surprise sits on the equity side, where the filing says the money came from a stock deal.
Assets tell the same story. The biggest asset is $20.26 B of mortgage servicing rights, valued at fair value, which means an estimate of what they would fetch today, and it equals 34% of everything Rocket owns. Goodwill and intangible assets, left behind by acquisitions, equal 52% of equity. Retained earnings, the profit the company kept over its life, are only $1.36 B, about 6% of equity. Those are the assets that carry the balance sheet, and each one depends on an estimate or a past deal.
Put together, the owners' stake rests mostly on acquisition accounting and on servicing rights valued by estimate, not on profit kept over the years. The debt depends on lenders, and cash covers only 11% of it, so the balance sheet holds only while those lenders keep lending and those valuations hold. What would the $24.31 B of equity look like if the servicing rights had to be marked at the price a buyer would pay for them today?