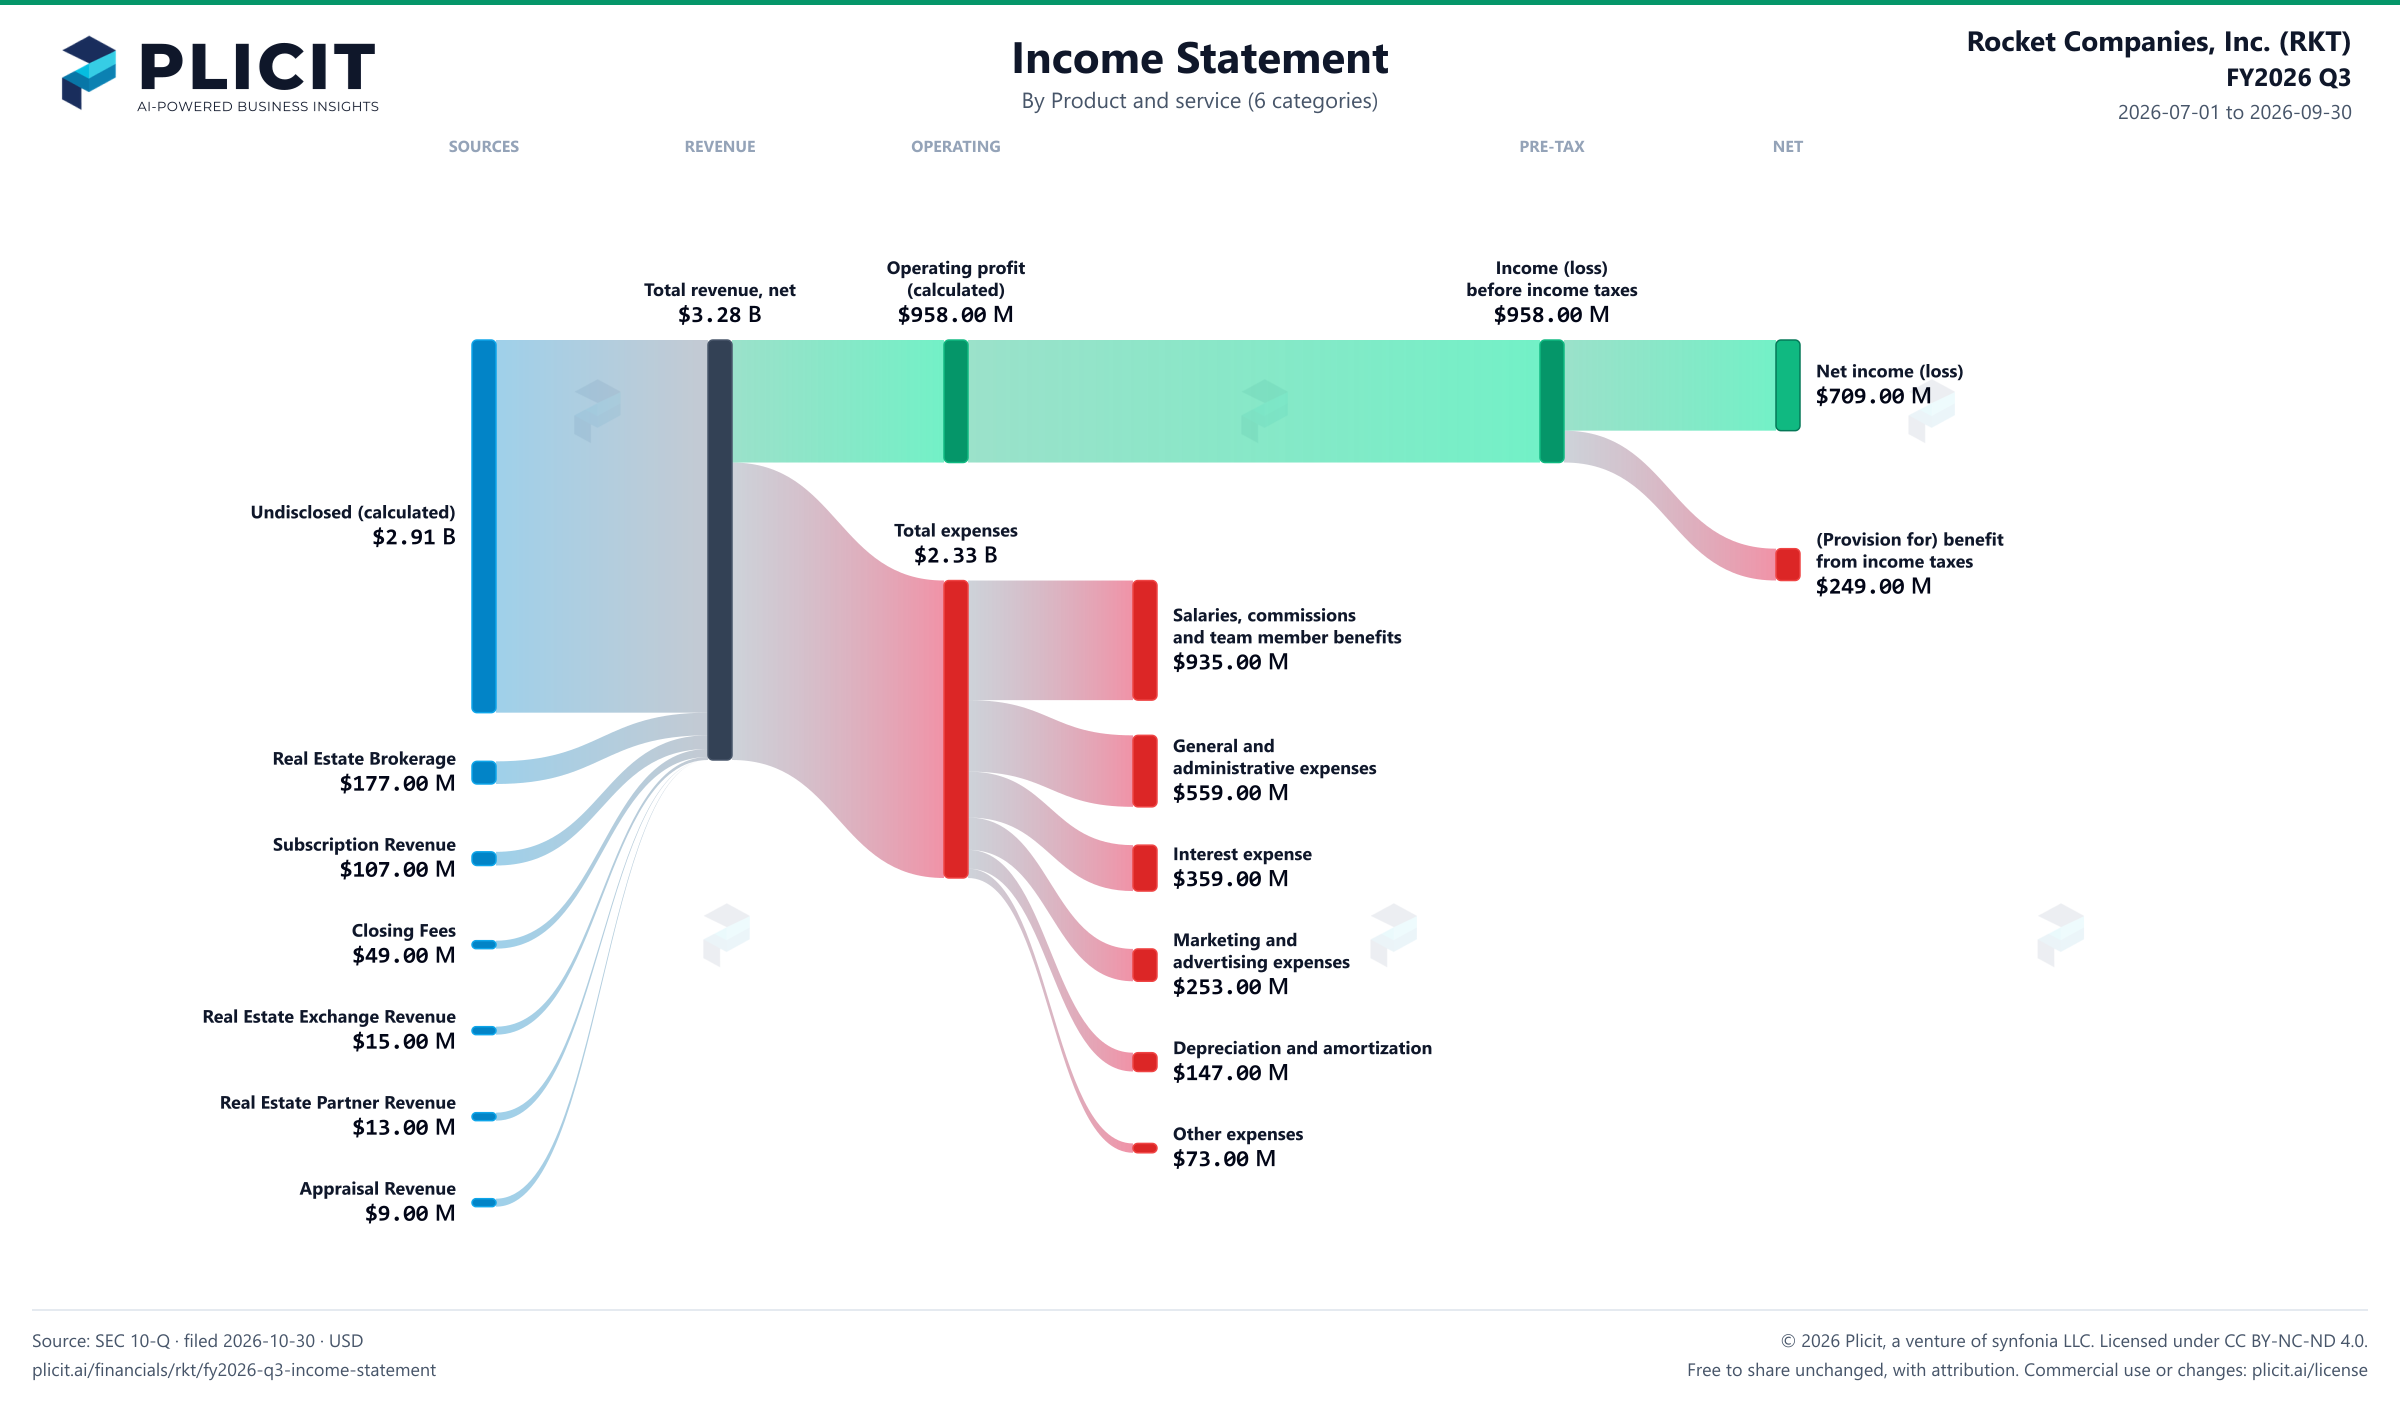
Paper gains on servicing rights almost matched Rocket's pre-tax profit
Rocket Companies earned $709.00 M this quarter on $3.28 B of sales, and that looks comfortable until you read where the pre-tax number comes from. Pre-tax income was $958.00 M. Fair-value gains on servicing rights added $882.00 M to revenue, nearly all of that pre-tax profit. Take those paper gains away and pre-tax profit would have shrunk to $76.00 M. The net profit is real, but its size depends on how the servicing rights are valued. That is the first thing to know before trusting the headline.
Why does an accounting gain matter? Because the company books the value of a servicing right when it originates a loan, long before any fee arrives. The nine-month cash flow strips out $2.17 B of that originated value as non-cash, so the gain is a valuation, not money in hand. Cash comes later, when rights are sold: the nine months show $1.75 B of net proceeds from selling servicing rights.
For a reader, the lesson is to separate the profit that arrived as cash from the profit that arrived as a valuation. Watch the sales of servicing rights, the nine-month cash line and the fair-value marks each quarter, because they show whether the gain is turning into money. The filing gives the pieces, and the reader can tie them together. If those valuations reset next quarter, how much of the $709.00 M would still be left?