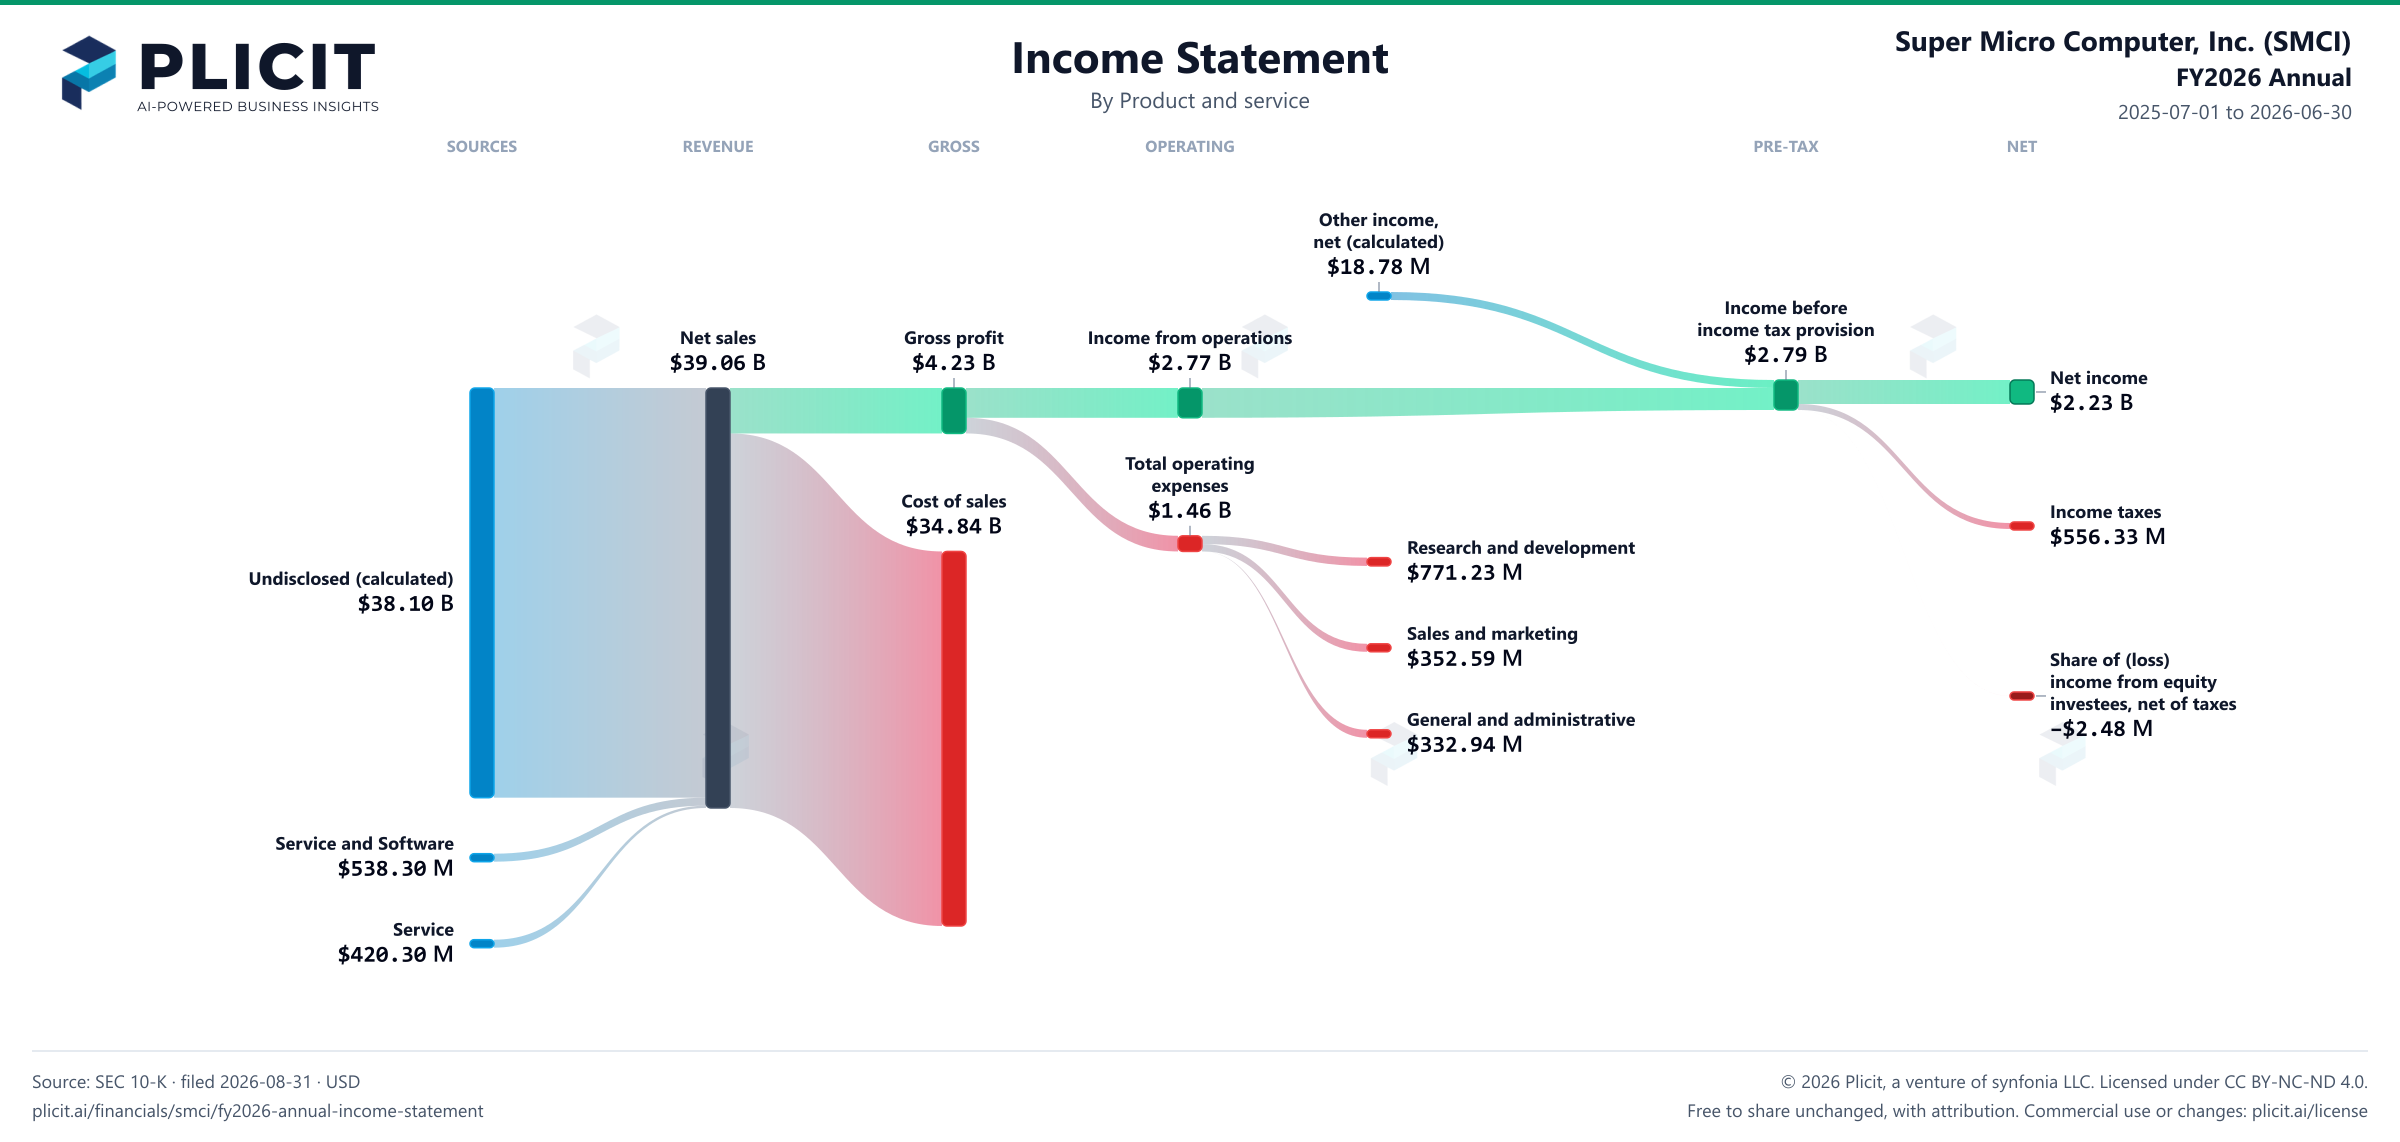
Revenue jumped 78%, but gross margin slipped to 10.8%
Super Micro Computer's income statement looks strong on the surface. Net income reached $2.23 B on $39.06 B of sales, and operating profit more than doubled to $2.77 B. Sales rose 78%, from $21.97 B. Management credits the gains to strong demand and increased billing for Hyper Servers, GPU & Super Racks. Services and software, at $538.30 M, contributed to growth, although product revenue remained the primary driver. Product sales, not services, carried the year, which matters for the margin story that follows.
The margin tells the other side. Gross margin fell to 10.8% from 11.1% as the company priced to win share and shifted its product and customer mix. The filing reports that a $237.7 million tariff increase rose 228.3% on the year, and that lower vendor rebates added $312.9 million to cost of sales. Cost of sales now takes 89.18% of sales. Pricing and mix are choices the company made, and the margin shows what those choices cost.
Where does the money go after gross profit? Research spending fell from 2.9% of sales to 2.0%, and operating profit covered interest 14.2 times, down from 21.0 times. The backlog is another cushion: $2.61 B of contracted work not yet delivered, equal to 7% of sales. Management expects 60% of that backlog to become revenue within a year. Those are the two numbers to watch next. Will the margin recover as that backlog turns into revenue, or will the pricing that cut it keep going?