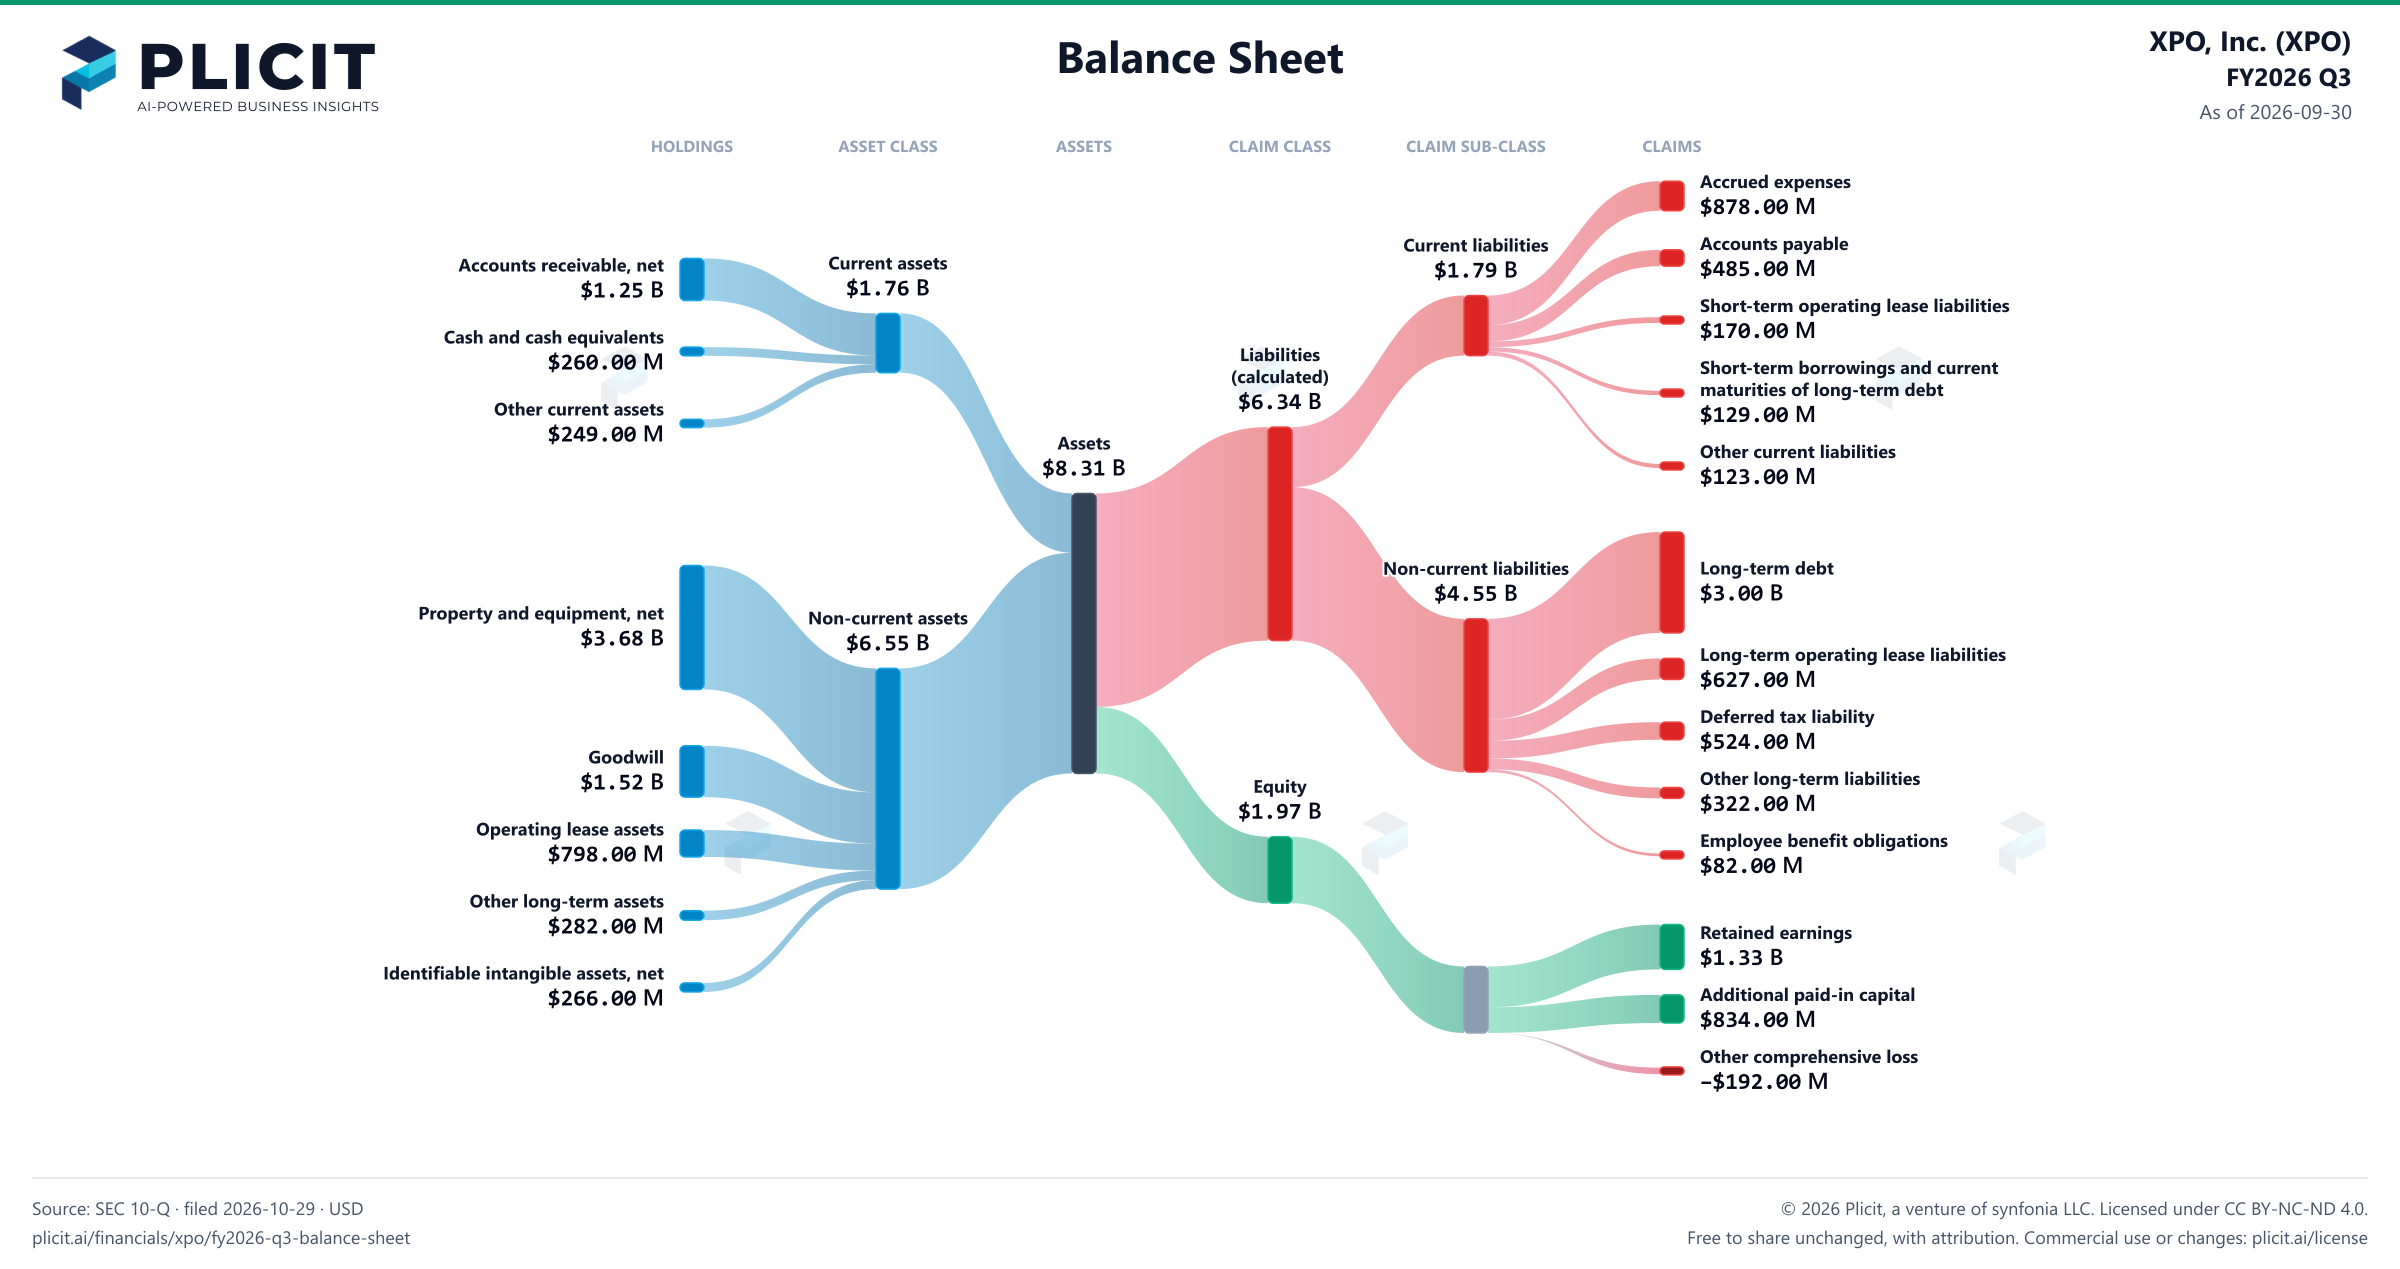
XPO's cash covers only 9% of its long-term debt
XPO's cushion thinned over the quarter. Cash fell to $260.00 M, down 16% from $310.00 M at the last year-end. The company owed $3.00 B of long-term debt against that cash, so its cash covers only 9% of the debt. Bills due within a year came to $1.79 B, more than the cash on hand. The balance sheet does not say which of those bills fall due first. Nothing in this balance sheet shows where the rest of that money will come from.
The whys lead to how XPO is funded. Liabilities carry most of the load: XPO owed $6.34 B against $1.97 B of owners' money. After goodwill and intangibles, owners' net worth is $183.00 M, up from $3.00 M a year earlier. Retained earnings rose 50% to $1.33 B, so profit has been building up. Owners' money is the cushion that absorbs a loss before lenders are hit. Lenders are owed 47% of what XPO owes. That makes the debt, not the bills, the bigger lever.
For a reader, the balance sheet says XPO has built up profit but leans on borrowing to fund itself. Goodwill and intangibles total $1.79 B, and their worth depends on what the businesses bought can still earn. The filing does not say what those assets would fetch if sold. The cash on hand is the first line of defence, and it is smaller than a year ago. What settles it: will the next quarter's cash cover the $1.79 B due within a year, or will new borrowing fill the gap?