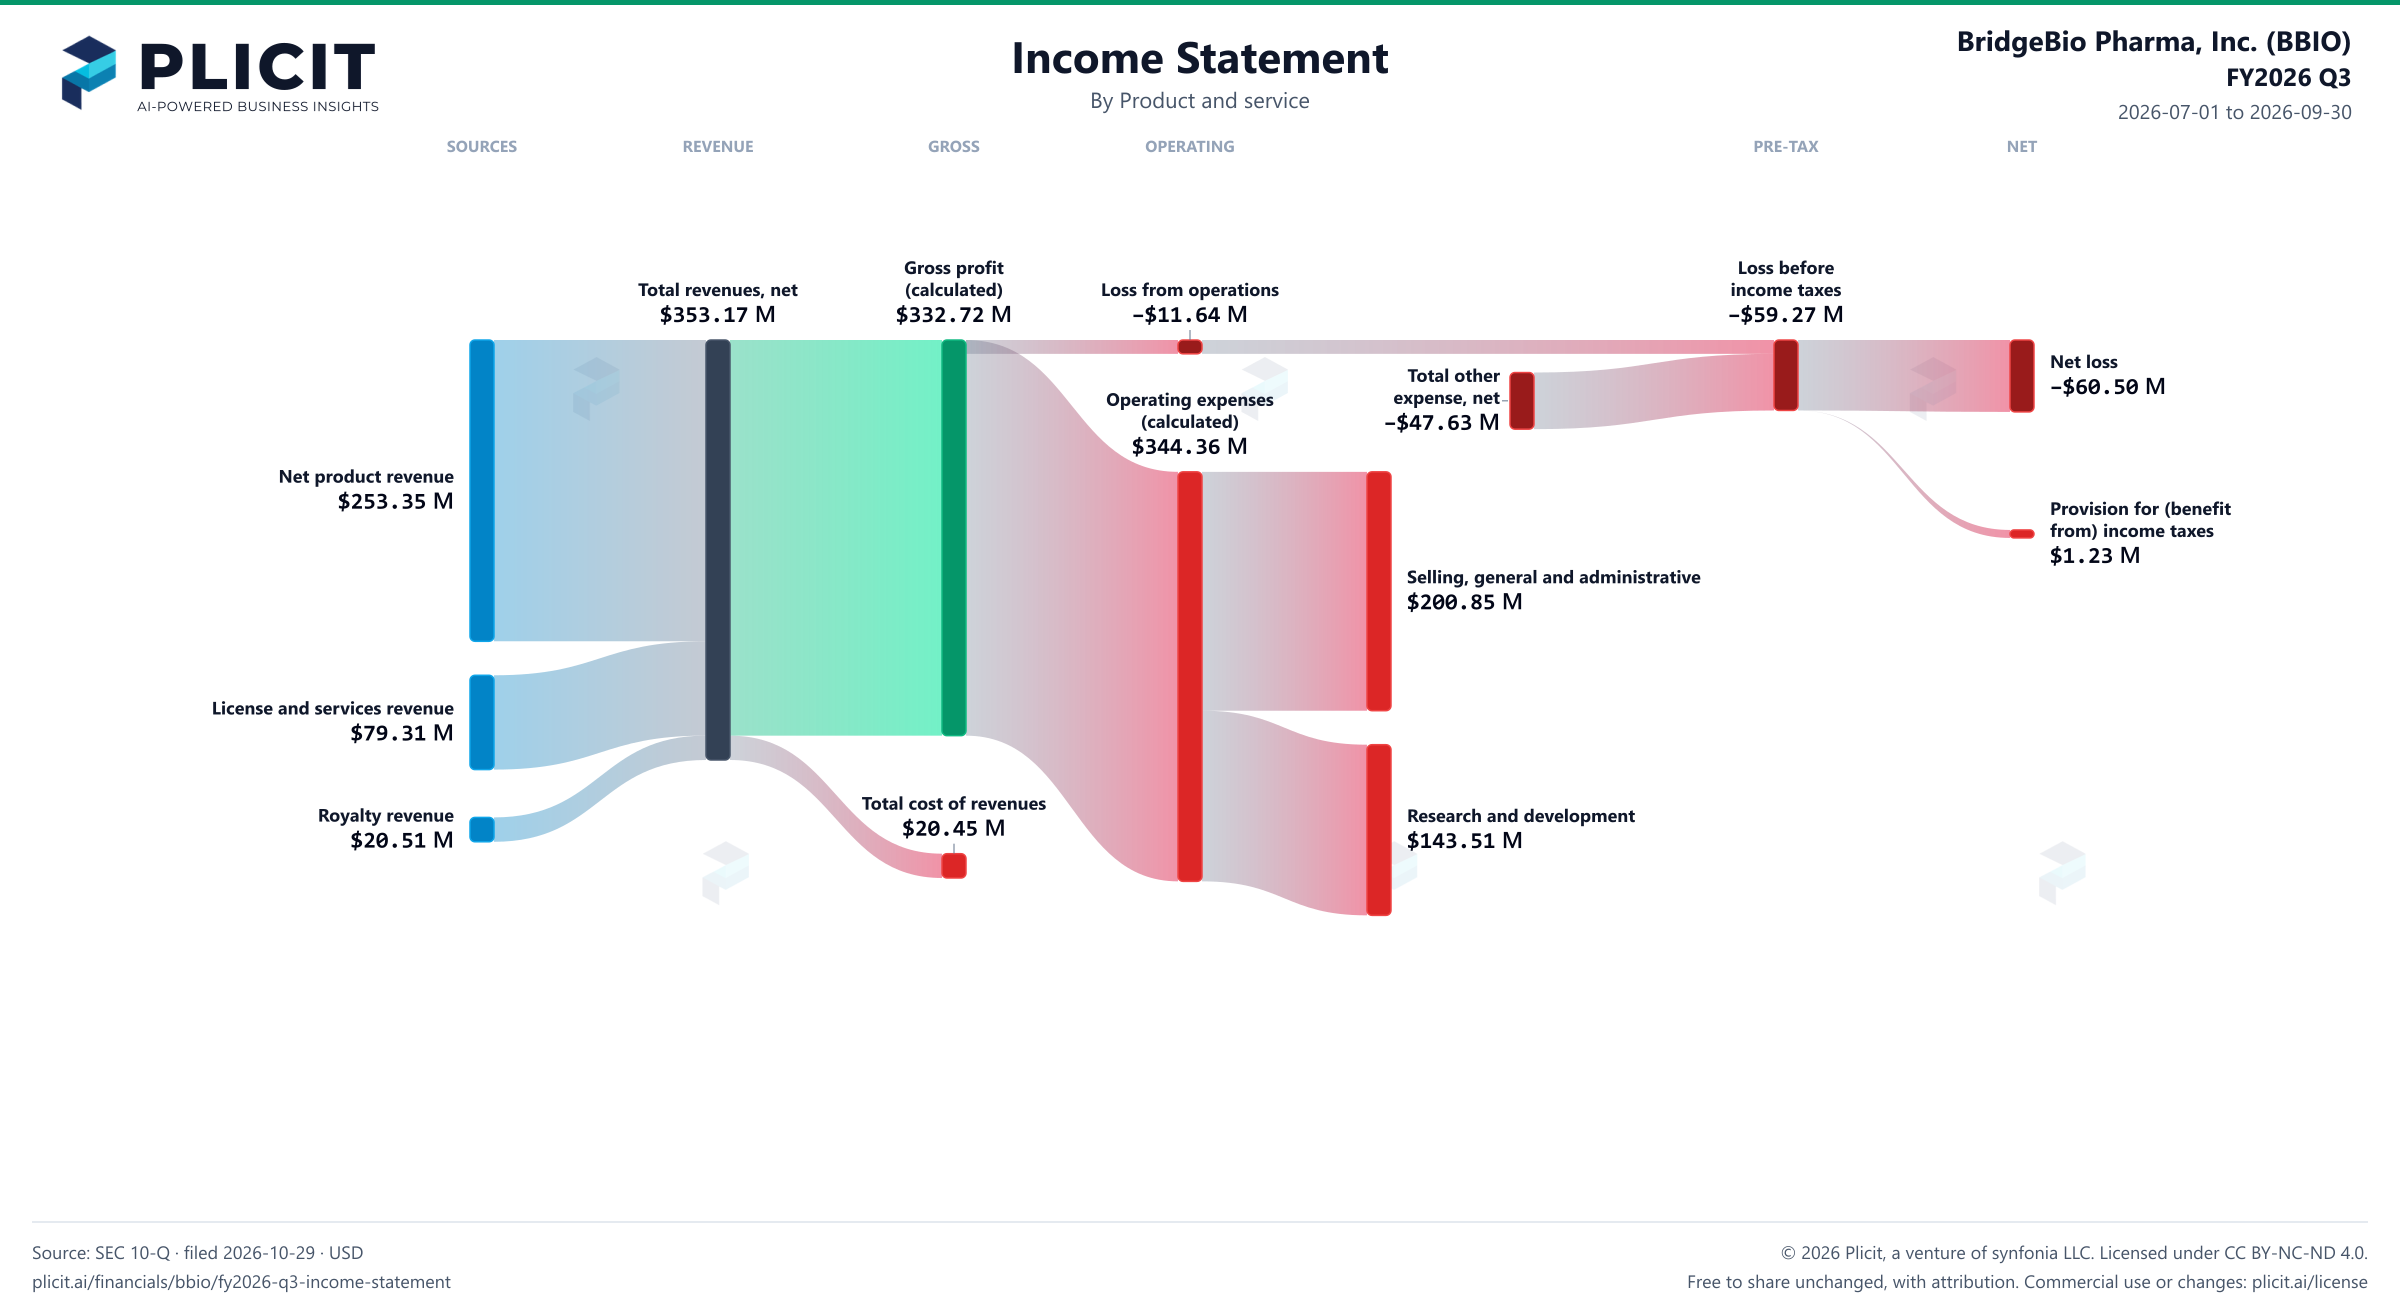
BridgeBio's sales rose 193%, yet the quarter still lost money
BridgeBio's sales rose 193% this quarter, to $353.17 M, and the headline looks like a turnaround. Look under the total. Net product revenue reached $253.35 M, a real gain. The filing says the license line's rise came mainly from a $75.0 M sales milestone under the Bayer License Agreement. That one milestone was 32% of the quarter's $232.47 M rise in sales. Over nine months, license and services revenue actually fell 29%, from $125.44 M to $89.54 M. Without the milestone, the loss would have been about $135.50 M, all else equal.
Why does the loss survive a surge in sales? Research, selling and overhead costs took $344.36 M, more than the $332.72 M of gross profit left after direct costs. Management says the research increase is primarily driven by late-stage programs. The larger drag sits below the operating line, at $42.28 M of noncash interest on deferred royalty obligations, which the filing treats as debt owed to royalty purchasers. That charge is not paid in cash, so it widens the loss without draining the bank account.
What it means: the product line is the real engine, up 134% to $253.35 M, but it does not yet carry the whole cost base. The milestone was a single event, so the quarter's growth rate cannot be read as a run rate. Interest on its debt and royalty obligations ran $55.54 M in the quarter, on top of the operating loss. Nine months of product sales show the same pattern, with license income swinging while product revenue keeps climbing. Will product sales alone cover research, overhead and interest in a quarter with no milestone?