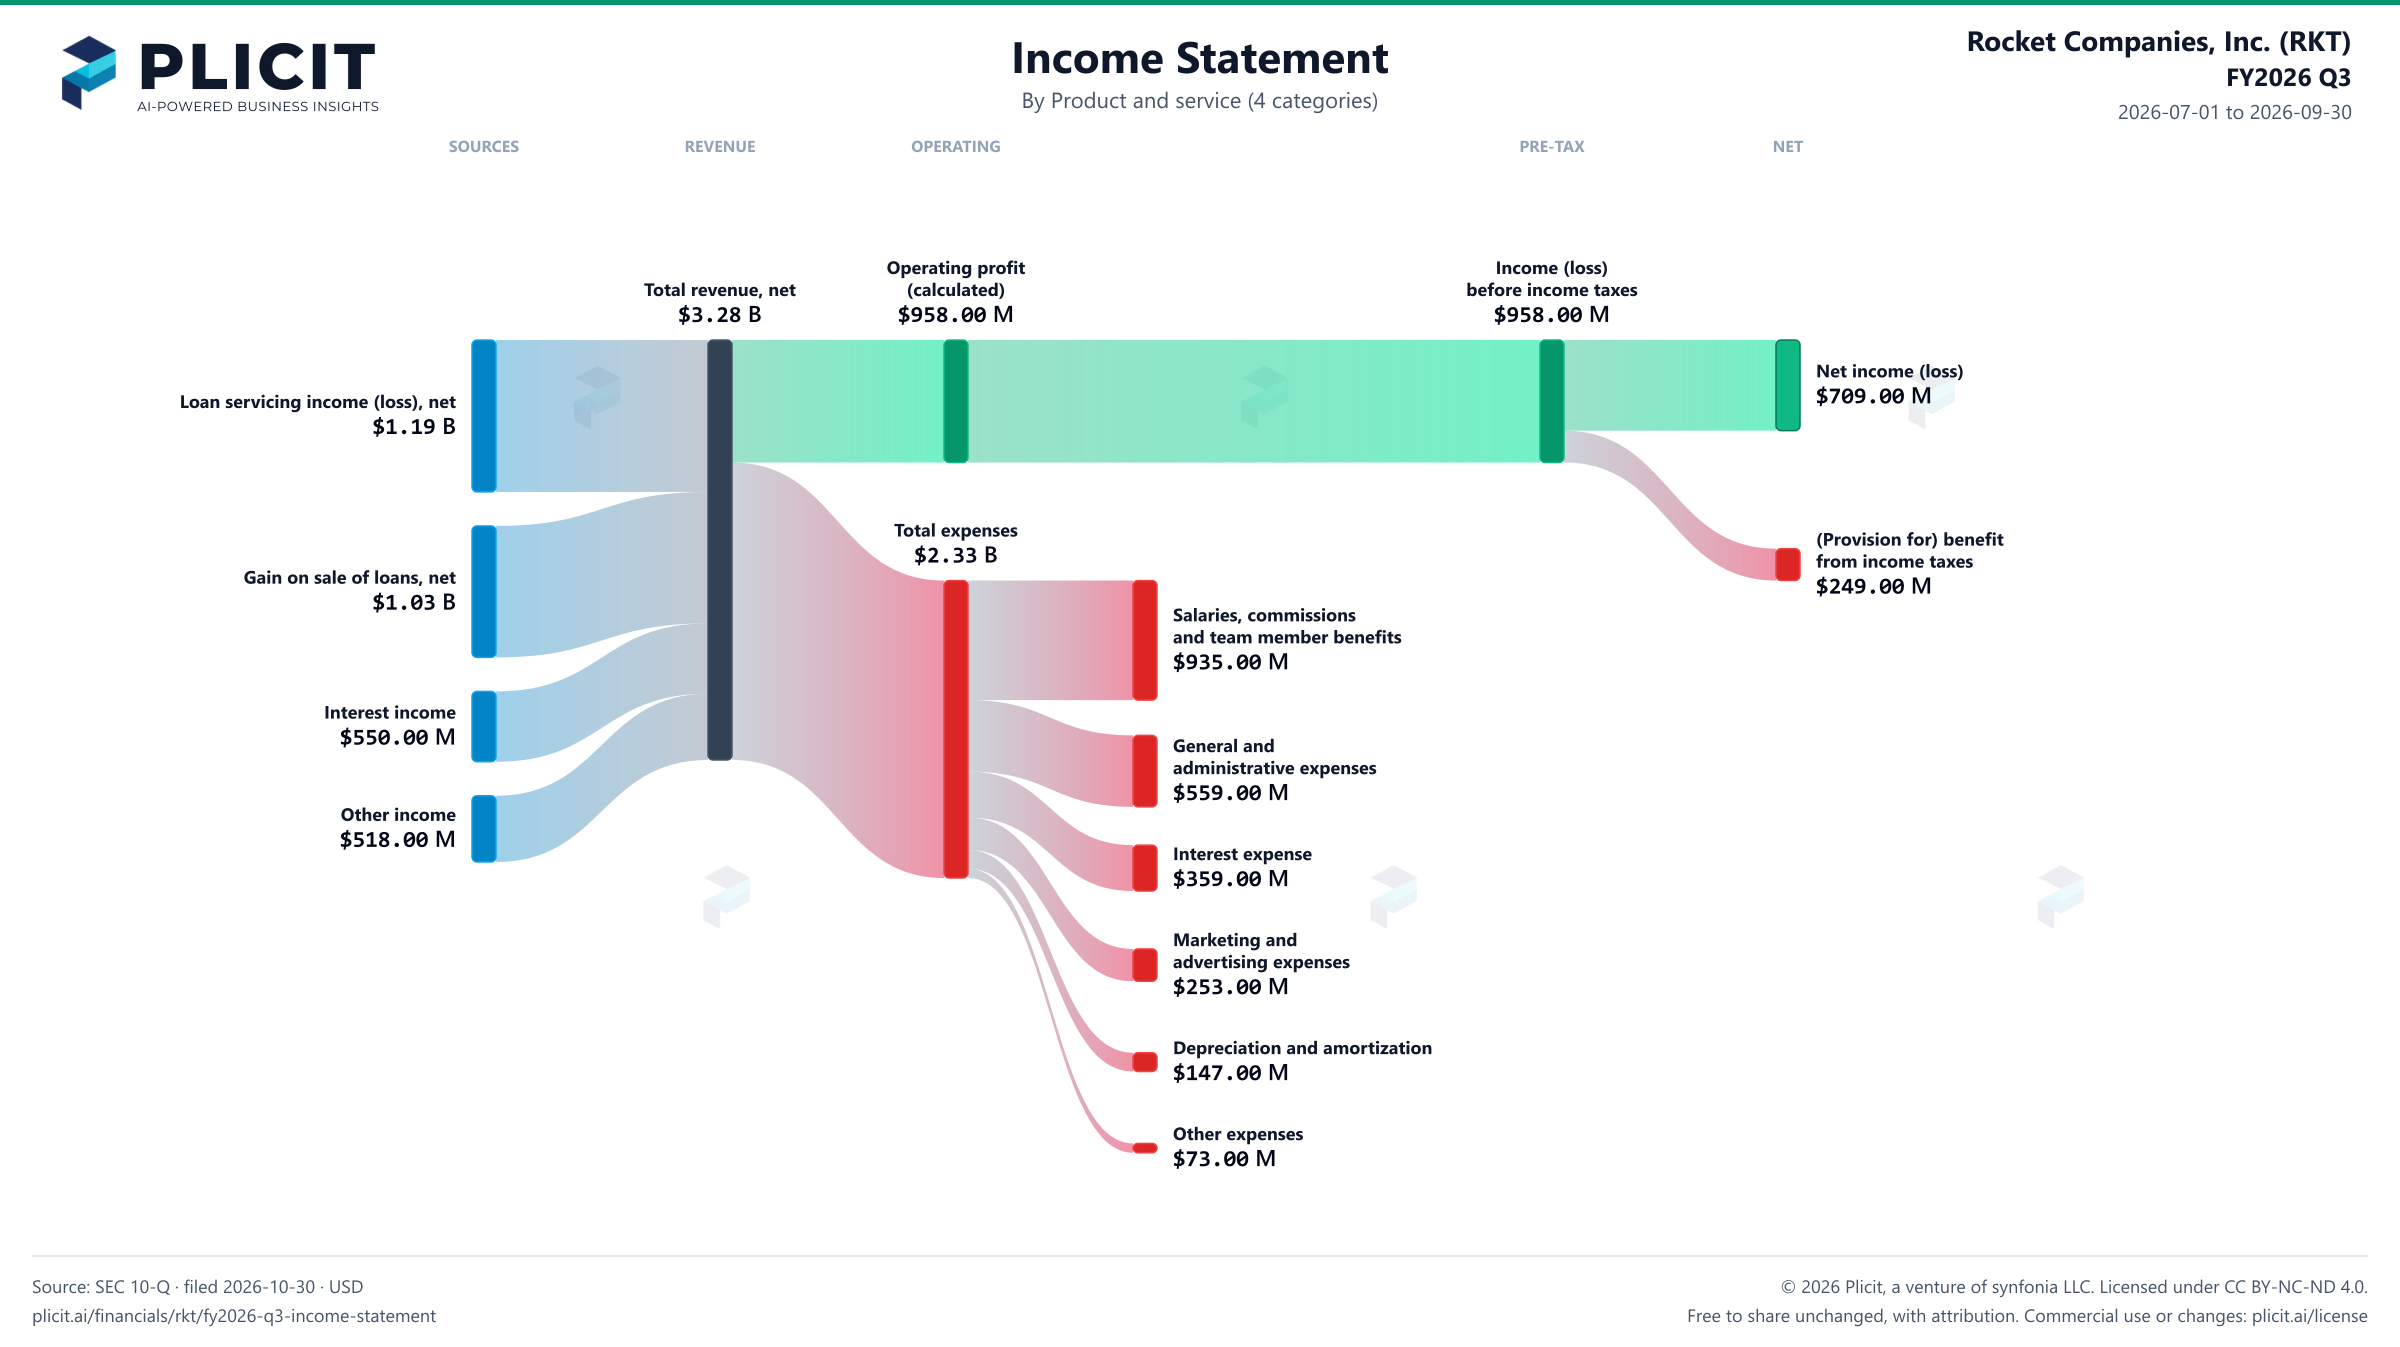
Half of Rocket's servicing income jump is a fair-value mark, not fees
Rocket's revenue reached $3.28 B this quarter, up 94% from $1,695.00 M a year earlier, and the biggest engine was loan servicing. That line swung from a $67.00 M loss to $1.19 B, so it now brings in more than any other part of sales. Together, servicing and gain on sale make up 67% of the quarter's revenue. Interest income and other income came in well behind. Much of that top line is not cash, and the next paragraphs show what sits inside it.
Why did it swing? The filing names servicing fees and a fair-value change. Servicing fee income rose $619 million with a bigger portfolio, and the change in fair value of servicing rights rose $636 million, which is a mark on paper, not cash. Put together, about half of the jump is an accounting valuation and about half is fees. The fee growth is real money, but the valuation part depends on the assumptions behind it.
The second line matters as well. Gain on sale of loans, net, is 71% fair value of servicing rights created on new loans, which means most of it is a valuation, not a sale price. The same line was $386.00 M a year earlier, so the mark is up 88%. Servicing income is partly a bet on how long those valuations hold. What would servicing income look like if those valuations were reset at today's market rates?