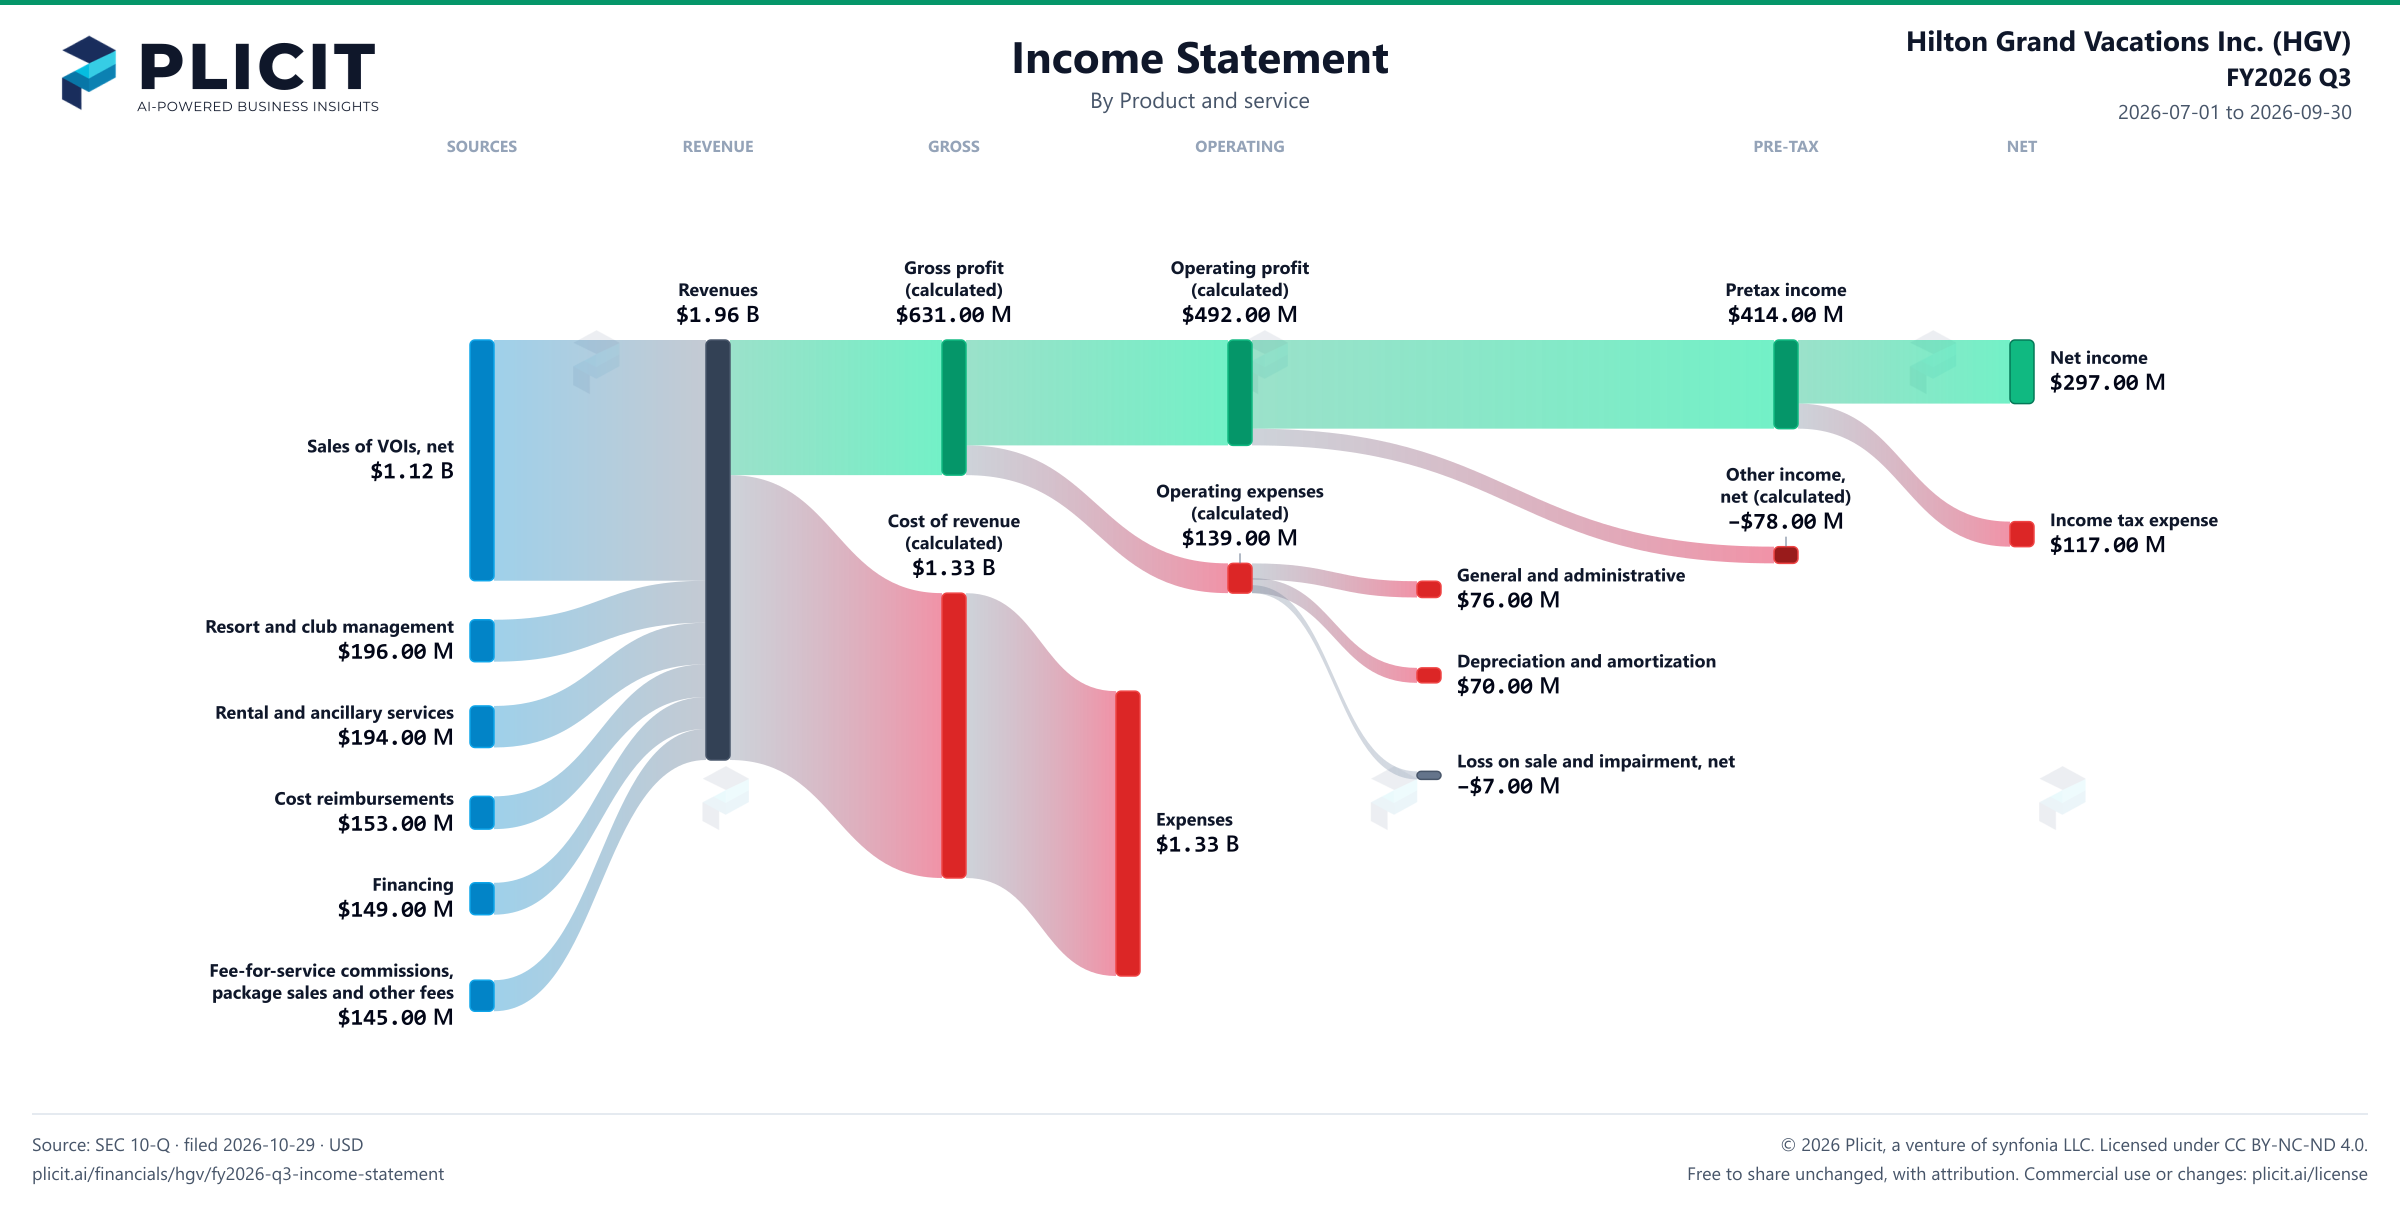
Profit rose nearly tenfold, helped by a lower tax rate
Net income in the third quarter was $297.00 M, against $30.00 M a year earlier. Revenue rose 51% to $1.96 B, and operating income rose to $492.00 M from $121.00 M. Most of the sales increase is timing: the filing puts $536.00 M of net construction recognition this quarter against a $99.00 M deferral a year earlier. Sales recognized from construction completion show up in profit when the revenue is booked, not when a buyer's cash arrives. The cash flow page shows the same quarter from the cash side.
A lower tax rate added to it: the statement implies 28.3% this quarter, against 33.3% a year earlier. The notes print a different prior-year figure, about 38%, which the statement's own numbers do not reproduce. Diluted earnings per share rose 1221%, while profit rose 1064%. The average diluted share count fell 13%, from 90.1 million to 78.6 million shares. The statement and the notes disagree on last year's tax rate, so that part of the profit story needs its own check.
Interest is less of a squeeze: operating income covered interest 6.3 times this quarter, against 1.5 times a year earlier. The interest line itself barely moved, at $78.00 M against $79.00 M, so the change came from the profit side. Operating cash was $87.00 M for the quarter, so most of the $297.00 M profit is still on paper. A lender reading this page should keep both numbers in view. How much of the $297.00 M would survive if sales counted only when the cash came in?