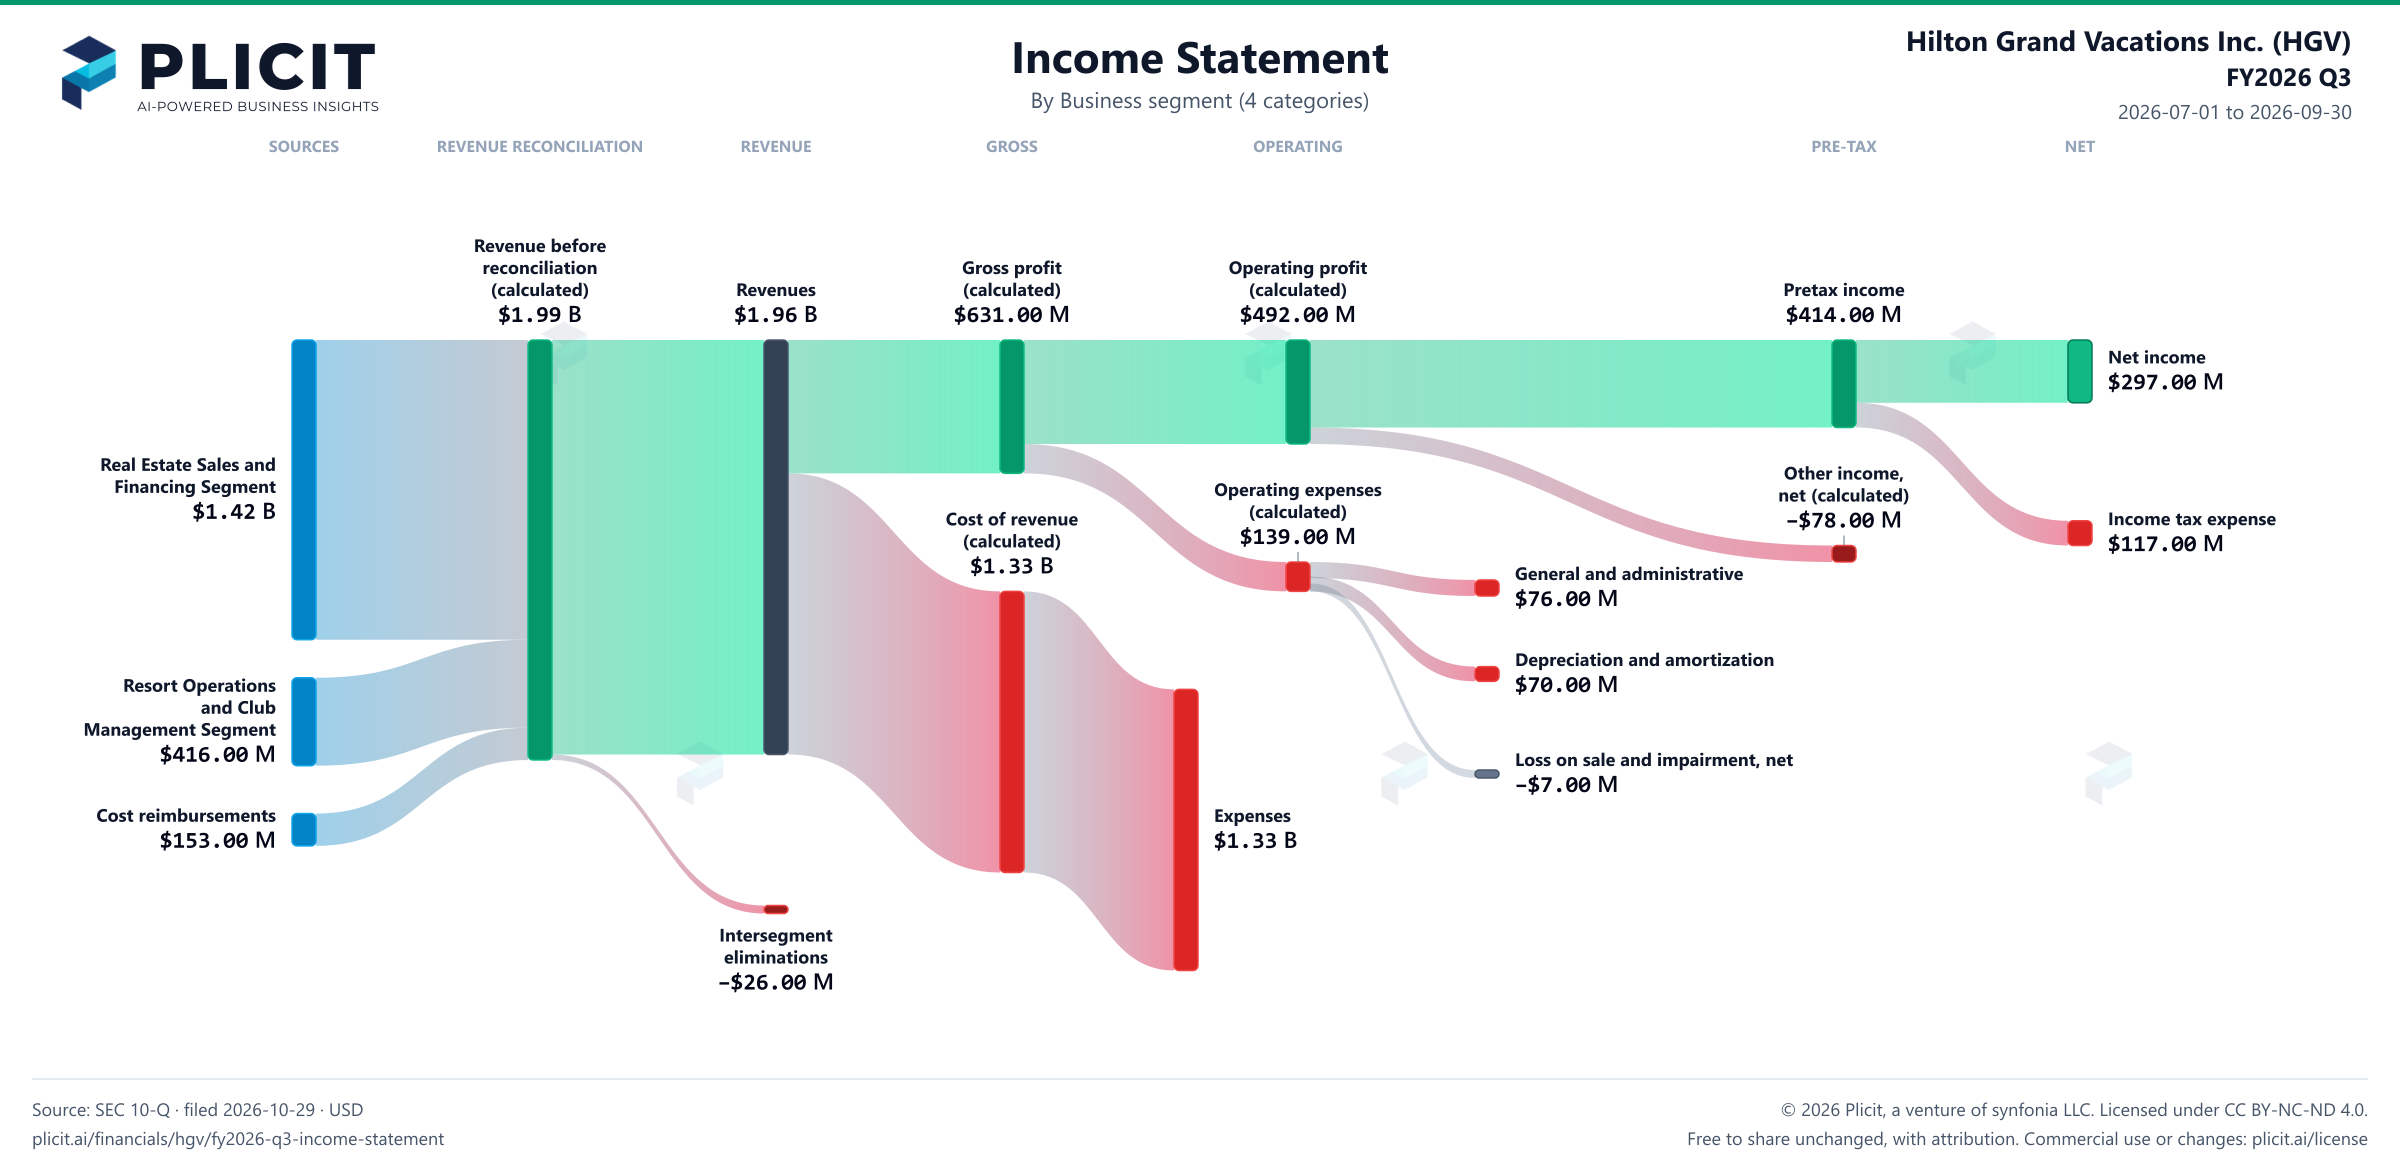
Most of the revenue jump is a construction timing swing
Real estate sales and financing is the engine, bringing in $1.42 B of the company's $1.96 B in revenue this quarter. Its revenue rose 79.7% to $1.42 B, while total revenue grew 50.8%. The filing's own explanation is timing: a net construction recognition of $536.00 M in 2026, compared with a deferral of $99.00 M in 2025. Sales of VOIs under construction are deferred until construction is complete, so a finished project lands all at once in revenue. The filing does not separate how much of this is timing from how much is new demand, so the quarter is a timing story first.
Margin moved the same way, with real estate profit margin at 40.5% against 21.3% a year earlier. The company's notes say margins expand in the period when earlier deferred sales are recognized on construction completion. A separate change in reserve estimates added to the same line: the filing says a $55.00 M cut to the originated allowance lifted Sales of VOIs, net. Together, the timing and the reserve change explain much of why the segment's margin looks so much better.
The resort side, which runs the properties and clubs, moved from $406.00 M to $416.00 M. The company's loans run for a weighted average of 9.0 years, so the cash from those sales arrives slowly. Resort operations are the slower, steadier business, and the segment table shows it growing at a fraction of the real estate pace. If this quarter's sales were recorded only as cash came in, how much of the $297.00 M profit would remain?