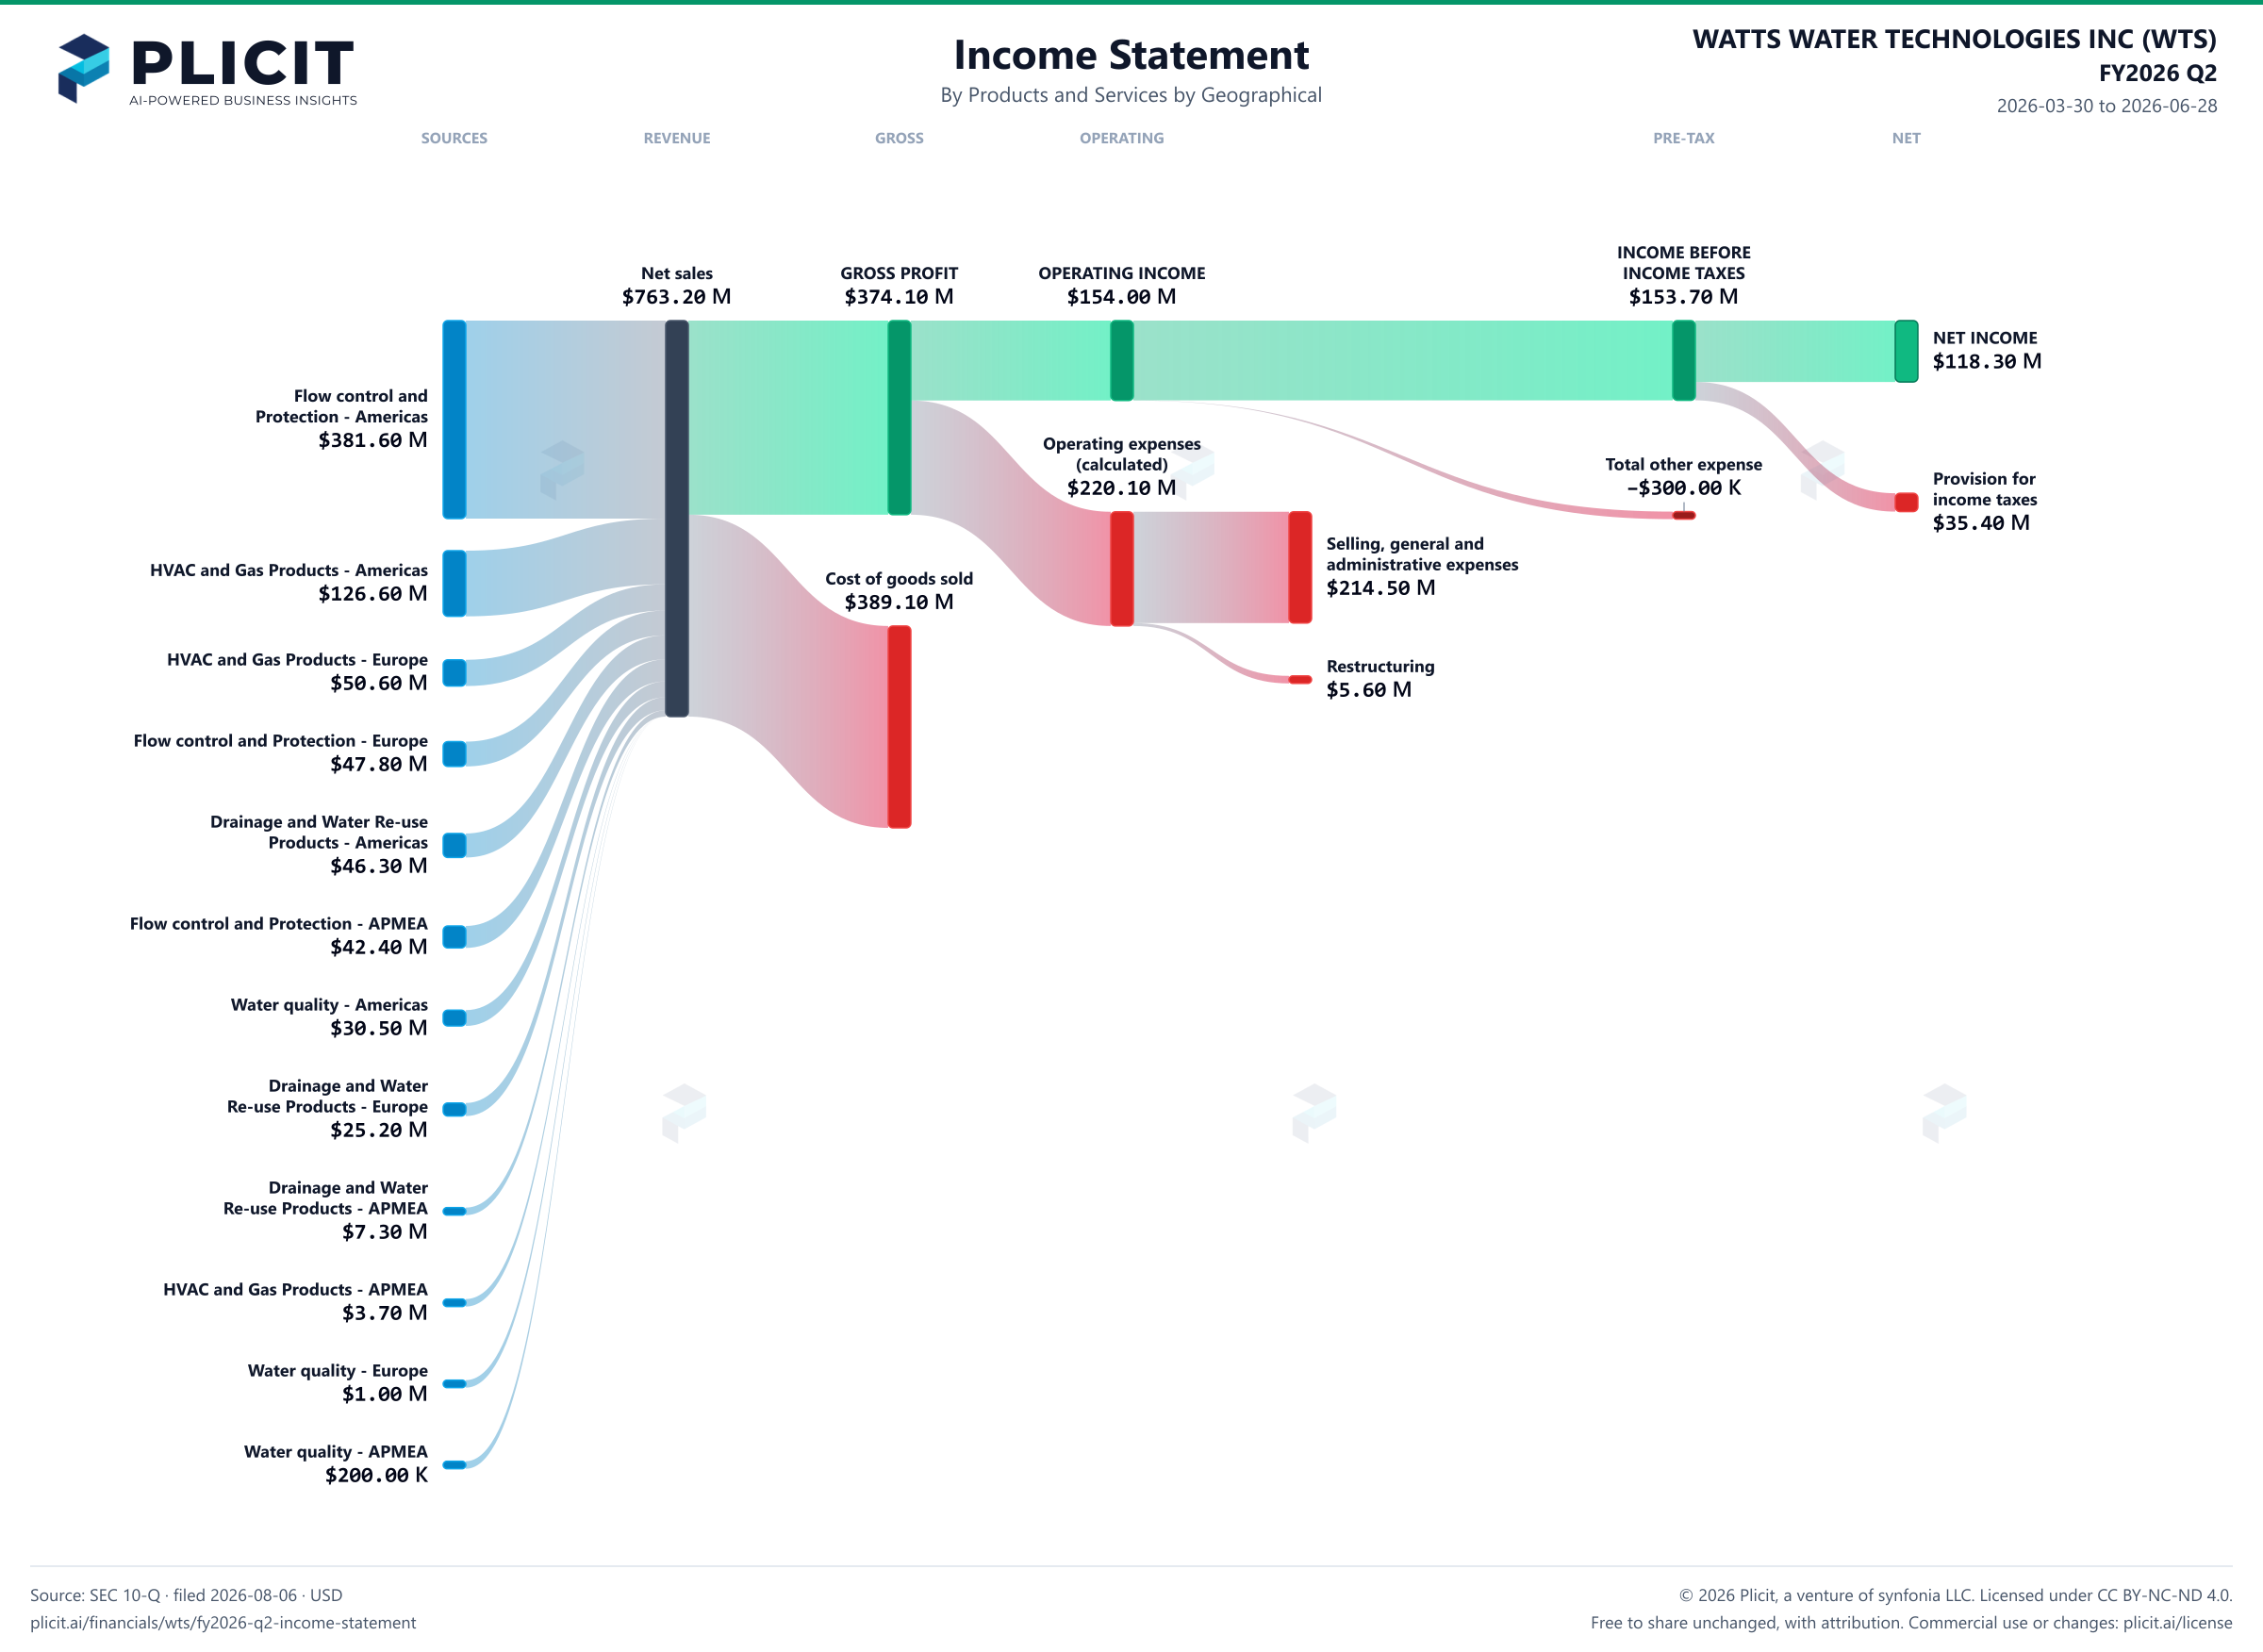
Profit rose 17% on 19% sales growth, and the margin slipped
Watts Water sold more and kept less. Revenue rose 19% to $763.20 M, and net income rose 17% to $118.30 M. But the gross margin slipped from 50.6% to 49.0%, and operating income of $154.00 M was 20% of sales, down from 21% a year earlier. Net income grew more slowly than sales, so each dollar of sales now carries slightly less profit. That is the gap that matters to a reader. The filing blames the slip on acquisitions: "Gross margin declined primarily due to the dilutive impact of acquisitions".
Part of the profit growth is a tax story. Before tax, profit rose 14%, to $153.70 M from $134.70 M. The tax bill was $35.40 M, a 23% rate against 25% last year. At last year's rate, the bill would have been $38.57 M, so the lower rate is worth $3.17 M this quarter. Had the rate stayed at last year's level, net income would have grown about 14%, not 17%. That gap comes from tax, not from selling more.
Spending on the future held roughly steady as a share of sales. Research came to 2.7% of sales, the same as a year earlier, and property and equipment spending fell to 1.5% from 1.6%. Selling and overhead costs took 28.1% of sales, down from 29.1%, and that drop offsets part of the gross margin slip. In dollars, selling and overhead costs grew 14.6%, slower than sales. Will overhead keep shrinking as a share of sales, or did a lower tax rate and a leaner overhead line carry this quarter's profit?