Americas carries Watts Water, and acquired sales fill 29% of the rise
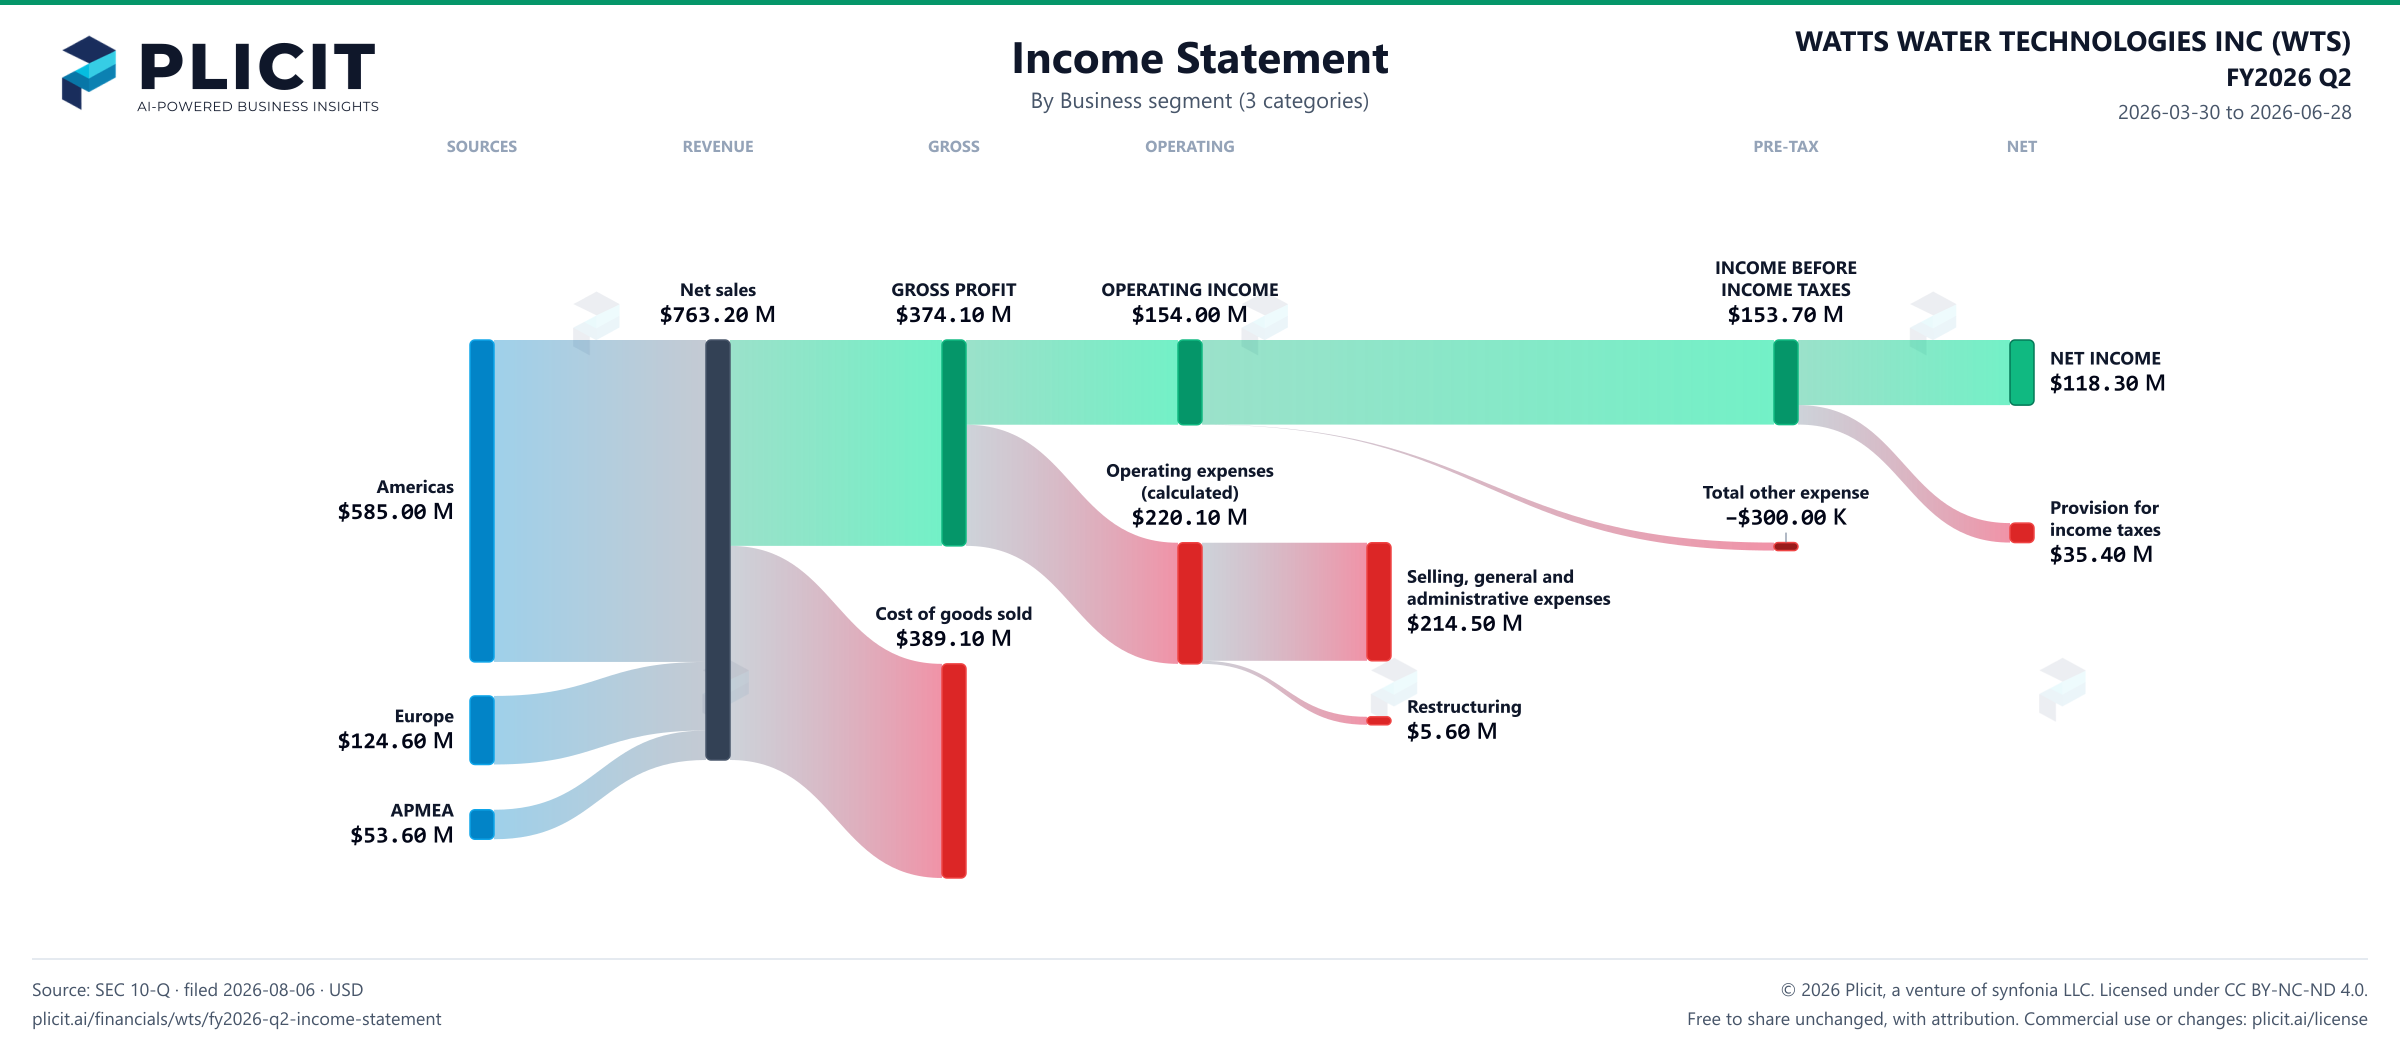
Americas carries the quarter, and 29% of the company's sales rise was bought. The segment brought in $585.00 M of $763.20 M, 77% of sales. Total sales rose 18.6%, but the filing splits that $119.50 M rise into organic growth of $78.70 M, $6.50 M of currency and $34.30 M from acquisitions. Americas alone took $28.40 M from deals completed in 2025. Strip out the purchases and currency, and growth is 12.2%. Europe and APMEA together added $33.00 M, far less than Americas.
Americas also makes the money. Its $150.10 M of segment earnings is 85% of the $177.30 M the three businesses earned together. Europe kept 13% of its sales as segment earnings, and APMEA kept 20%. Between the segments and the consolidated line, Watts Water gave up $23.30 M to corporate costs and special items. The filing puts the corporate piece at a $17.30 M operating loss, with $6.00 M of special items on top. Americas earned more than the other two segments combined.
Restructuring sits in the same two places. The filing books a net charge of $5.60 M, up from $3.40 M a year earlier, which it says primarily related to severance for cost savings in Americas and Europe. The gross margin slipped too, and the filing blames the dilutive impact of acquisitions. Americas' 26% margin is the number to watch, because it carries the company. Will the bought sales earn what the old ones did, or will the gross margin keep sliding?