DaVita's fastest-growing business swung to an $18.64 M quarterly loss
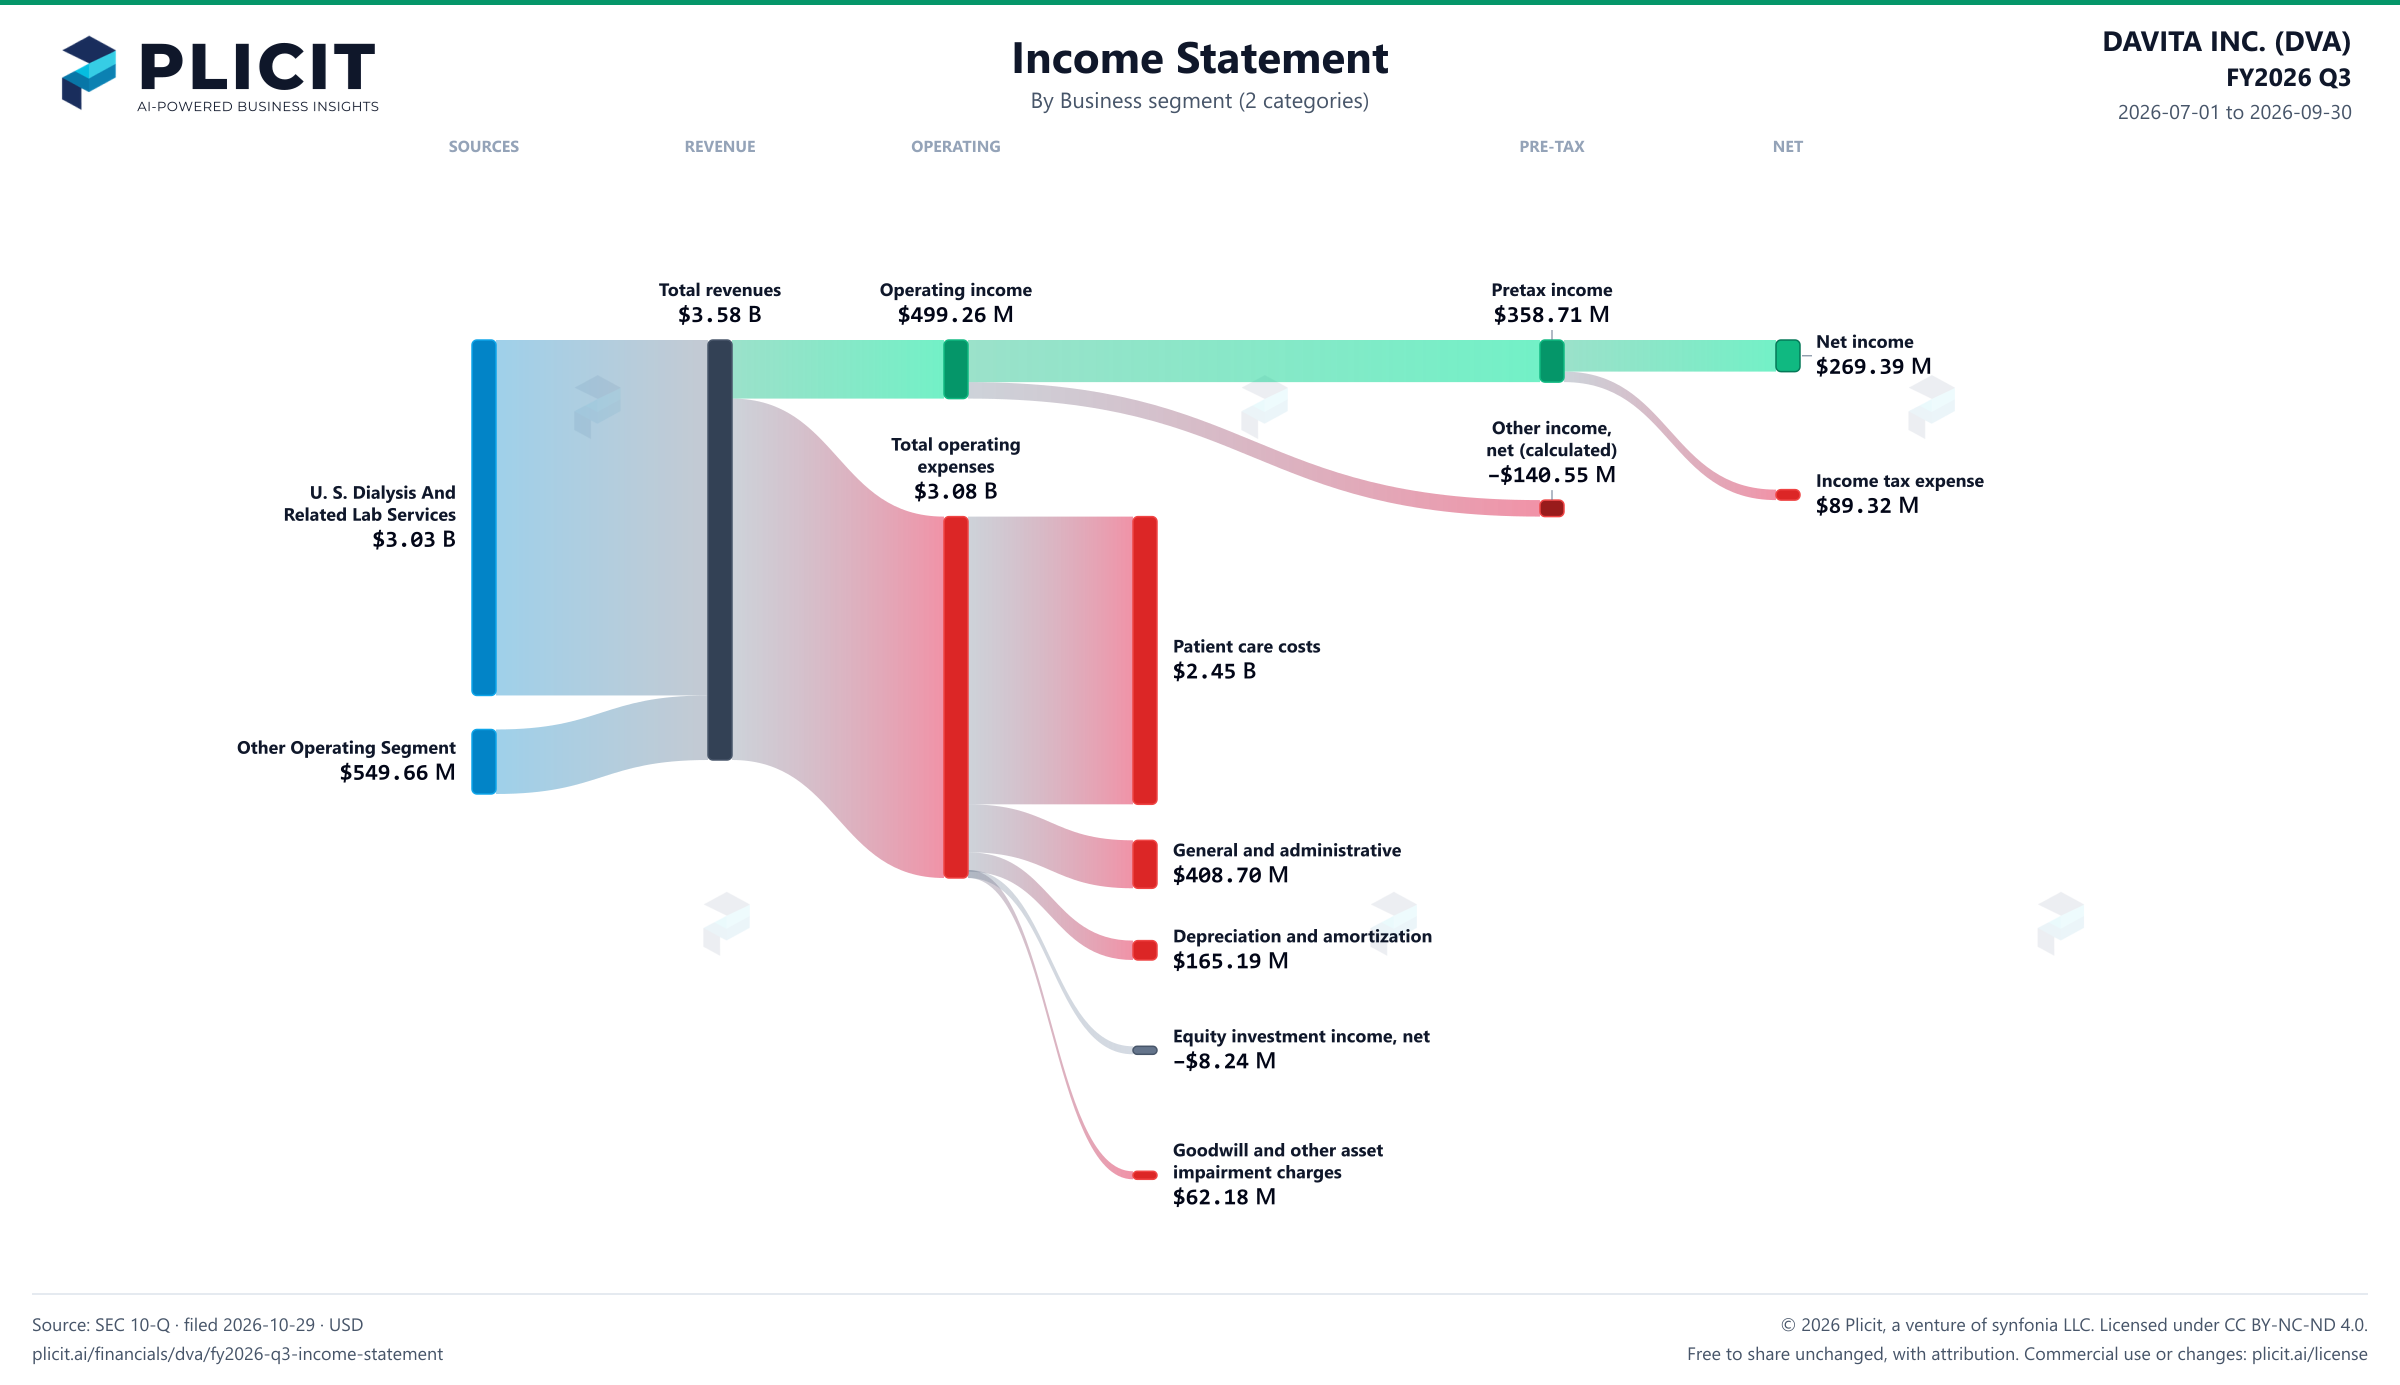
DaVita's smaller business line grew fastest and lost money. Its other operating segments lifted sales 22% to $549.66 M, yet posted an $18.64 M operating loss against a $1.22 M profit a year earlier. These segments are mainly integrated kidney care and the international clinics. The culprit is the $62.18 M write-down of the business in China. Strip it out and management's adjusted operating income for these businesses was $44 million. So the loss stems from the charge, but that charge is a warning about what the expansion abroad is worth.
Why did the core not offset it? U.S. dialysis, 85% of sales, grew just 2.0% and earned $544.18 M of operating income, against $530.11 M a year earlier. That is a margin of 18%, steady but not spectacular. Together the segments earned $525.54 M before head-office costs, down from $531.33 M. Their blended margin slipped 0.8 points, to 14.7%. Head-office costs and other items then trimmed the total to $499.26 M of operating income. The growth engine, in other words, is the business that just took the write-down.
For investors the split is a warning. Dialysis grows slowly and profitably; the faster-growing segments are where DaVita is placing its bets, and they are where value just evaporated. Management blames adverse reimbursement rate changes in non-renal hospital services in China, and the goodwill note says the unit remains at risk. Watch the adjusted operating income of the international clinics and whether these segments can turn growth into profit without further write-downs. If these segments keep growing fast while losing money on paper, are they building value or burning it?