Side businesses, 15% of DaVita's sales, delivered 61% of its growth
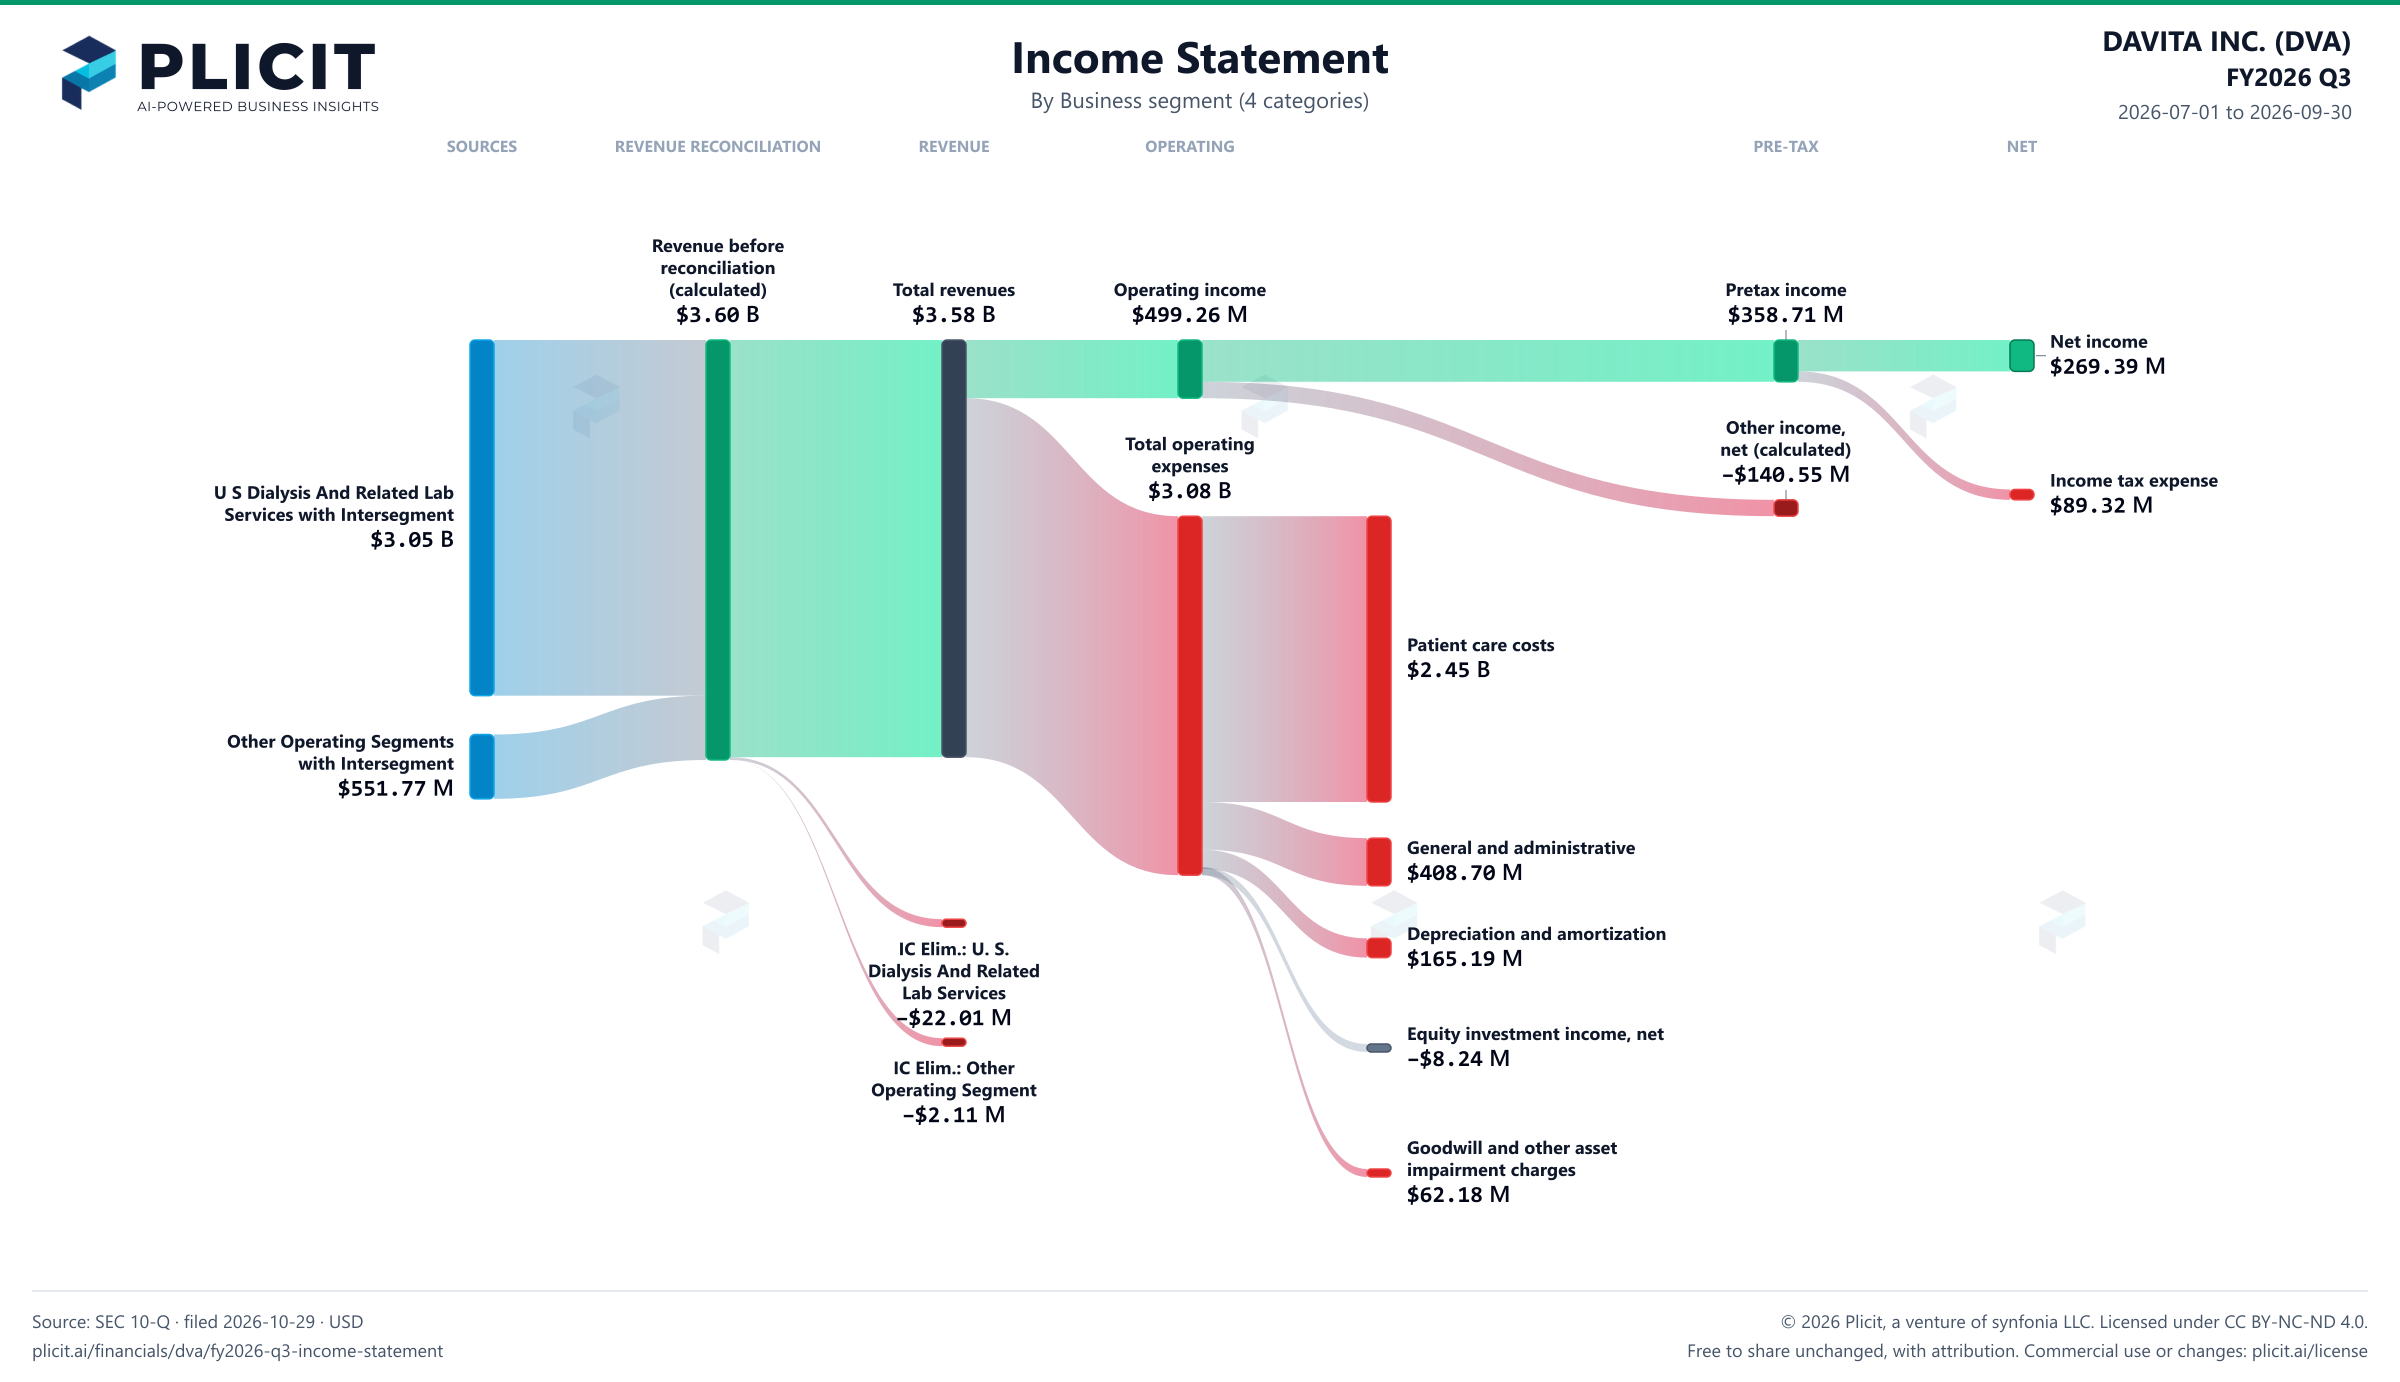
Strip out dialysis and DaVita's growth story looks very different. Its other operating segments, 15% of sales, supplied 61% of the $157.90 M rise in revenue from a year earlier. Counting sales to the rest of the group, they grew 21% to $551.77 M, while U.S. dialysis grew just 2.4%. Within those segments, revenue from sources other than patient care jumped to $163.01 M from $115.86 M. Yet the same segments posted an $18.64 M operating loss, dragged down by the $62.18 M write-down in China. Growth, in other words, arrived where the profits did not.
Why does dialysis sell inside its own group? U.S. dialysis booked $22.01 M of revenue from other DaVita segments this quarter, up from $11.93 M, and the group eliminates $24.12 M of such internal sales in total. The filing does not say which units were buying. What it does show is where the acquisition money sits: U.S. dialysis carries 87% of the $7.55 B of goodwill, while the other segments hold the China unit whose goodwill was just cut by $57.10 M. The segments that grow fastest are the ones carrying the write-down risk.
For investors, the filing describes a slow core and a fast, unprofitable fringe. The dialysis core grows slowly and pays the bills; the other segments grow fast but just lost money on paper. Management's own adjusted measure puts these segments' operating income at $44 million this quarter, down from $57 million in the quarter before. So even before the China charge, their profit shrank from the prior quarter. Watch whether integrated kidney care and the international clinics can turn their sales growth into steady profit. If the fastest-growing part of DaVita cannot earn money, what exactly is the growth worth?