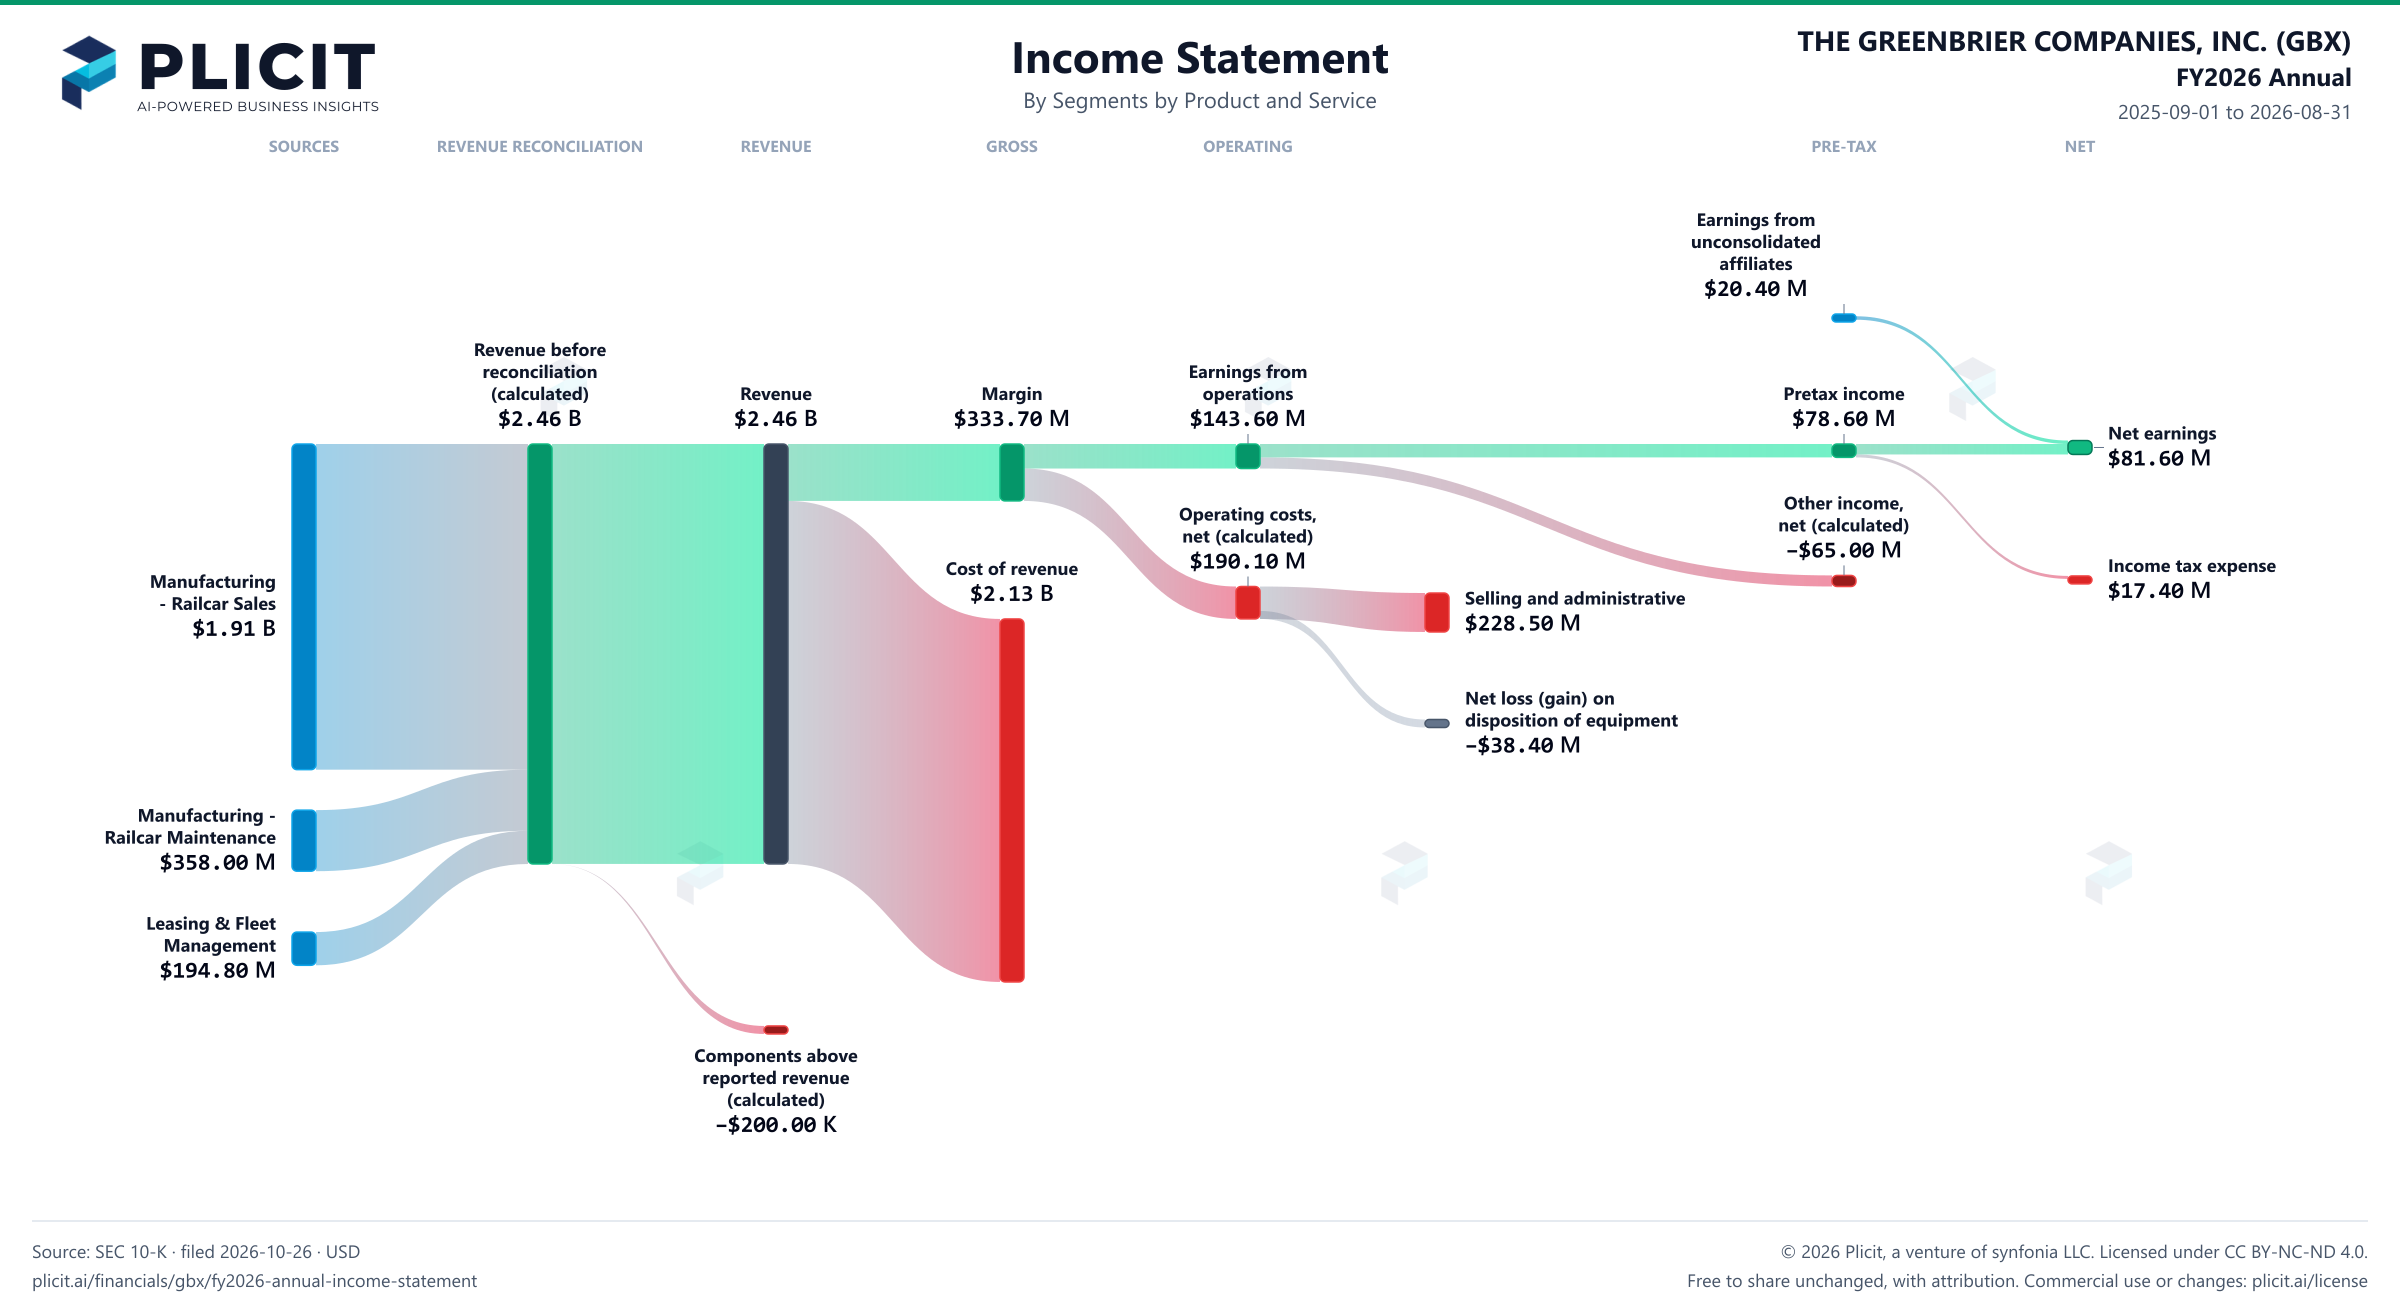
Greenbrier profit fell 61% as railcar deliveries dropped 31.9%
Greenbrier delivered 13,900 railcars in the year to August 31, 2026, down from 20,400, and the income statement shows the cost of that slide. Sales fell 24% to $2.46 B, gross margin shrank to 13.6% from 18.7%, and net earnings attributable to shareholders fell 61% to $79.0 million. Management blames "a 31.9% decrease in deliveries" and "an unfavorable change in railcar manufacturing product mix." Railcar sales alone lost $753.80 M of revenue. When a factory business loses 31.9% of its deliveries, its fixed costs eat the margin.
Below the factory floor, the bills kept coming. Interest and foreign exchange took $65.00 M, 45% of the $143.60 M operating profit. Joint ventures and affiliates, including a railcar maker in Brazil, added $20.40 M, or 26% of profit before tax. Fleet sales helped too: the net gain on disposition of equipment rose to $38.4 million from $15.9 million on higher sales of assets from the lease fleet. Selling and administrative costs fell $34.8 million, mostly on "lower incentive compensation," yet still rose to 9.3% of sales from 8.1%.
For investors, the year shows how much this business depends on volume. The new railcar backlog fell to 14,000 units from 16,600, valued at $2,100 million against $2,200 million, and management says about $1.0 billion of it is scheduled for delivery in 2027. That is far below the $2.46 B of sales just booked, before any new orders, maintenance or leasing. Diluted earnings came to $2.49 a share. If deliveries keep falling, where will profit come from next year: the factories, the fleet, or more sales of fleet railcars?