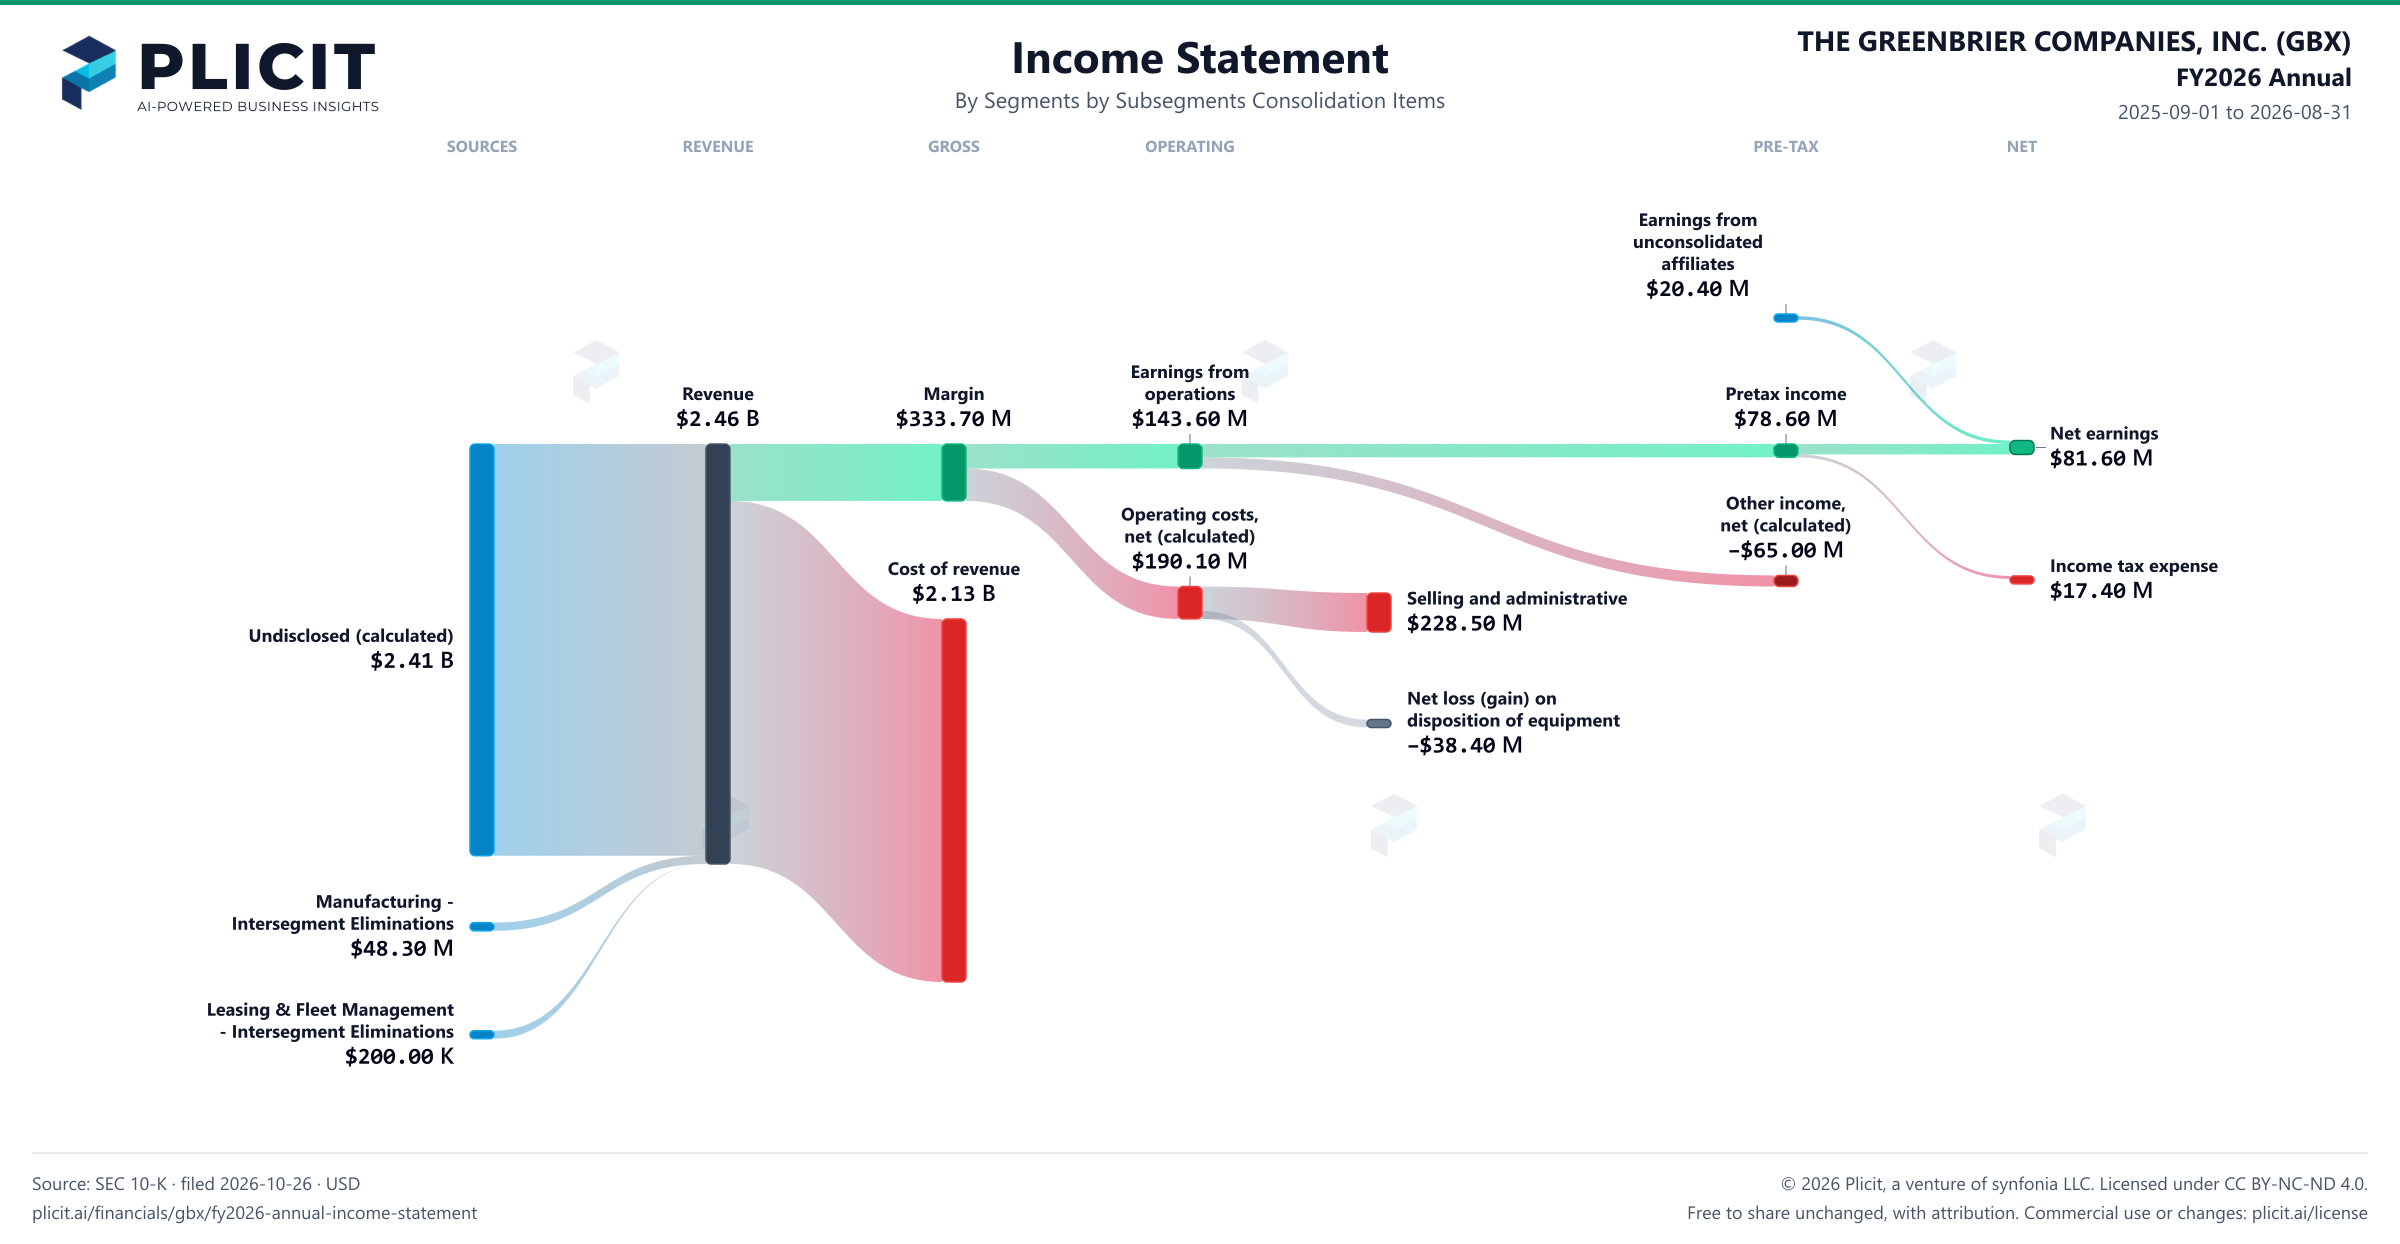
Greenbrier factories cut sales to their own lease fleet by 51%
Greenbrier factories sold just $48.30 M of goods and services to the company leasing arm in the year to August 31, 2026, down 51% from $98.90 M. The year before last, the figure was $237.00 M. These internal sales vanish from the consolidated revenue of $2.46 B, so they never show in the headline, but they reveal how much the lease fleet leans on the factories. The margin consolidation strips out of them fell to $0.5 million from $14.2 million.
Why would internal sales fall while Leasing raised its capital spending to $174.8 million from $140.5 million? One clue is accounting, not railcars. Greenbrier changed the measurement basis for allocating revenue and expenses associated with syndication activity between its segments from September 1, 2025, and "Prior period segment results have been recast." Syndication here is the sale of new railcars with "leases attached" to them. A change in how that work is split between the factories and the fleet can move internal sales without a single railcar moving differently.
For investors, this view is small in dollars but large in meaning. With the eliminated margin down to $0.5 million, almost no profit now rides on factory sales to the sister fleet, while that fleet keeps growing through its own spending. Recast segments make year-on-year comparisons of the businesses harder to trust. Watch the next filings for a steady split. If the fleet no longer buys from the factories at a profit, which business is really earning the returns the company reports?