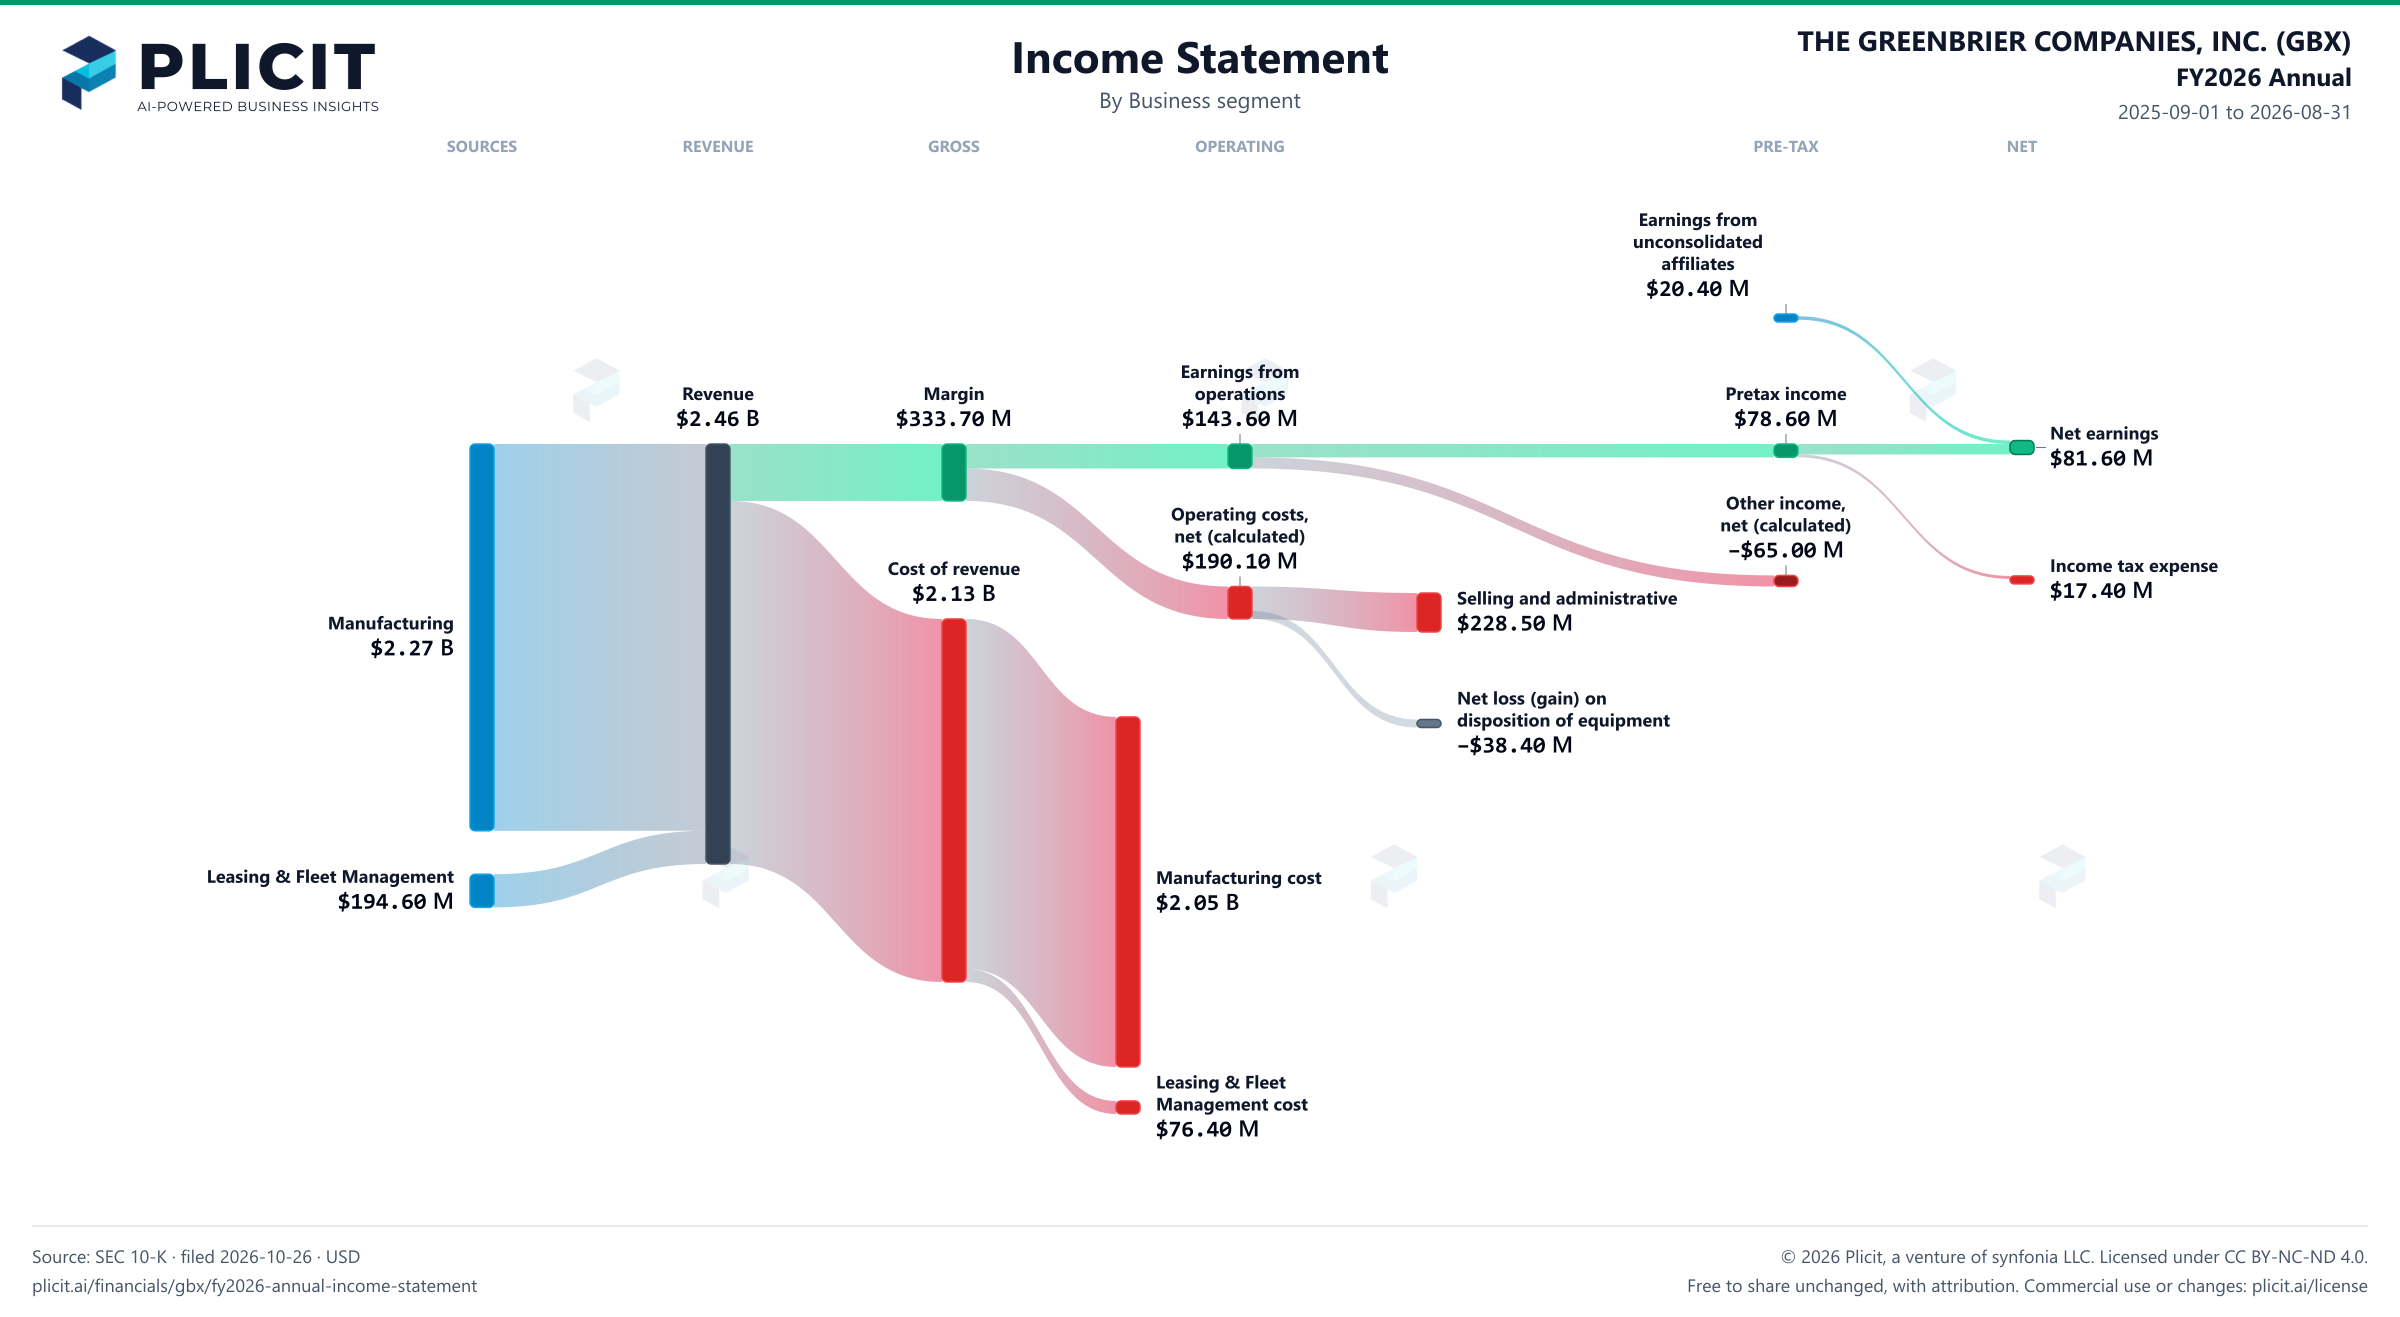
Greenbrier factories lost 68% of their profit as deliveries collapsed
Greenbrier railcar factories had a brutal year. Manufacturing revenue fell $780.4 million, or 25.6%, in the year to August 31, 2026, and its operating profit fell 68% to $120.80 M from $377.40 M. Management blames "a 31.9% decline in deliveries partially offset by a change in railcar manufacturing product mix." A business that still brings in 92% of sales now keeps only 5.3% of them as operating profit. The fixed costs of big plants do not shrink when the order book does.
Leasing & Fleet Management looks like the hero: it earned $139.10 M on $194.60 M of sales, a 71% margin, and supplied 54% of the operating income its businesses reported. But look at where that profit came from. Its revenue rose just $1.3 million, while segment earnings included a $42.1 million net gain on disposition of equipment, 30% of the $139.10 M. Gains from selling railcars are real money, yet they shrink the fleet that earns the rent. Greenbrier then put 63% of its capital spending into Leasing, refilling that fleet.
For shareholders, the split matters. Leasing leaned on selling fleet assets, and Manufacturing on volumes that are still falling: the new railcar backlog shrank to 14,000 units from 16,600. Head-office costs and other items outside the businesses then took $116.30 M off their combined profit. The segment figures also moved under a new yardstick, since "Prior period segment results have been recast." If the factories cannot refill their order book, how long can fleet sales keep propping up the profit line?