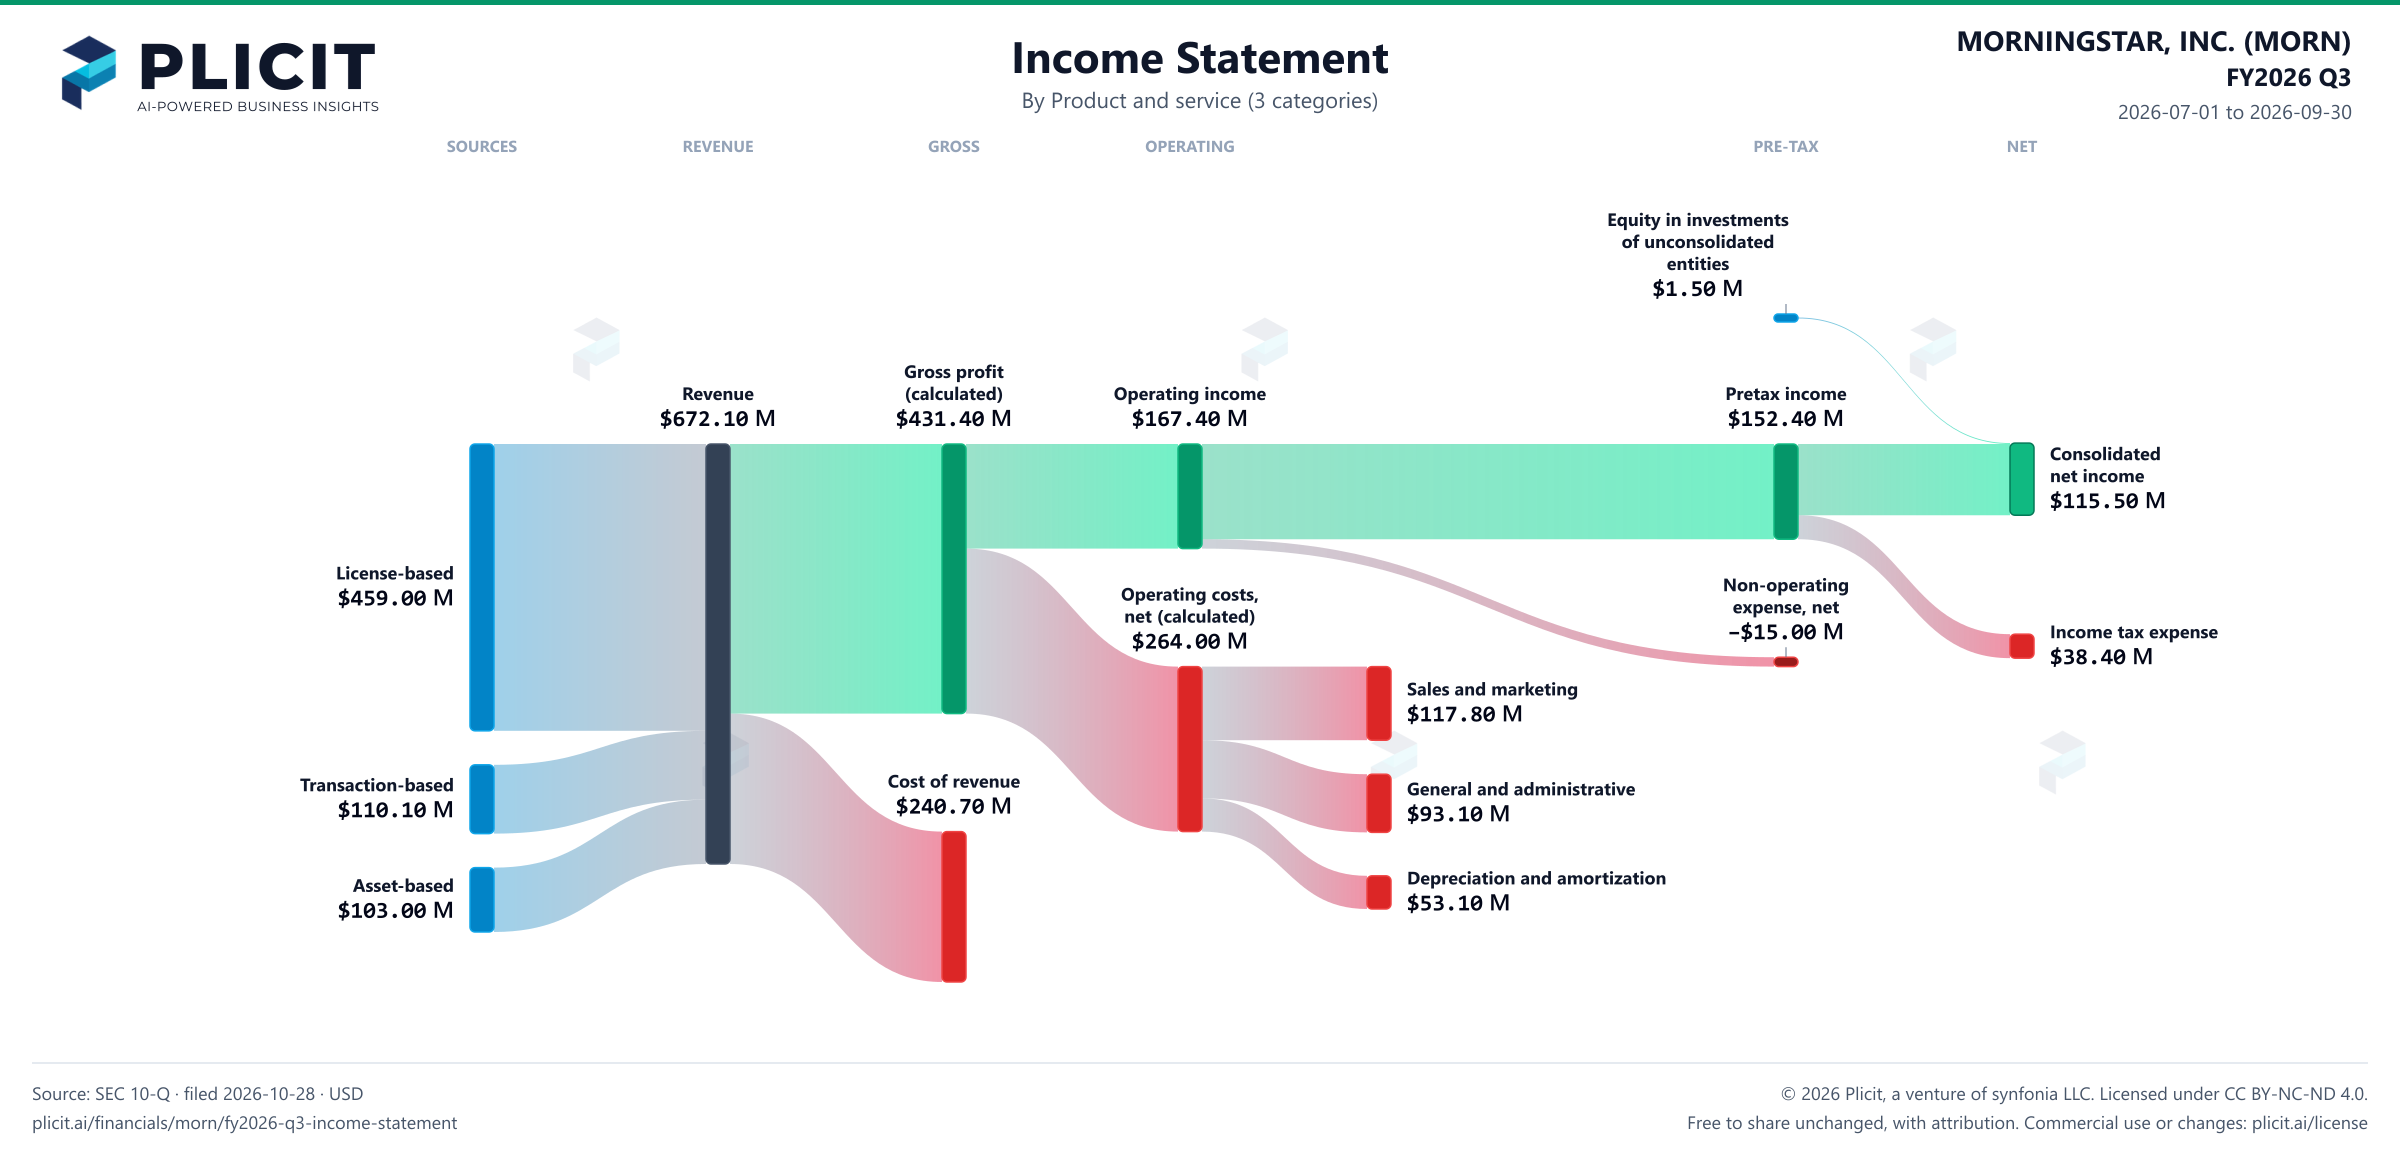
License sales are 68% of revenue, while asset-based fees grew fastest
License-based sales were $459.00 M this quarter, 68% of the total, and they supplied $24.00 M of the $54.70 M rise. Asset-based sales rose from $84.70 M to $103.00 M, faster than any other line, and their share climbed to 15%. Transaction-based sales grew 12.7% to $110.10 M. Total revenue reached $672.10 M, up 8.9% from $617.40 M a year earlier. Every line grew, and license added the most dollars. Nothing shrank, so the mix shift is a story of growth rather than decline.
The license line is the biggest base, and its growth is steady rather than explosive at 5.5% this quarter. Asset-based fees depend on assets under management, which is why this line can rise faster than the others. Transaction revenue is a smaller slice, but it grew 20.7% in the nine months, the fastest of the three. Asset-based revenue rose 16.7% over the same nine months, so the trend holds. Over the quarter the asset line rose 21.6%, against 5.5% for license, and that gap is the number to watch.
For an investor the mix matters: the more asset fees grow, the more revenue depends on market levels. License revenue is 68% of the total, so the company's health rests mostly on that line, and any slowdown there would show up quickly. Asset-based fees are already 15% of revenue, and they move with markets, so a sell-off would hit them first. A reader should watch whether the license line keeps its pace as asset fees move. Will license growth keep pace with asset-based fees, or will markets decide which line leads next year?