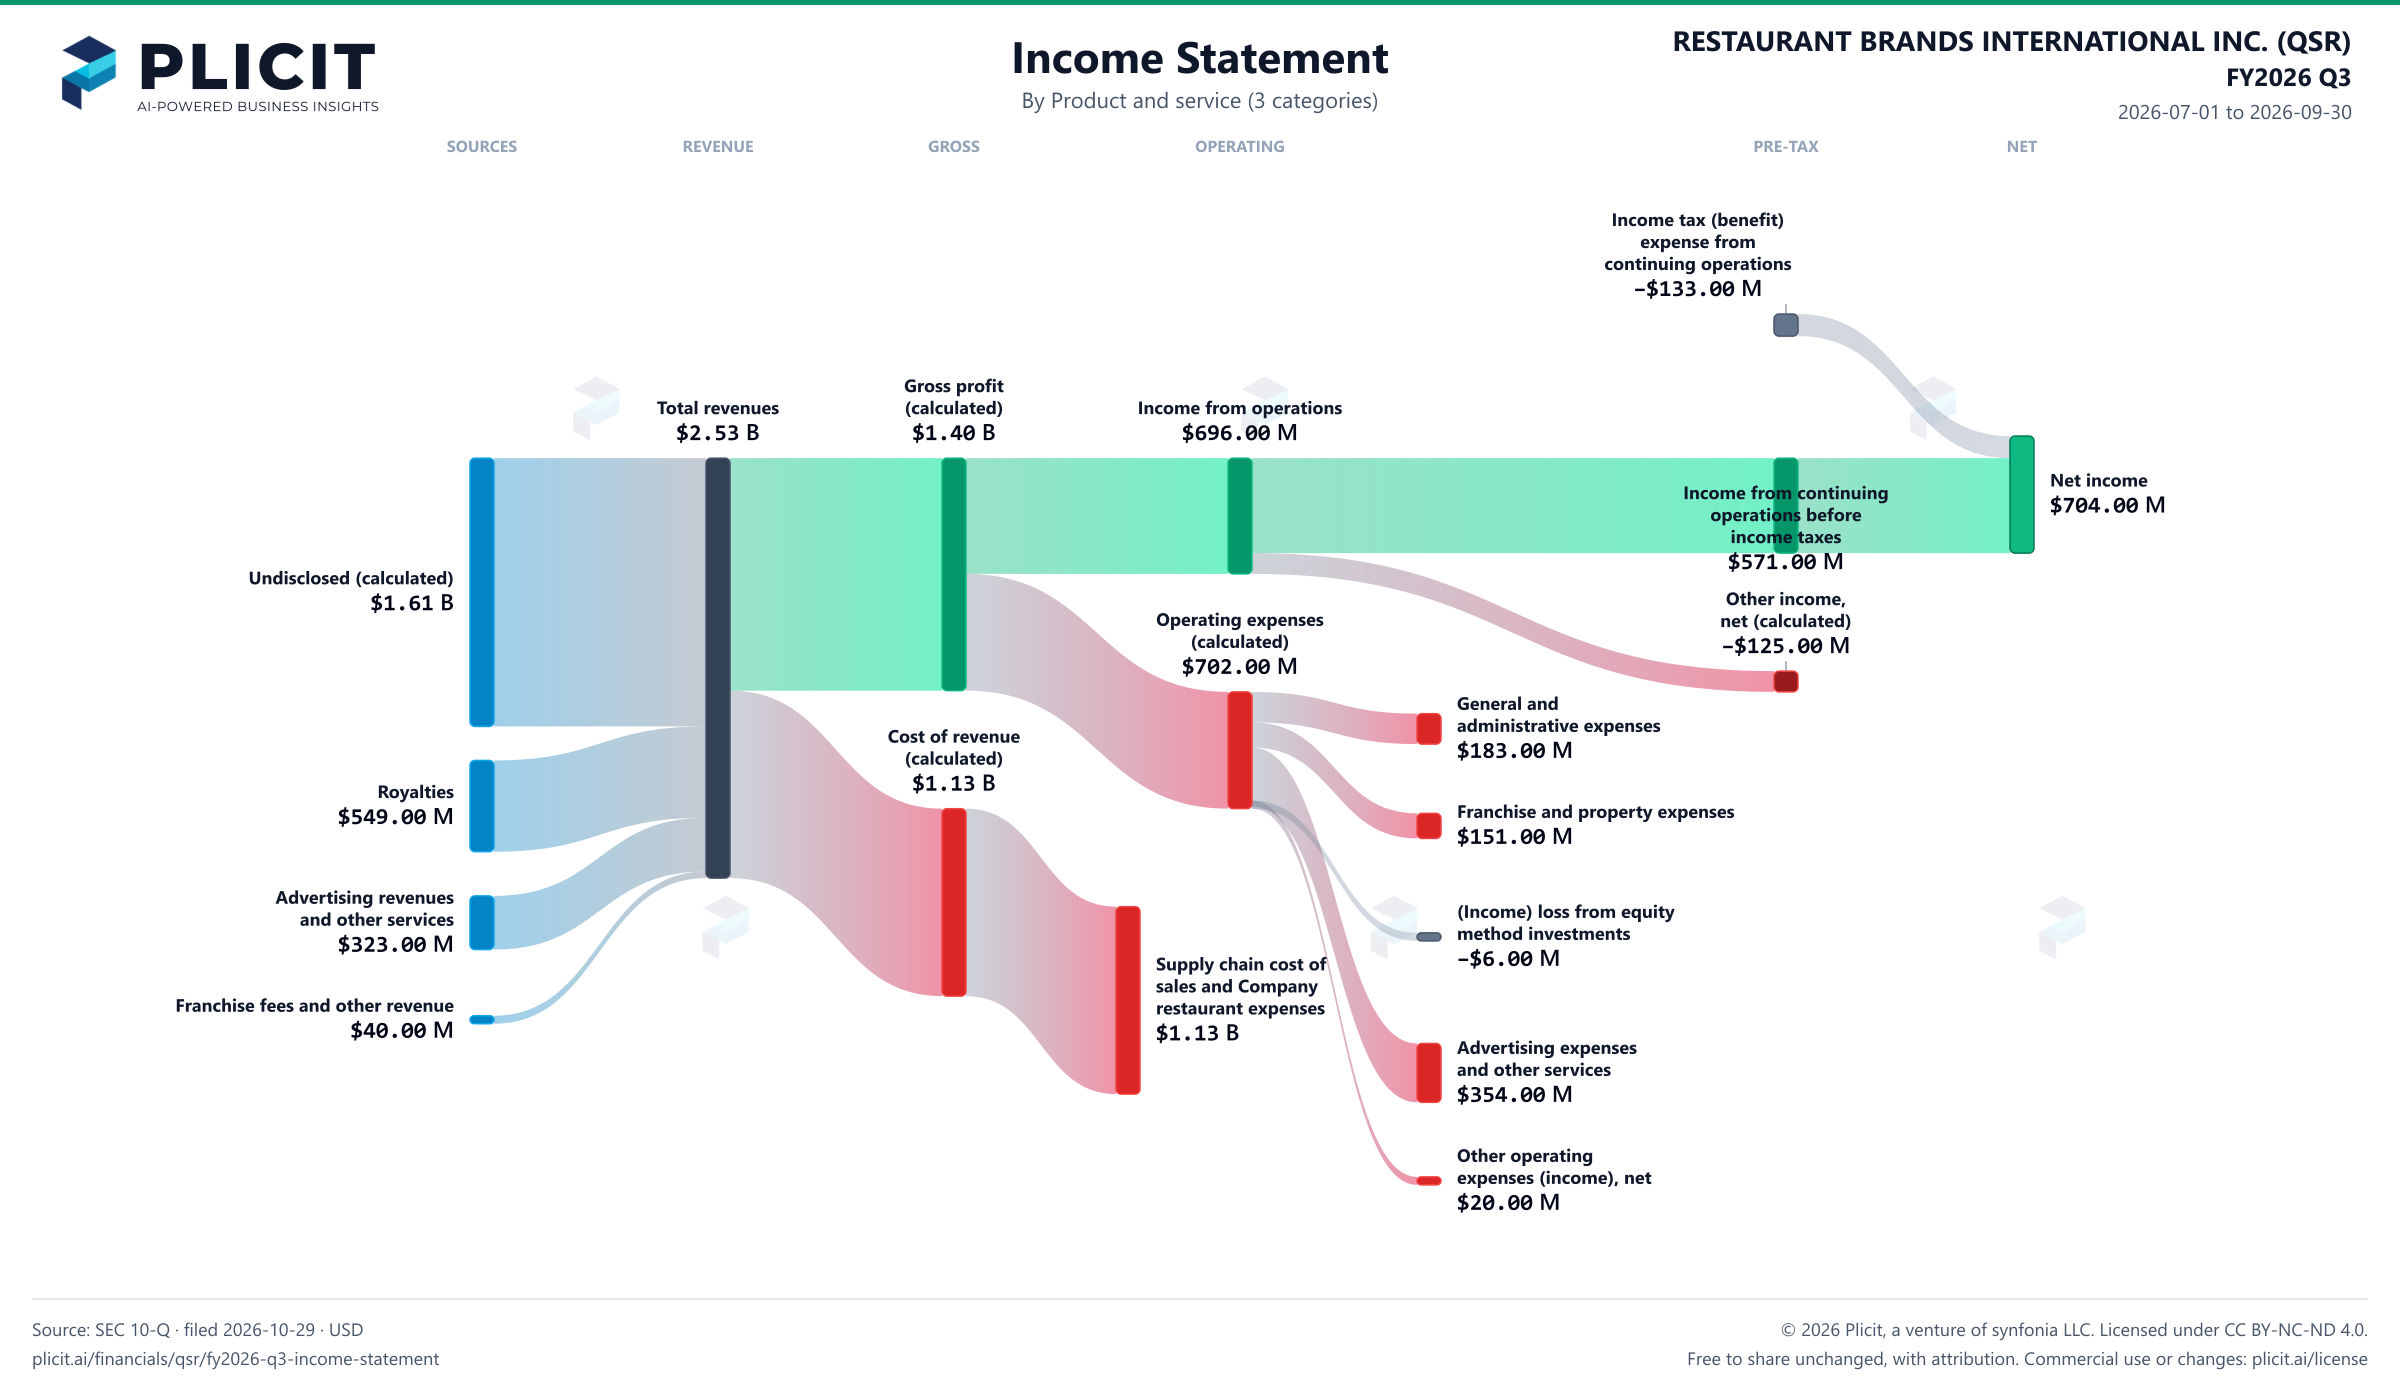
Royalties lead the product lines, and franchise fees are shrinking
Royalties is the biggest line at $549.00 M, or 22% of the company's $2.53 B of sales. The three lines the view shows add to only $912.00 M, so 64% of sales sit outside this cut. Royalties rose 5.6% from a year earlier, the fastest of the three, while franchise fees and other revenue slipped 2.4%. Royalties are paid on franchised sales, so this line grows when restaurants sell more, with no cooking costs attached. Investors should ask how much of the other $1.61 B comes from that same engine.
Franchise fees are small, at $40.00 M, so their drop is a signal rather than a drag. The filing's own commentary ties the higher franchise and property revenues to system-wide sales. Advertising revenues and other services rose 2.9%, against 3.1% for the whole, so it is not the one shrinking. The mix shift is small: Royalties gained 0.5 points of share, to 21.7% of revenue. Read against the whole company, the three lines are a window, not the full picture.
For a reader, royalties are the cleanest line to follow, because they track other people's restaurants. Watch whether royalties keep outgrowing the whole company, and whether franchise fees recover. The missing $1.61 B is the question, because the view cannot say whether it grows with the royalties. A royalty is paid on sales, so it holds up better than a line that depends on the franchisee's margin. Would royalties still lead if the company's restaurant sales were broken out in this same view?